بعبدا في ٥ كانون الثاني ٢٠٢٦
الإمضاء: جوزاف عون
صدر عن رئيس الجمهورية
رئيس مجلس الوزراء
الإمضاء: نواف سلام
رئيس مجلس الوزراء
الإمضاء: نواف سلام
The World Bank
… / | Bourie House 119, 5th Floor | Tel: (961-1) 963 300 INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT
… / | Abdallah Bayhum Street | Fax: (961-1) 963 433 INTERNATIONAL DEVELOPMENT ASSOCIATION
… / | Marffaa, Solidere | Email: [email protected] Jean-Christophe Carret
Country / | P.O. Box 11-8577 | Division Director, Middle East Department
… / | Beirut, Lebanon | Middle East & North Africa Region
Bourie House 119, 5th Floor Abdallah Bayhum Street Marffaa, Solidere P.O. Box 11-8577 Beirut, Lebanon Tel: (961-1) 963 300 Fax: (961-1) 963 433 Email: [email protected] / | |
التاريخ: ۱۷ حزيران/يونيو ۲۰۲٥
معالي السيد ياسين جابر
وزير المالية
وزارة المالية
شارع ساحة النجمة
الموازي لساحة رياض الصلح
بيروت
الجمهورية اللبنانية
الموضوع: مشروع الادارة المالية
(القرض رقم 9644-LB)
تعديل على اتفاقية القرض
معالي الوزير ياسين جابر المحترم،
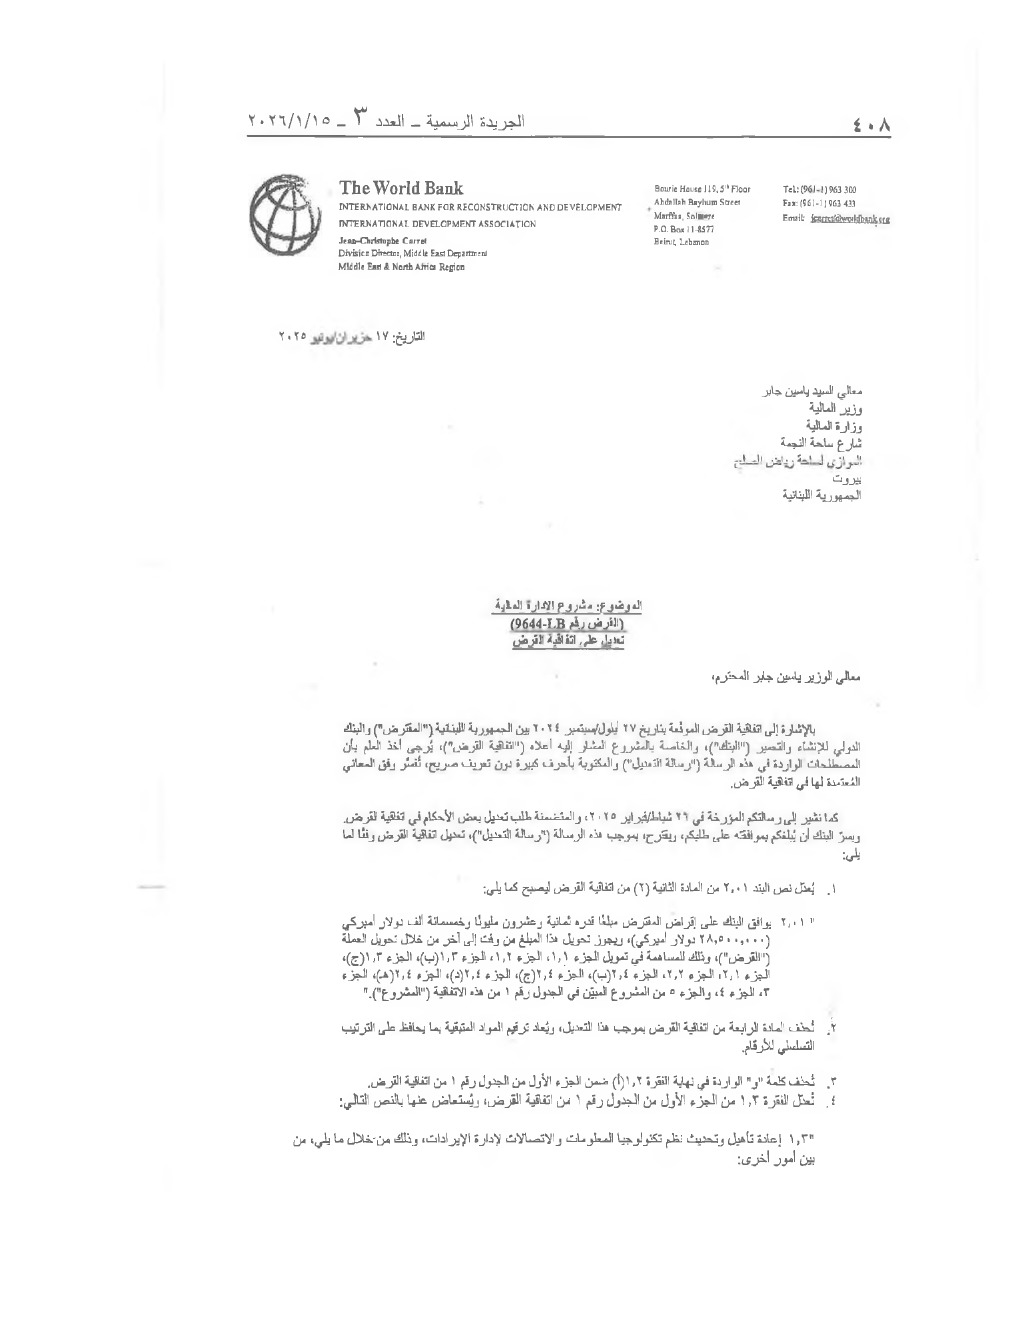
بالإشارة إلى اتفاقية القرض المؤرخة بتاريخ ۲۷ أيلول/سبتمبر ٢٠٢٤ بين الجمهورية اللبنانية ("المقترض") والبنك الدولي للإنشاء والتعمير ("البنك")، والخاصة بالمشروع المشار إليه أعلاه ("اتفاقية القرض")، يُرجى أخذ العلم بأن المصطلحات الواردة في هذه الرسالة ("رسالة التعديل") والمكتوبة بأحرف كبيرة دون تعريف صريح، تُفسّر وفق المعاني المعتمدة لها في اتفاقية القرض.
كما نشير إلى رسالتكم المؤرخة في ٢٦ شباط/فبراير ۲۰۲٥، والمتضمنة طلب تعديل بعض الأحكام في اتفاقية القرض. ويسرّ البنك أن يُبلغكم بموافقته على طلبكم، ويقترح، بموجب هذه الرسالة ("رسالة التعديل")، تعديل اتفاقية القرض وفقاً لما يلي:
١. يُعدل نص البند ۲,۰۱ من المادة الثانية (۲) من اتفاقية القرض ليصبح كما يلي:
" ۲,۰۱ يوافق البنك على إقراض المقترض مبلغاً قدره ثمانية وعشرون مليوناً وخمسمائة الف دولار أميركي (۲۸,۵۰۰,۰۰۰ دولار أميركي)، ويجوز تحويل هذا المبلغ من وقت إلى آخر من خلال تحويل العملة ("القرض")، وذلك للمساهمة في تمويل الجزء ١,١، الجزء ۱٫۲، / ١,٢، الجزء ۱٫۳(ب)، / ١,٣(ب)، الجزء ۱٫۳(ج)، / ١,٣(ج)، الجزء ۲٫۱، / ٢,١، الجزء ۲٫۲، / ٢,٢، الجزء ٢٫٤(ب)، / ٢,٤(ب)، الجزء ٢٫٤(ج)، / ٢,٤(ج)، الجزء ٢٫٤(د)، / ٢,٤(د)، الجزء ٢٫٤(هـ)، / ٢,٤(هـ)، الجزء ۳، الجزء ٤، والجزء ٥ من المشروع المبيّن في الجدول رقم 1 من هذه الاتفاقية ("المشروع")."
٢. تُحذف المادة الرابعة من اتفاقية القرض بموجب هذا التعديل، ويُعاد ترقيم المواد المتبقية بما يحافظ على الترتيب التسلسلي للأرقام.
٣. تُحذف كلمة "و" الواردة في نهاية الفقرة ۱,۲ (أ) / ١,٢(أ) ضمن الجزء الأول من الجدول رقم 1 من اتفاقية القرض.
٤. تُعدل الفقرة ۱,۳ من الجزء الأول من الجدول رقم 1 من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
"۱,۳ إعادة تأهيل وتحديث نظم تكنولوجيا المعلومات والاتصالات لإدارة الإيرادات، وذلك من خلال ما يلي، من بين أمور أخرى:
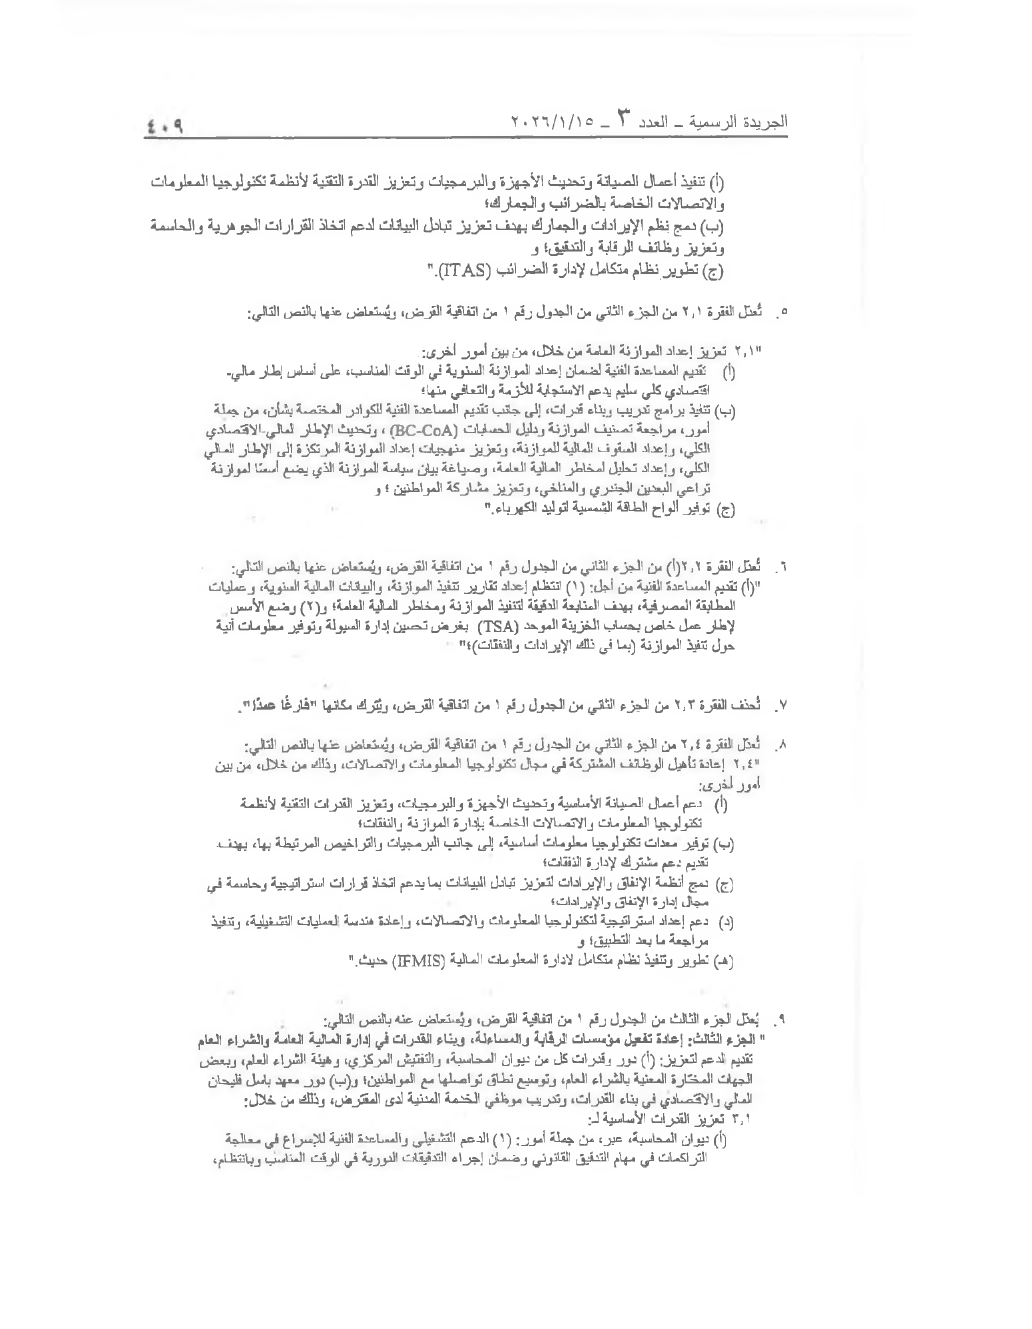
(أ) تنفيذ أعمال الصيانة وتحديث الأجهزة والبرمجيات وتعزيز القدرة التقنية لأنظمة تكنولوجيا المعلومات والاتصالات الخاصة بالضرائب والجمارك؛
(ب) دمج نظم الإيرادات والجمارك بهدف تعزيز تبادل البيانات لدعم اتخاذ القرارات الجوهرية والحاسمة وتعزيز وظائف الرقابة والتدقيق؛ و
(ج) تطوير نظام متكامل لإدارة الضرائب (ITAS)."
٥. تُعدل الفقرة ٢,١ من الجزء الثاني من الجدول رقم ١ من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
"٢,١ تعزيز إعداد الموازنة العامة من خلال، من بين أمور أخرى:
(أ) تقديم المساعدة الفنية لضمان إعداد الموازنة السنوية في الوقت المناسب، على أساس إطار مالي-اقتصادي كلي سليم يدعم الاستجابة للأزمة والتعافي منها؛
(ب) تنفيذ برامج تدريب وبناء قدرات، إلى جانب تقديم المساعدة الفنية للكوادر المختصة بشأن، من جملة أمور، مراجعة تصنيف الموازنة ودليل الحسابات (BC-CoA) ، وتحديث الإطار المالي-الاقتصادي الكلي، وإعداد السقوف المالية للموازنة، وتعزيز منهجيات إعداد الموازنة المرتكزة إلى الإطار المالي الكلي، وإعداد تحليل لمخاطر المالية العامة، وصياغة بيان سياسة الموازنة الذي يضع أسسًا لموازنة تراعي البعدين الجندري والمناخي، وتعزيز مشاركة المواطنين ؛ و
(ج) توفير ألواح الطاقة الشمسية لتوليد الكهرباء."
٦. تُعدل الفقرة ٢,٢(أ) من الجزء الثاني من الجدول رقم ١ من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
"(أ) تقديم المساعدة الفنية من أجل: (١) انتظام إعداد تقارير تنفيذ الموازنة، والبيانات المالية السنوية، وعمليات المطابقة المصرفية، بهدف المتابعة الدقيقة لتنفيذ الموازنة ومخاطر المالية العامة؛ و(٢) وضع الأسس لإطار عمل خاص بحساب الخزينة الموحد (TSA) بغرض تحسين إدارة السيولة وتوفير معلومات آنية حول تنفيذ الموازنة (بما في ذلك الإيرادات والنفقات)؛"
٧. تُحذف الفقرة ٢,٣ من الجزء الثاني من الجدول رقم ١ من اتفاقية القرض، ويُترك مكانها "فارغًا عمدًا".
٨. تُعدل الفقرة ٢,٤ من الجزء الثاني من الجدول رقم ١ من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
"٢,٤ إعادة تأهيل الوظائف المشتركة في مجال تكنولوجيا المعلومات والاتصالات، وذلك من خلال، من بين أمور أخرى:
(أ) دعم أعمال الصيانة الأساسية وتحديث الأجهزة والبرمجيات، وتعزيز القدرات التقنية لأنظمة تكنولوجيا المعلومات والاتصالات الخاصة بإدارة الموازنة والنفقات؛
(ب) توفير معدات تكنولوجيا معلومات أساسية، إلى جانب البرمجيات والتراخيص المرتبطة بها، بهدف تقديم دعم مشترك لإدارة النفقات؛
(ج) دمج أنظمة الإنفاق والإيرادات لتعزيز تبادل البيانات بما يدعم اتخاذ قرارات استراتيجية وحاسمة في مجال إدارة الإنفاق والإيرادات؛
(د) دعم إعداد استراتيجية لتكنولوجيا المعلومات والاتصالات، وإعادة هندسة العمليات التشغيلية، وتنفيذ مراجعة ما بعد التطبيق؛ و
(هـ) تطوير وتنفيذ نظام متكامل لادارة المعلومات المالية (IFMIS) حديث."
٩. يُعدل الجزء الثالث من الجدول رقم ١ من اتفاقية القرض، ويُستعاض عنه بالنص التالي:
" الجزء الثالث: إعادة تفعيل مؤسسات الرقابة والمساءلة، وبناء القدرات في إدارة المالية العامة والشراء العام
تقديم الدعم لتعزيز: (أ) دور وقدرات كل من ديوان المحاسبة، والتفتيش المركزي، وهيئة الشراء العام، وبعض الجهات المختارة المعنية بالشراء العام، وتوسيع نطاق تواصلها مع المواطنين؛ و(ب) دور معهد باسل فليحان المالي والاقتصادي في بناء القدرات، وتدريب موظفي الخدمة المدنية لدى المقترض، وذلك من خلال:
٣,١ تعزيز القدرات الأساسية لـ:
(أ) ديوان المحاسبة، عبر، من جملة أمور : (١) الدعم التشغيلي والمساعدة الفنية للإسراع في معالجة التراكمات في مهام التدقيق القانوني وضمان إجراء التدقيقات الدورية في الوقت المناسب وبانتظام،
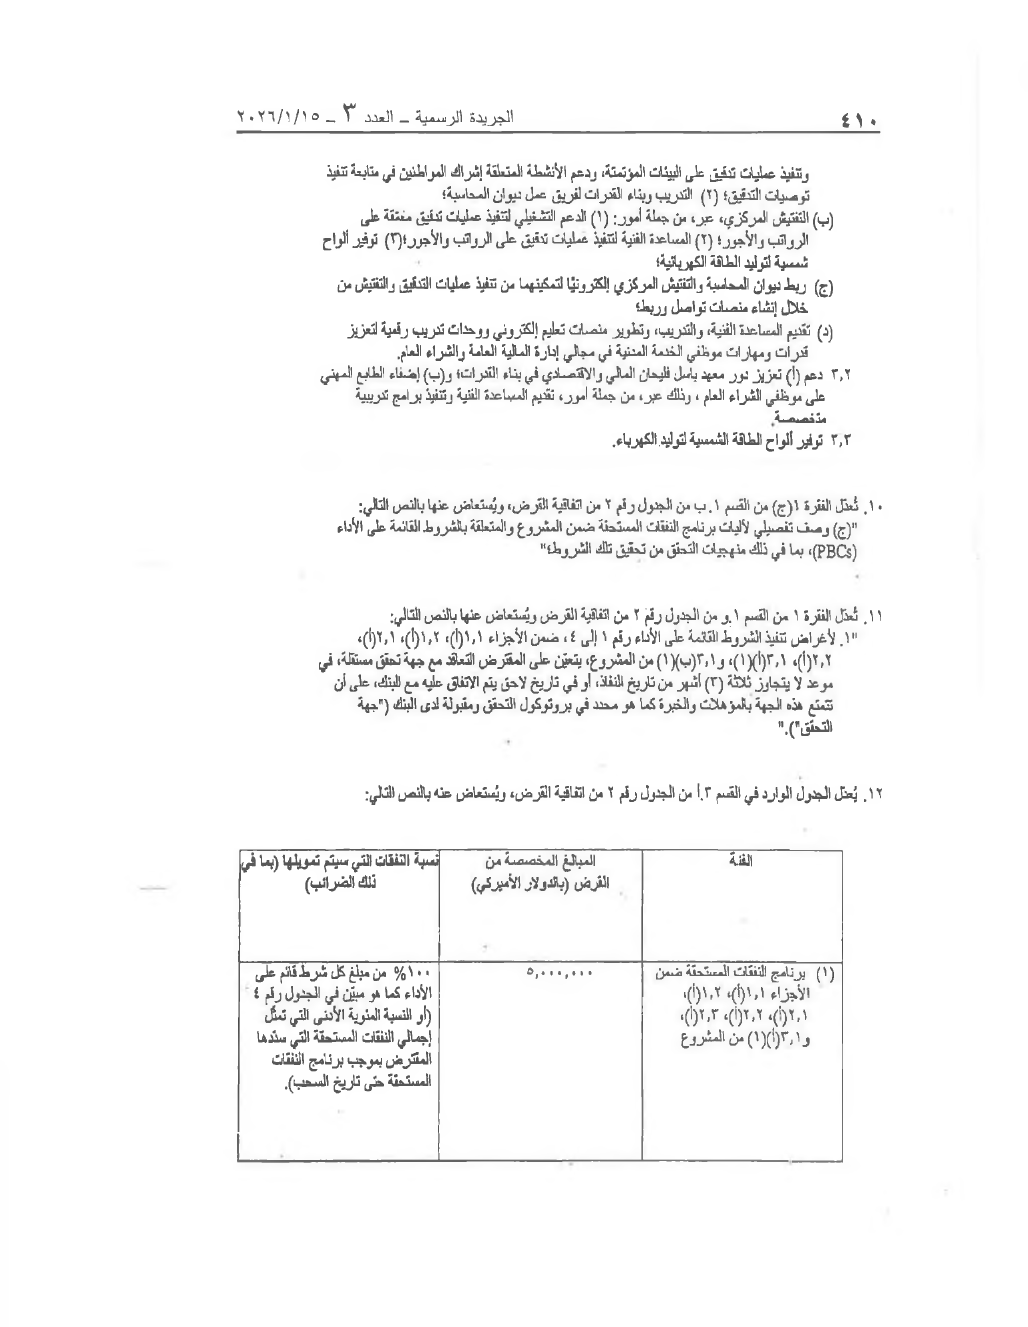
وتنفيذ عمليات تدقيق على البيئات المؤتمتة، ودعم الأنشطة المتعلقة إشراك المواطنين في متابعة تنفيذ توصيات التدقيق؛ (۲) التدريب وبناء القدرات لفريق عمل ديوان المحاسبة؛
(ب) التفتيش المركزي، عبر، من جملة أمور: (۱) الدعم التشغيلي لتنفيذ عمليات تدقيق معمقة على الرواتب والأجور؛ (۲) المساعدة الفنية لتنفيذ عمليات تدقيق على الرواتب والأجور؛ (۳) توفير ألواح شمسية لتوليد الطاقة الكهربائية؛
(ج) ربط ديوان المحاسبة والتفتيش المركزي إلكترونيا لتمكينهما من تنفيذ عمليات التدقيق والتفتيش من خلال إنشاء منصات تواصل وربط؛
(د) تقديم المساعدة الفنية، والتدريب، وتطوير منصات تعليم إلكتروني ووحدات تدريب رقمية لتعزيز قدرات ومهارات موظفي الخدمة المدنية في مجالي إدارة المالية العامة والشراء العام.
۳,۲ دعم (أ) تعزيز دور معهد باسل فليحان المالي والاقتصادي في بناء القدرات، و(ب) إضفاء الطابع المهني على موظفي الشراء العام، ، وذلك عبر، من جملة أمور، تقديم المساعدة الفنية وتنفيذ برامج تدريبية متخصصة.
۳,۳ توفير ألواح الطاقة الشمسية لتوليد الكهرباء.
۱۰. تُعدّل الفقرة ۱(ج) من القسم ۱ .ب من الجدول رقم ۲ من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
"(ج) وصف تفصيلي لآليات برنامج النفقات المستحقة ضمن المشروع والمتعلقة بالشروط القائمة على الأداء (PBCs)، بما في ذلك منهجيات التحقق من تحقيق تلك الشروط؛"
۱۱. تُعدّل الفقرة ۱ من القسم ١.و من الجدول رقم ۲ من اتفاقية القرض ويُستعاض عنها بالنص التالي:
"۱. لأغراض تنفيذ الشروط القائمة على الأداء رقم ۱ إلى ٤، ضمن الأجزاء ۱,۱(أ)، ۱,۲(أ)، ۲,۱(أ)، ۲,۲(أ)، ۳,۱(أ)(۱)، و۳,۱(ب)(۱) من المشروع، يتعين على المقترض التعاقد مع جهة تحقق مستقلة، في موعد لا يتجاوز ثلاثة (۳) أشهر من تاريخ النفاذ، أو في تاريخ لاحق يتم الاتفاق عليه مع البنك، على أن تتمتع هذه الجهة بالمؤهلات والخبرة كما هو محدد في بروتوكول التحقق ومقبولة لدى البنك ("جهة التحقق")."
۱۲. يُعدّل الجدول الوارد في القسم ۳. أ / ٣.أ من الجدول رقم ۲ من اتفاقية القرض، ويُستعاض عنه بالنص التالي:
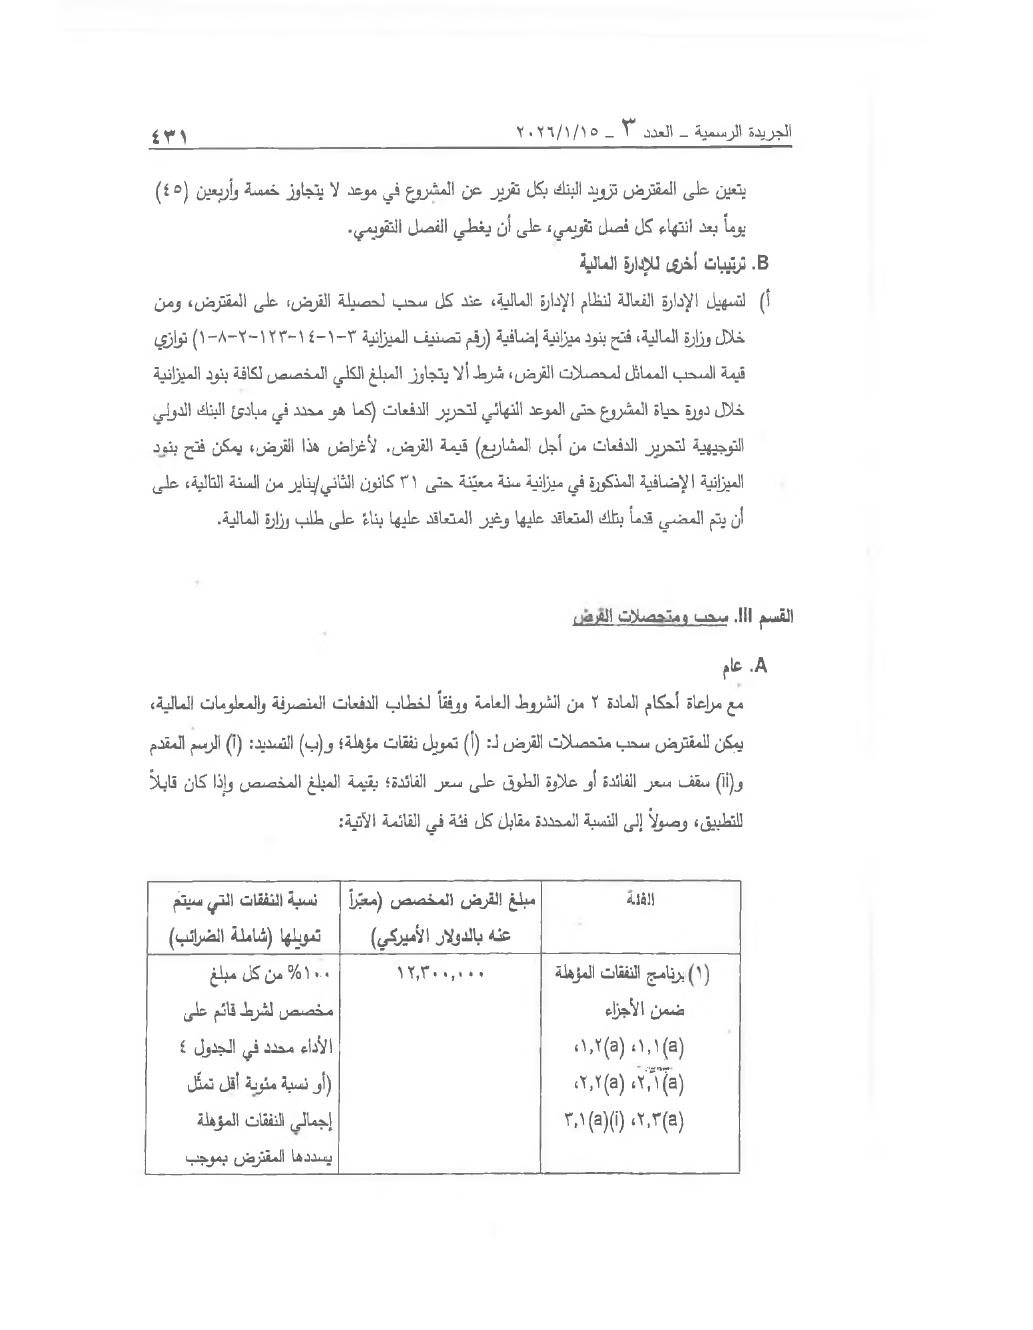
الفئة | المبالغ المخصصة من القرض (بالدولار الأميركي) | نسبة النفقات التي سيتم تمويلها (بما في ذلك الضرائب)
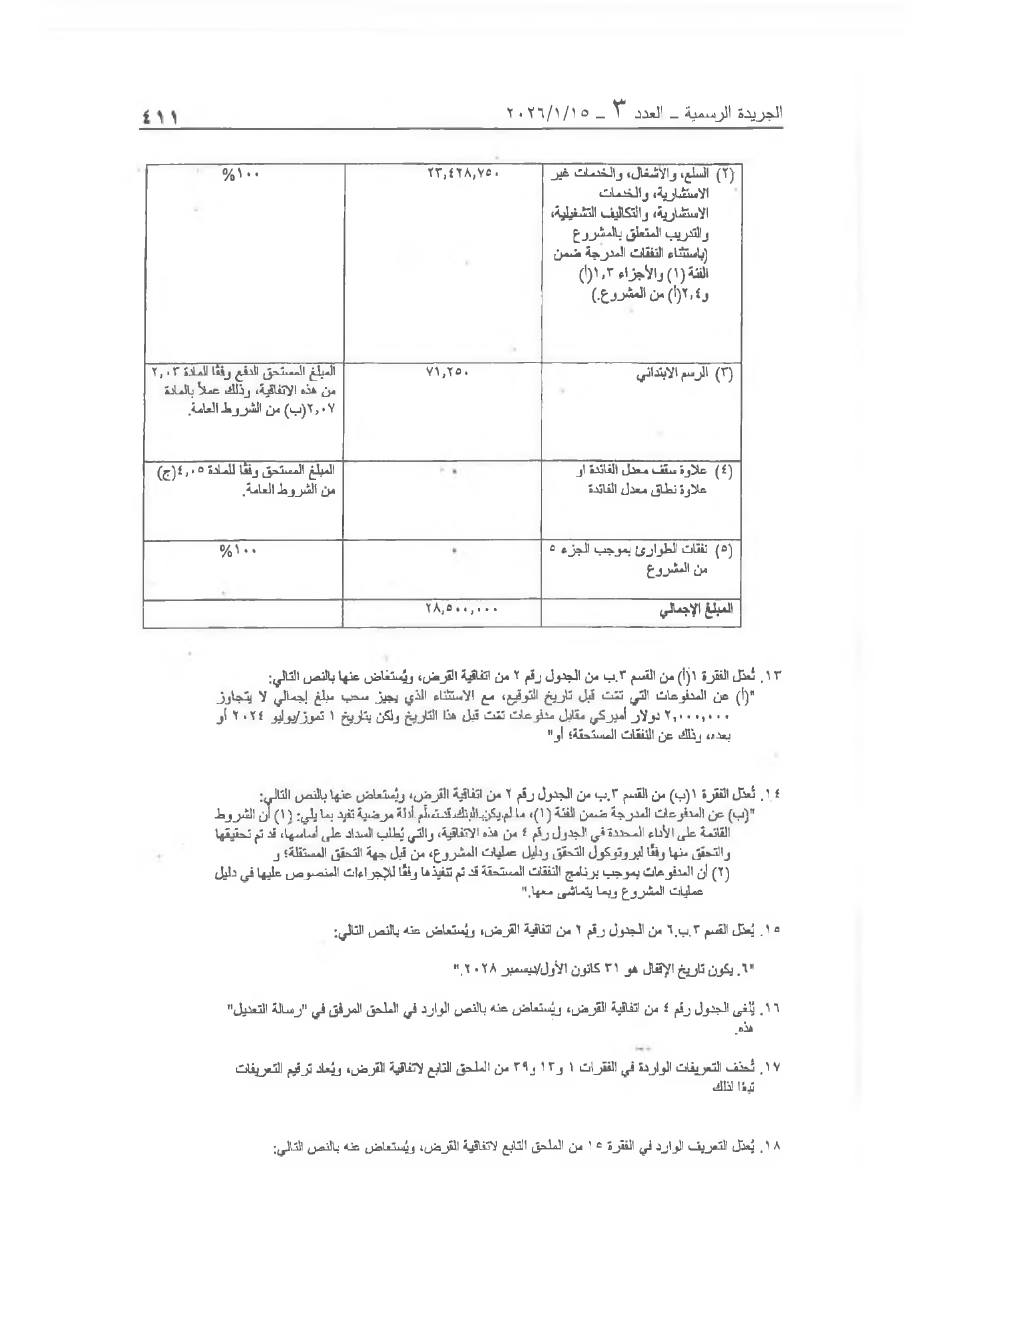
(۱) برنامج النفقات المستحقة ضمن الأجزاء ۱,۱(أ)، ۱,۲(أ)، ۲,۱(أ)، ۲,۲(أ)، … / ٢,٣(أ)، و۳,۱(أ)(۱) من المشروع | ٥,٠٠٠,٠٠٠ | %۱۰۰ / ١٠٠% من مبلغ كل شرط قائم على الأداء كما هو مبين في الجدول رقم ٤ (أو النسبة المئوية الأدنى التي تمثل إجمالي النفقات المستحقة التي سددها المقترض بموجب برنامج النفقات المستحقة حتى تاريخ السحب).
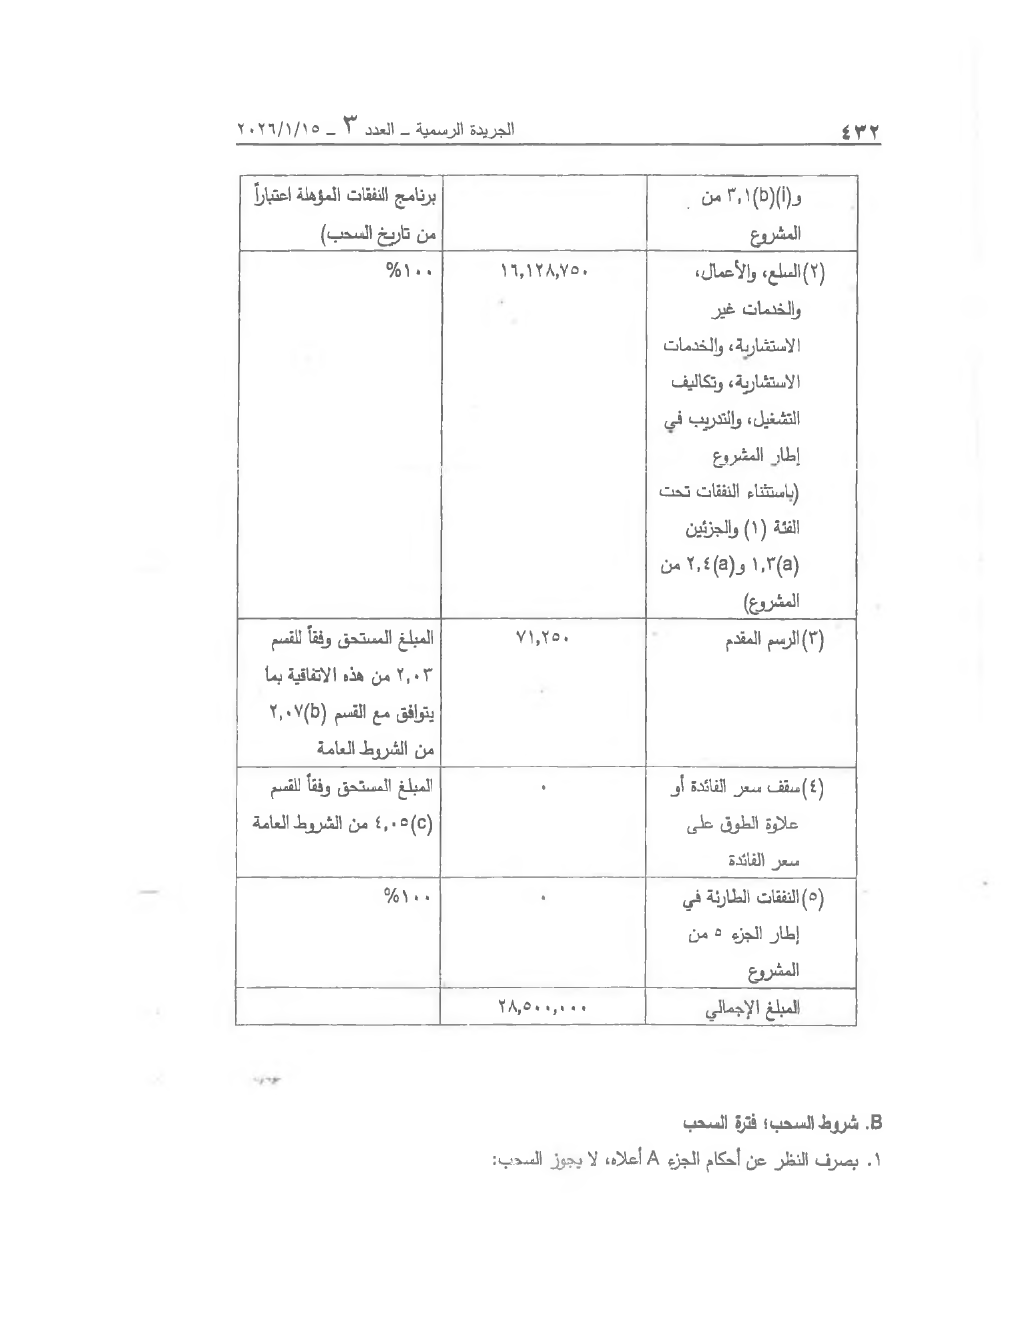
(٢) السلع، والأشغال، والخدمات غير الاستشارية، والخدمات الاستشارية، والتكاليف التشغيلية، والتدريب المتعلق بالمشروع (باستثناء النفقات المدرجة ضمن الفئة (١) والأجزاء ١,٣ (أ) و ٤,٢(أ) / ١.٣(أ) و٢.٤(أ) من المشروع.) | ٢٣,٤٢٨,٧٥٠ | %١٠٠
(٣) الرسم الابتدائي | ٧١,٢٥٠ | المبلغ المستحق الدفع وفقًا للمادة ٢,٠٣ من هذه الاتفاقية، وذلك عملاً بالمادة ٢,٠٧(ب) من الشروط العامة.
(٤) علاوة سقف معدل الفائدة أو علاوة نطاق معدل الفائدة | * | المبلغ المستحق وفقًا للمادة ٤,٠٥ (ج) / ٤.٠٥(ج) من الشروط العامة.
(٥) نفقات الطوارئ بموجب الجزء ٥ من المشروع | * | %١٠٠
المبلغ الإجمالي | ٢٨,٥٠٠,٠٠٠
… / | ١٣. تُعدّل الفقرة ١(أ) من القسم ٣.ب من الجدول رقم ٢ من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
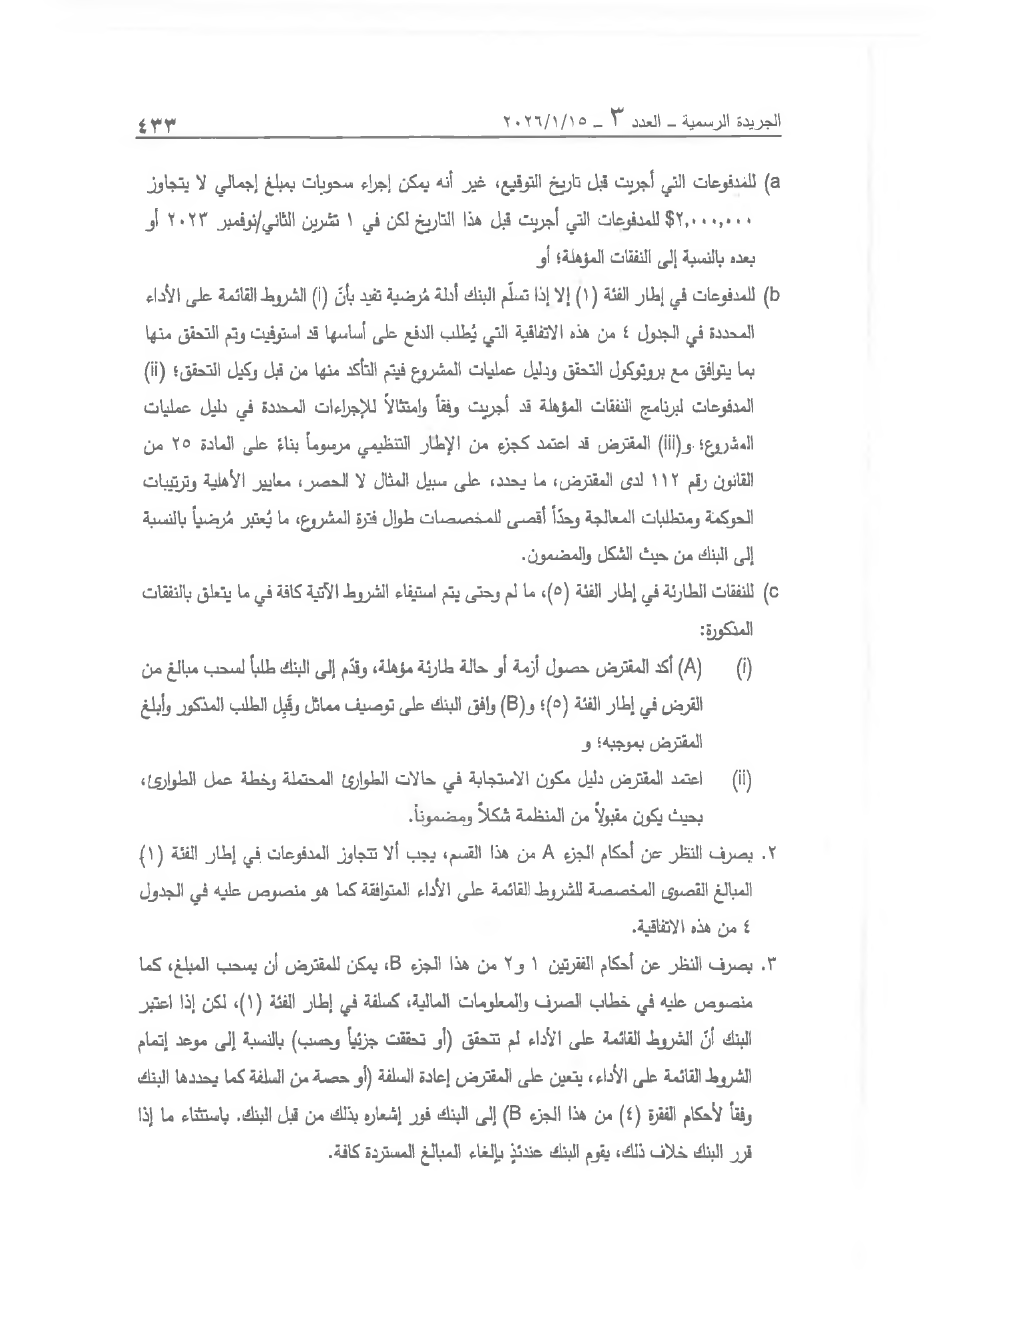
"(أ) عن المدفوعات التي تمّت قبل تاريخ التوقيع، مع الاستثناء الذي يجيز سحب مبلغ إجمالي لا يتجاوز ٢,٠٠٠,٠٠٠ دولار أميركي مقابل مدفوعات تمّت قبل هذا التاريخ ولكن بتاريخ ١ تموز/يوليو ٢٠٢٤ أو بعده، وذلك عن النفقات المستحقة؛ أو"
١٤. تُعدّل الفقرة ١(ب) من القسم ٣.ب من الجدول رقم ٢ من اتفاقية القرض، ويُستعاض عنها بالنص التالي:
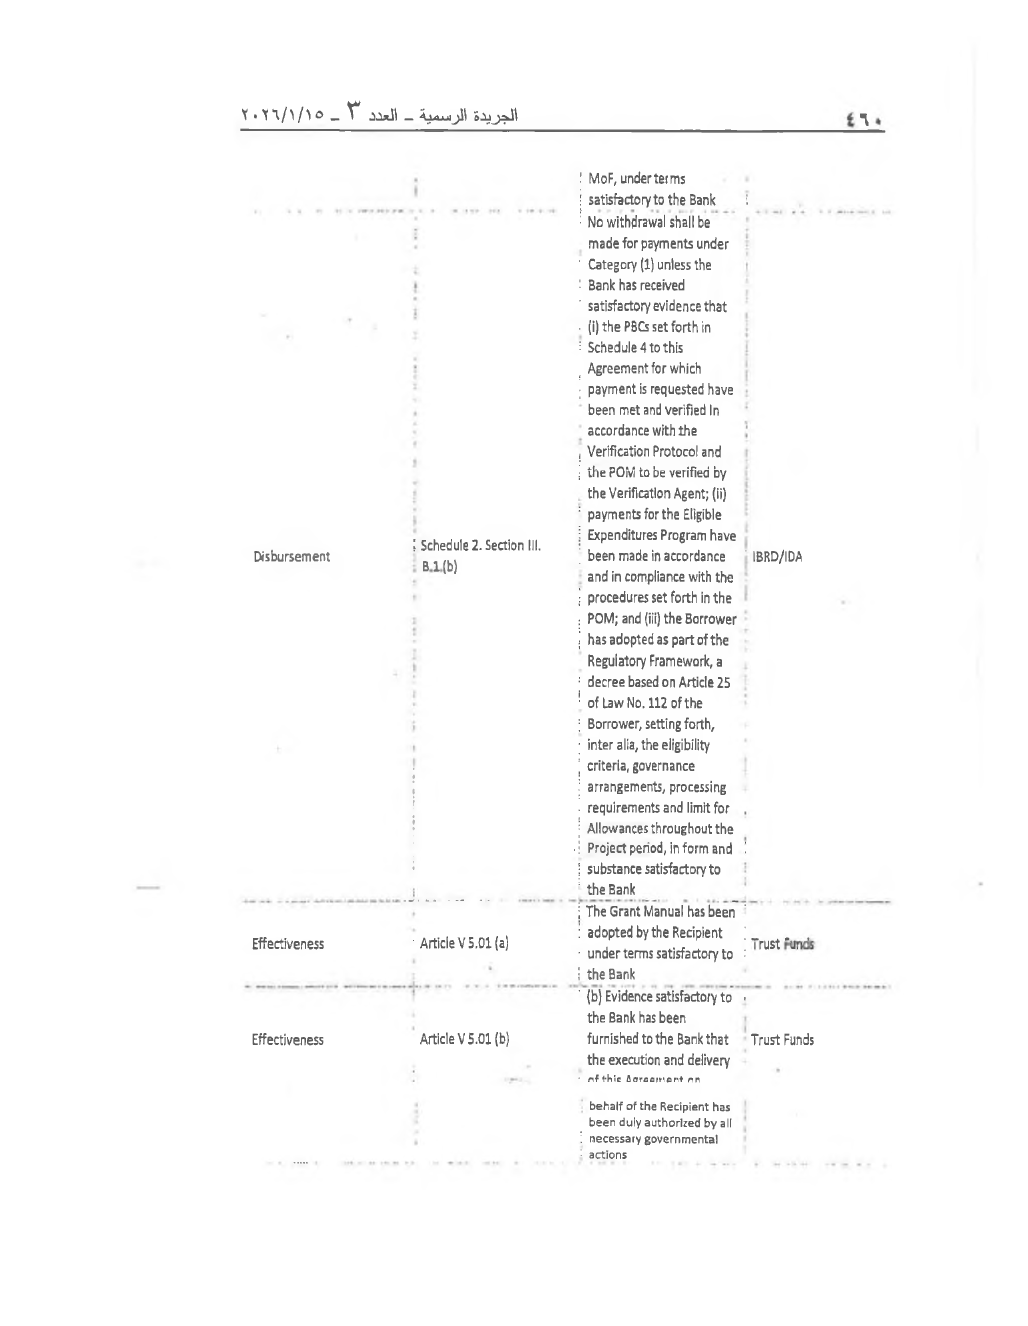
"(ب) عن المدفوعات المدرجة ضمن الفئة (١)، ما لم يكن البنك قد تسلّم أدلّة مرضية تفيد بما يلي: (١) أن الشروط القائمة على الأداء المحددة في الجدول رقم ٤ من هذه الاتفاقية، والتي يُطلب السداد على أساسها، قد تم تحقيقها والتحقق منها وفقًا لبروتوكول التحقق ودليل عمليات المشروع، من قِبل جهة التحقق المستقلة؛ و (٢) أن المدفوعات بموجب برنامج النفقات المستحقة قد تم تنفيذها وفقًا للإجراءات المنصوص عليها في دليل عمليات المشروع وبما يتماشى معها."
١٥. يُعدل القسم ٣.ب.٦ من الجدول رقم ٢ من اتفاقية القرض، ويُستعاض عنه بالنص التالي:
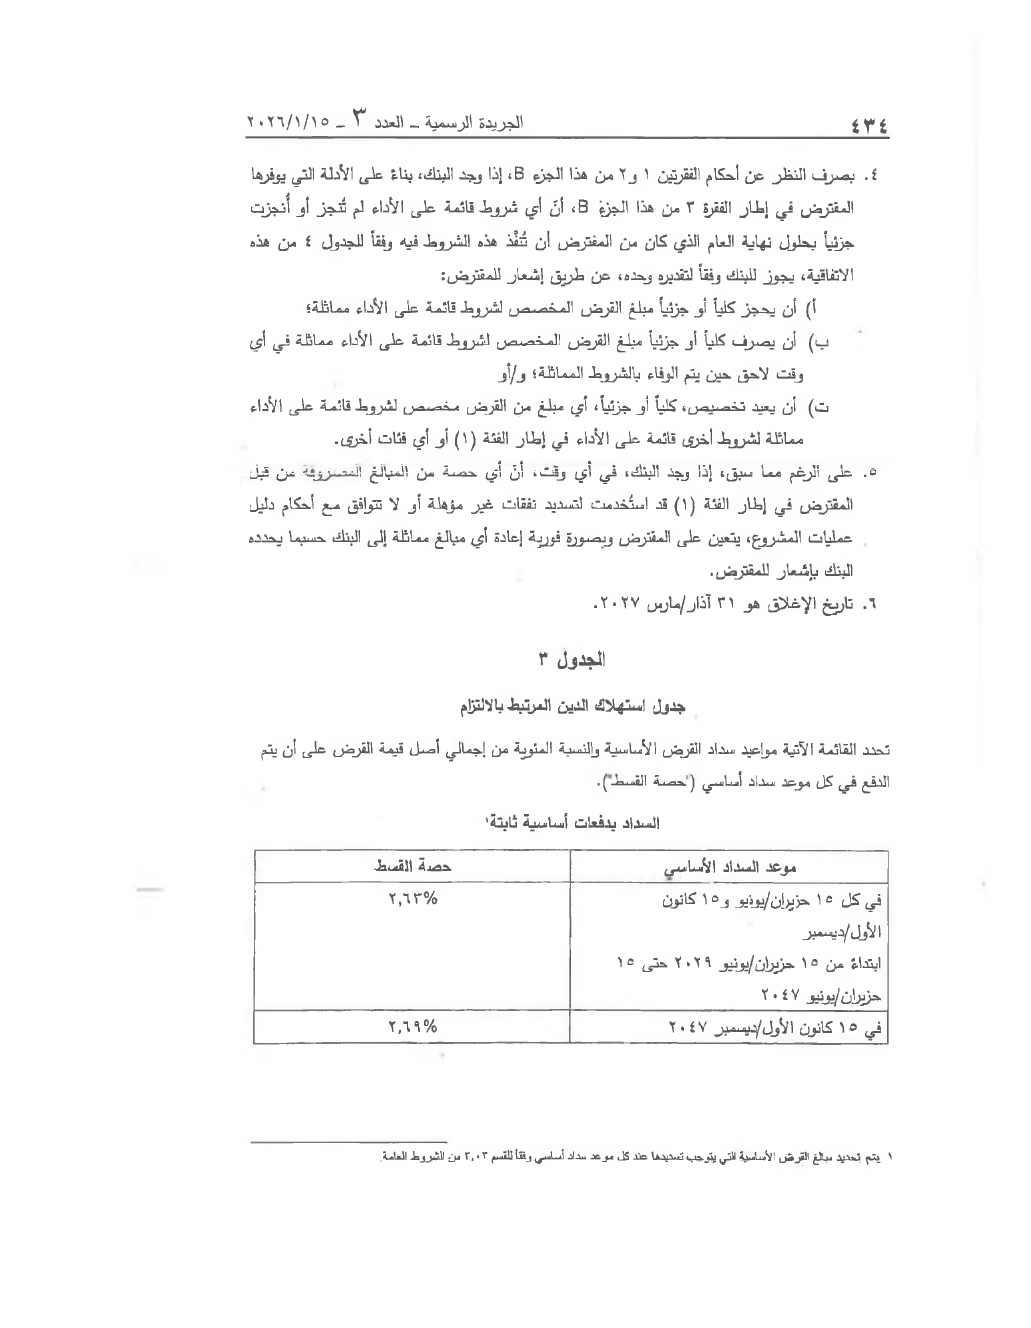
"٦. يكون تاريخ الإقفال هو ٣١ كانون الأول/ديسمبر ٢٠٢٨."
١٦. يُلغى الجدول رقم ٤ من اتفاقية القرض، ويُستعاض عنه بالنص الوارد في الملحق المرفق في "رسالة التعديل" هذه.
١٧. تُحذف التعريفات الواردة في الفقرات ١ و ١٢ و ٣٩ / و١٣ و٣٩ من الملحق التابع لاتفاقية القرض، ويُعاد ترقيم التعريفات تبعًا لذلك.
١٨. يُعدل التعريف الوارد في الفقرة ١٥ من الملحق التابع لاتفاقية القرض، ويُستعاض عنه بالنص التالي:
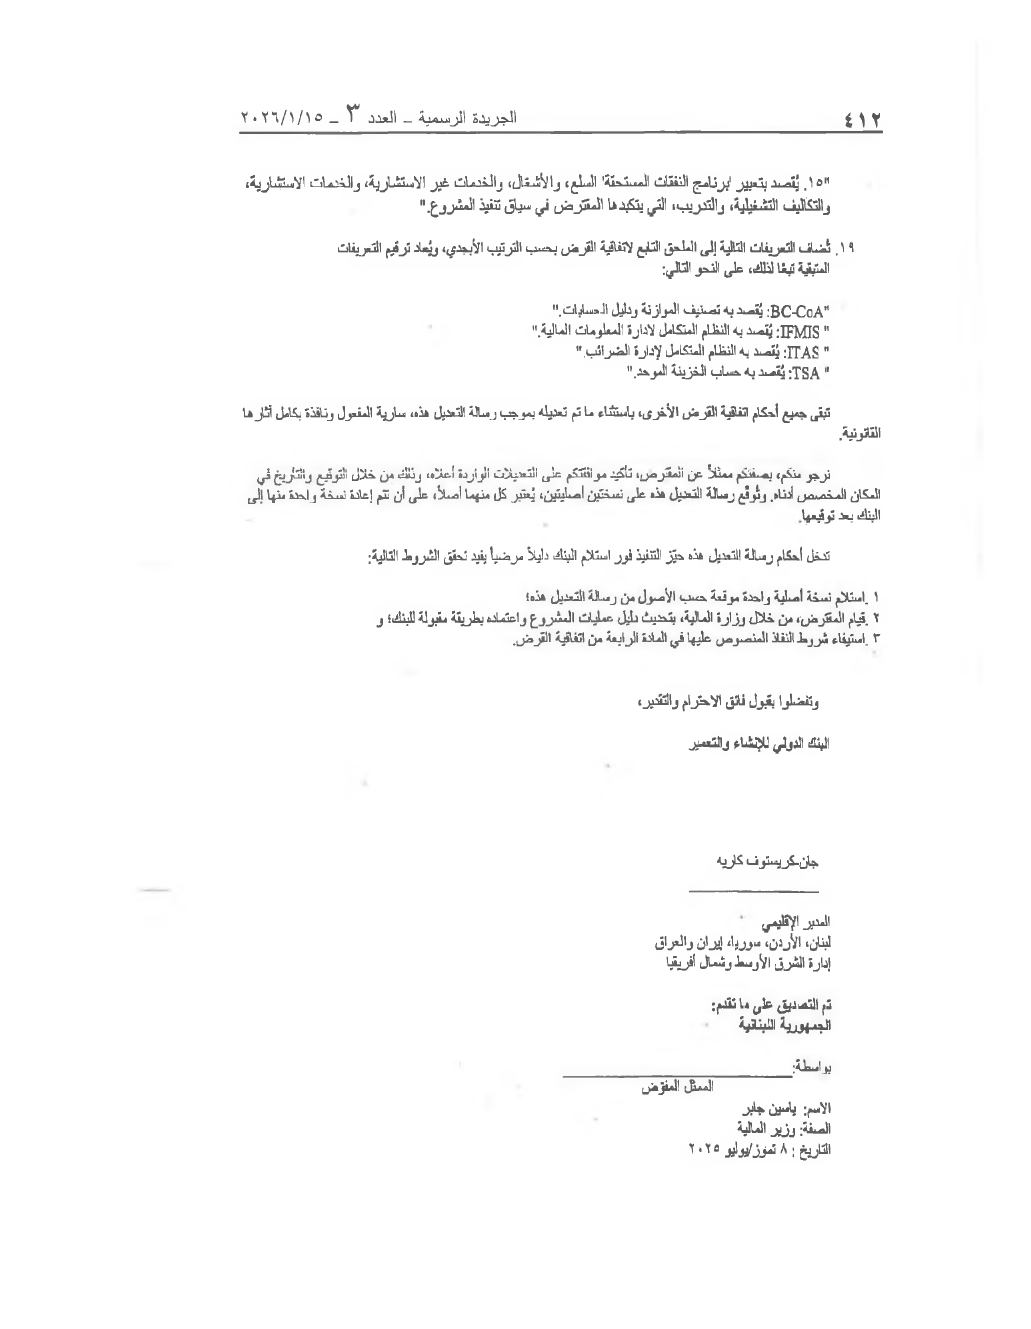
"١٥. يُقصد بتعبير 'برنامج النفقات المستحقة' السلع، والأشغال، والخدمات غير الاستشارية، والخدمات الاستشارية، والتكاليف التشغيلية، والتدريب، التي يتكبدها المقترض في سياق تنفيذ المشروع."
۱۹. تُضاف التعريفات التالية إلى الملحق التابع لاتفاقية القرض بحسب الترتيب الأبجدي، ويُعاد ترقيم التعريفات المتبقية تبعًا لذلك، على النحو التالي:
"BC-CoA: يُقصد به تصنيف الموازنة ودليل الحسابات."
" "IFMIS: يُقصد به النظام المتكامل لإدارة المعلومات المالية."
" "ITAS: يُقصد به النظام المتكامل لإدارة الضرائب."
" "TSA: يُقصد به حساب الخزينة الموحد."
تبقى جميع أحكام اتفاقية القرض الأخرى، باستثناء ما تم تعديله بموجب رسالة التعديل هذه، سارية المفعول ونافذة بكامل آثارها القانونية.
نرجو منكم، بصفتكم ممثلاً عن المقترض، تأكيد موافقتكم على التعديلات الواردة أعلاه، وذلك من خلال التوقيع والتاريخ في المكان المخصص أدناه. وتُوقع رسالة التعديل هذه على نسختين أصليتين، يُعتبر كل منهما أصلاً، على أن تتم إعادة نسخة واحدة منها إلى البنك بعد توقيعها.
تدخل أحكام رسالة التعديل هذه حيّز التنفيذ فور استلام البنك دليلاً مرضياً يفيد تحقق الشروط التالية:
١. استلام نسخة أصلية واحدة موقعة حسب الأصول من رسالة التعديل هذه؛
٢. قيام المقترض، من خلال وزارة المالية، بتحديث دليل عمليات المشروع واعتماده بطريقة مقبولة للبنك؛ و
٣. استيفاء شروط النفاذ المنصوص عليها في المادة الرابعة من اتفاقية القرض.
وتفضلوا بقبول فائق الاحترام والتقدير،
البنك الدولي للإنشاء والتعمير
جان-كريستوف كاريه
المدير الإقليمي
لبنان، الأردن، سوريا، إيران والعراق
إدارة الشرق الأوسط وشمال أفريقيا
تم التصديق على ما تقدم:
الجمهورية اللبنانية
بواسطة:
الممثل المفوض
الاسم: ياسين جابر
الصفة: وزير المالية
التاريخ: : ٨ تموز/يوليو ٢٠٢٥
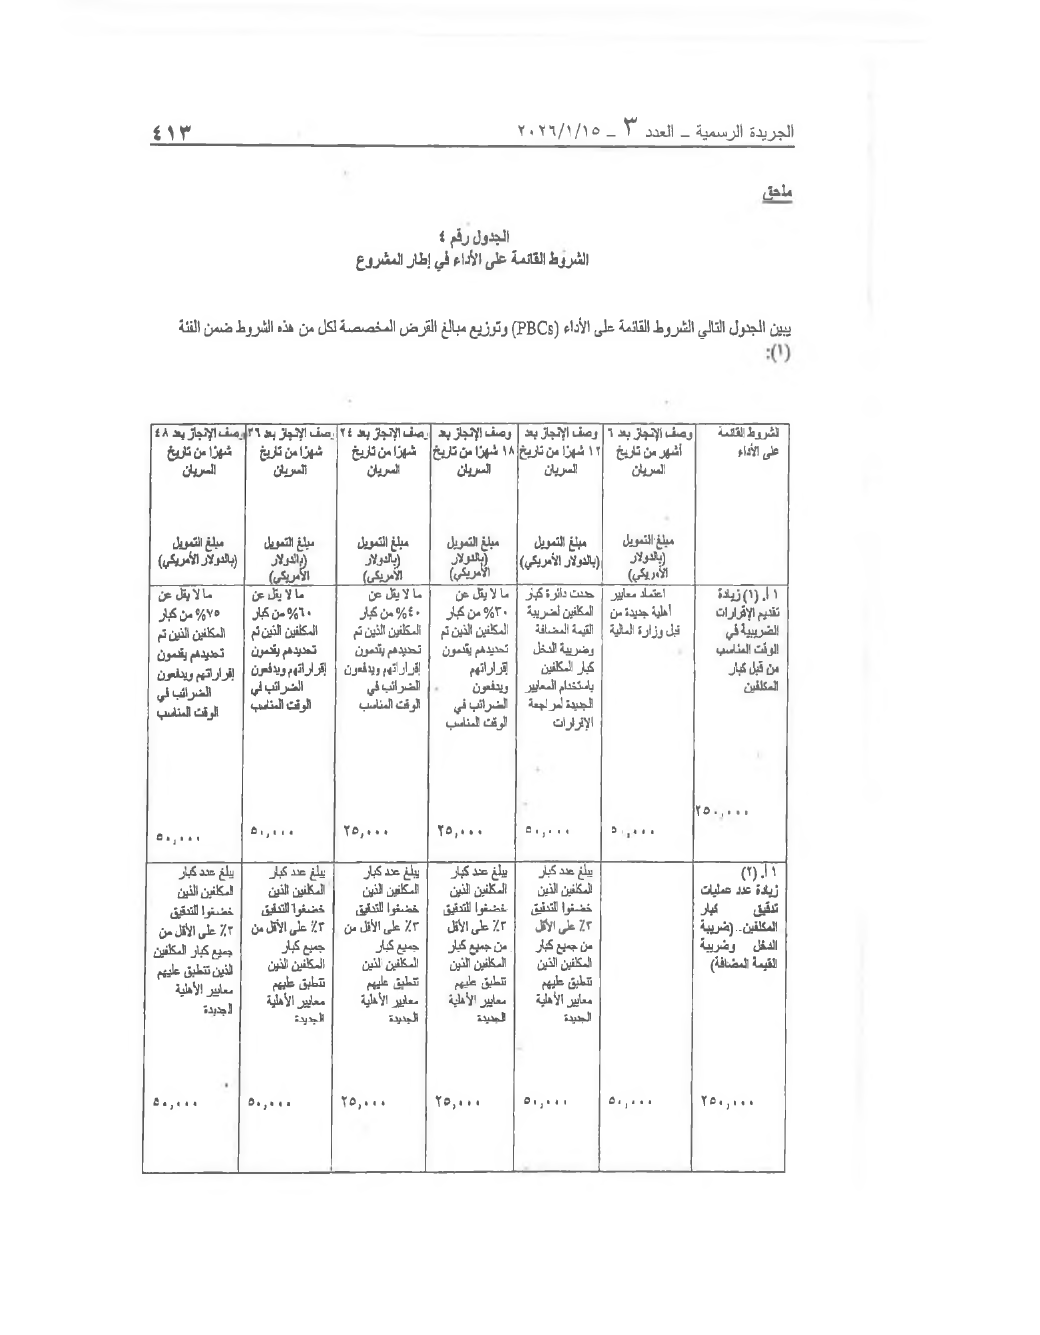
ملحق
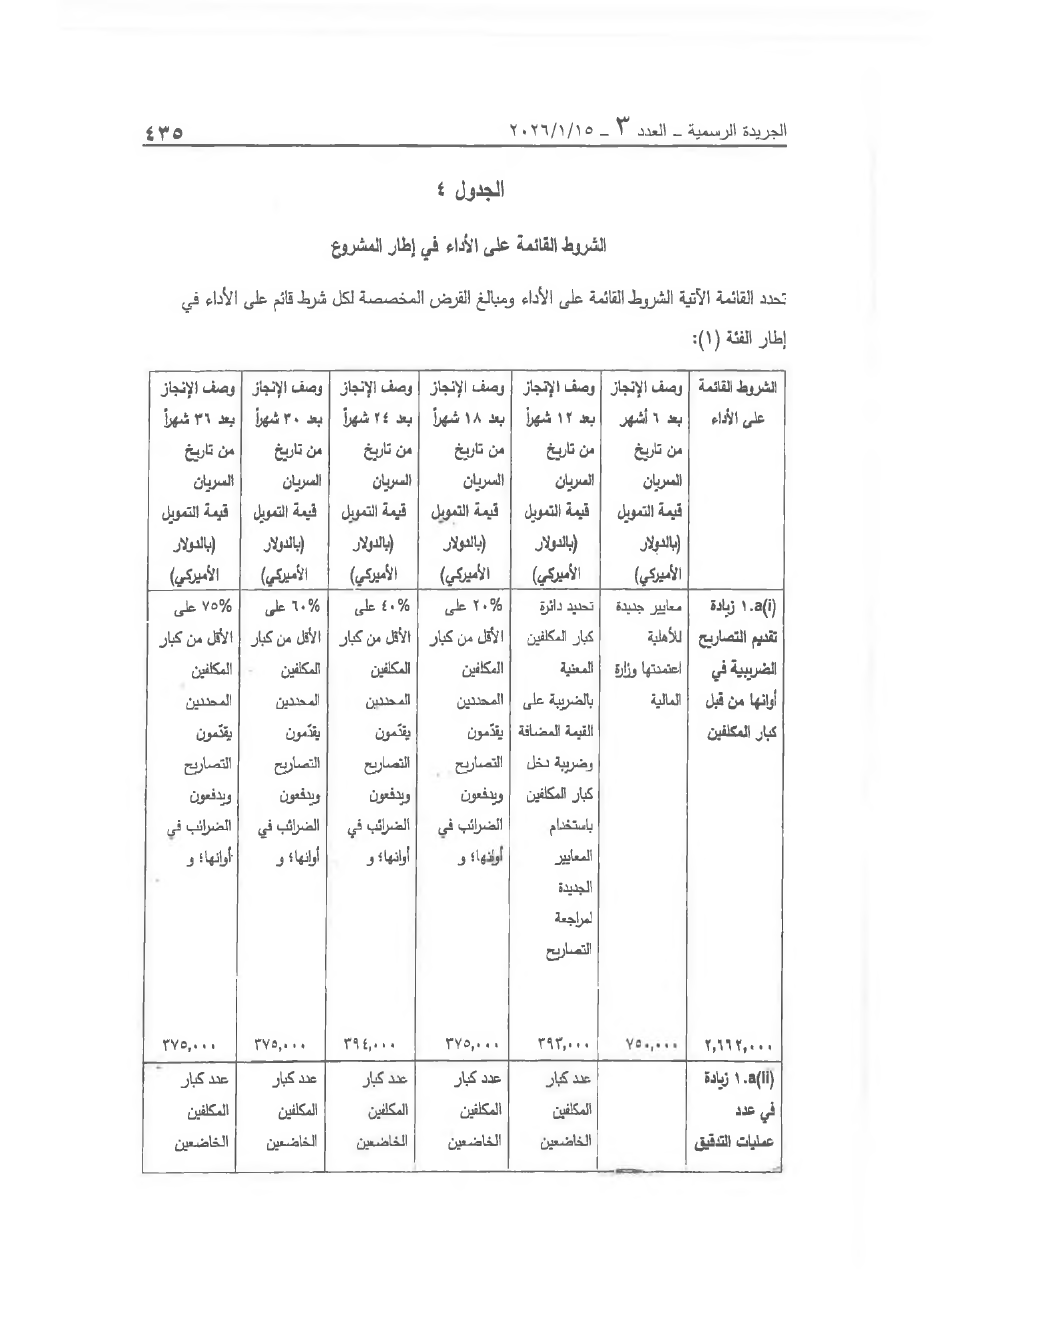
يبين الجدول التالي الشروط القائمة عـ (1):
الشروط القائمة على الأداء | وصف الإنجاز بعد 6 أشهر من تاريخ السريان
| مبلغ التمويل (بالدولار الأمريكي)
1 أ. (1) زيادة تقديم الإقرارات الضريبية في الوقت المناسب من قبل كبار المكلفين 250,000 | اعتماد معايير أهلية جديدة من قبل وزارة المالية 50,000 / ٥,٠٠٠
1 أ. (2) زيادة عدد عمليات تدقيق كبار المكلفين- (ضريبة الدخل وضريبة القيمة المضافة) 250,000 | 50,000
الجدول رقم 4
الشروط القائمة على الأداء في إطار المشروع
لى / على الأداء (PBCs) وتوزيع مبالغ القرض المخصصة لكل من هذه الشروط ضمن الفئة
وصف الإنجاز بعد 12 شهرًا من تاريخ السريان مبلغ التمويل (بالدولار الأمريكي) | وصف الإنجاز بعد 18 شهرًا من تاريخ السريان مبلغ التمويل (بالدولار الأمريكي) | وصف الإنجاز بعد 24 شهرًا من تاريخ السريان مبلغ التمويل (بالدولار الأمريكي) | وصف الإنجاز بعد 36 شهرًا من تاريخ السريان مبلغ التمويل (بالدولار الأمريكي) | وصف الإنجاز بعد 48 شهرًا من تاريخ السريان
مبلغ التمويل (بالدولار الأمريكي) حددت دائرة كبار المكلفين لضريبة القيمة المضافة وضريبة الدخل كبار المكلفين باستخدام المعايير الجديدة لمراجعة الإقرارات 50,000 | ما لا يقل عن %30 / ٣٠% من كبار المكلفين الذين تم تحديدهم يقدمون إقراراتهم ويدفعون الضرائب في الوقت المناسب 25,000 | ما لا يقل عن %40 / ٤٠% من كبار المكلفين الذين تم تحديدهم يقدمون إقراراتهم ويدفعون الضرائب في الوقت المناسب 25,000 | ما لا يقل عن %60 / ٦٠% من كبار المكلفين الذين تم تحديدهم يقدمون إقراراتهم ويدفعون الضرائب في الوقت المناسب 50,000 | ما لا يقل عن %75 / ٧٥% من كبار المكلفين الذين تم تحديدهم يقدمون إقراراتهم ويدفعون الضرائب في الوقت المناسب 50,000
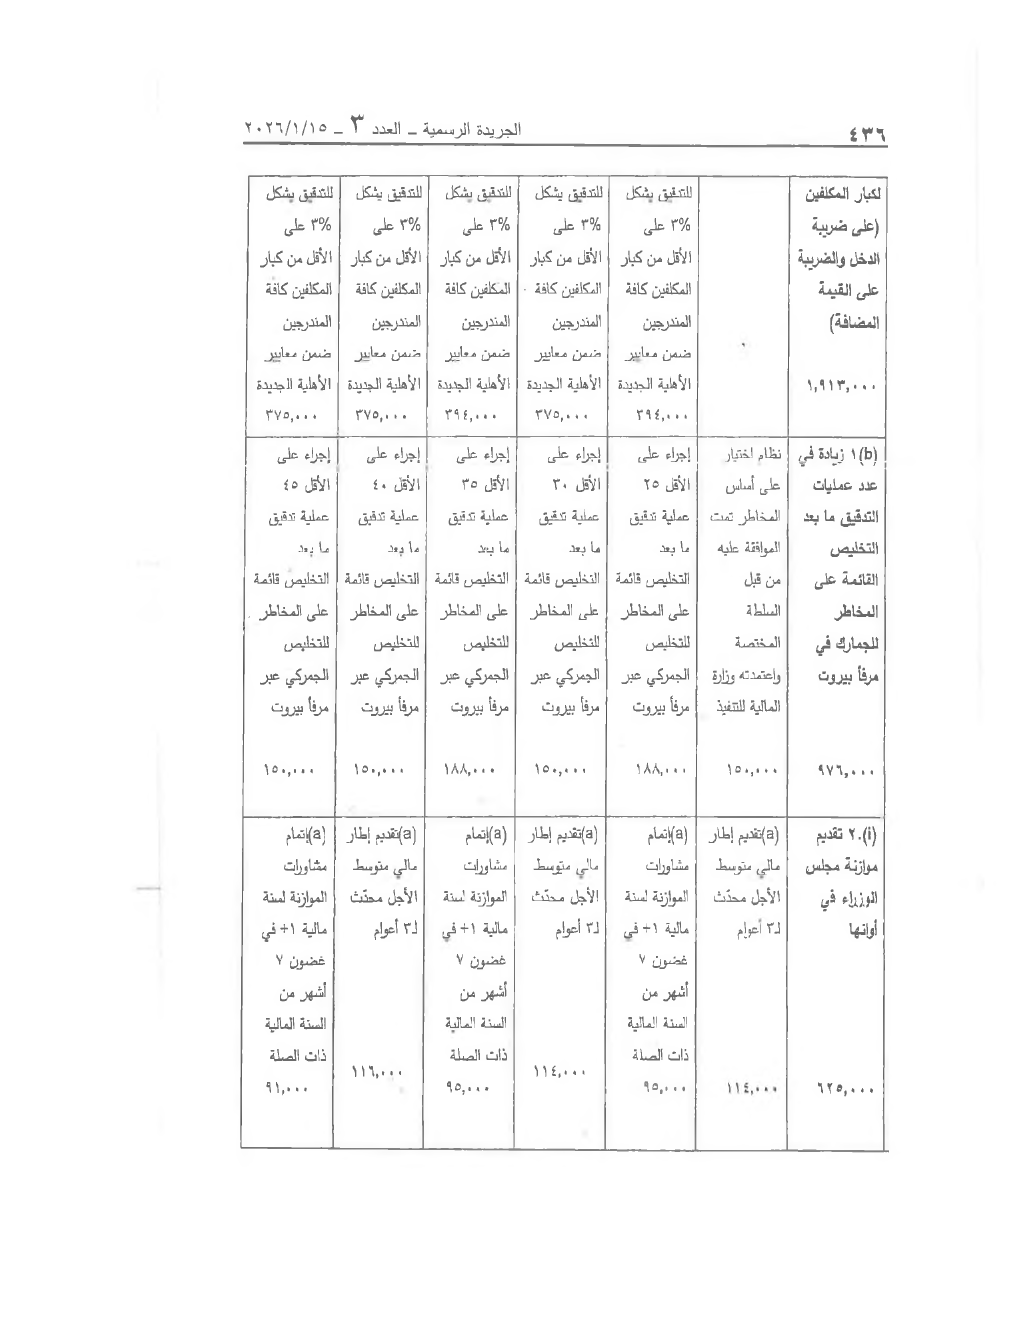
يبلغ عدد كبار المكلفين الذين خضعوا للتدقيق %2 / ٣% على الأقل من جميع كبار المكلفين الذين تنطبق عليهم معايير الأهلية الجديدة 50,000 | يبلغ عدد كبار المكلفين الذين خضعوا للتدقيق %2 / ٣% على الأقل من جميع كبار المكلفين الذين تنطبق عليهم معايير الأهلية الجديدة 25,000 | يبلغ عدد كبار المكلفين الذين خضعوا للتدقيق %2 / ٣% على الأقل من جميع كبار المكلفين الذين تنطبق عليهم معايير الأهلية الجديدة 25,000 | يبلغ عدد كبار المكلفين الذين خضعوا للتدقيق %2 / ٣% على الأقل من جميع كبار المكلفين الذين تنطبق عليهم معايير الأهلية الجديدة 50,000 | يبلغ عدد كبار المكلفين الذين خضعوا للتدقيق %2 / ٣% على الأقل من جميع كبار المكلفين الذين تنطبق عليهم معايير الأهلية الجديدة 50,000
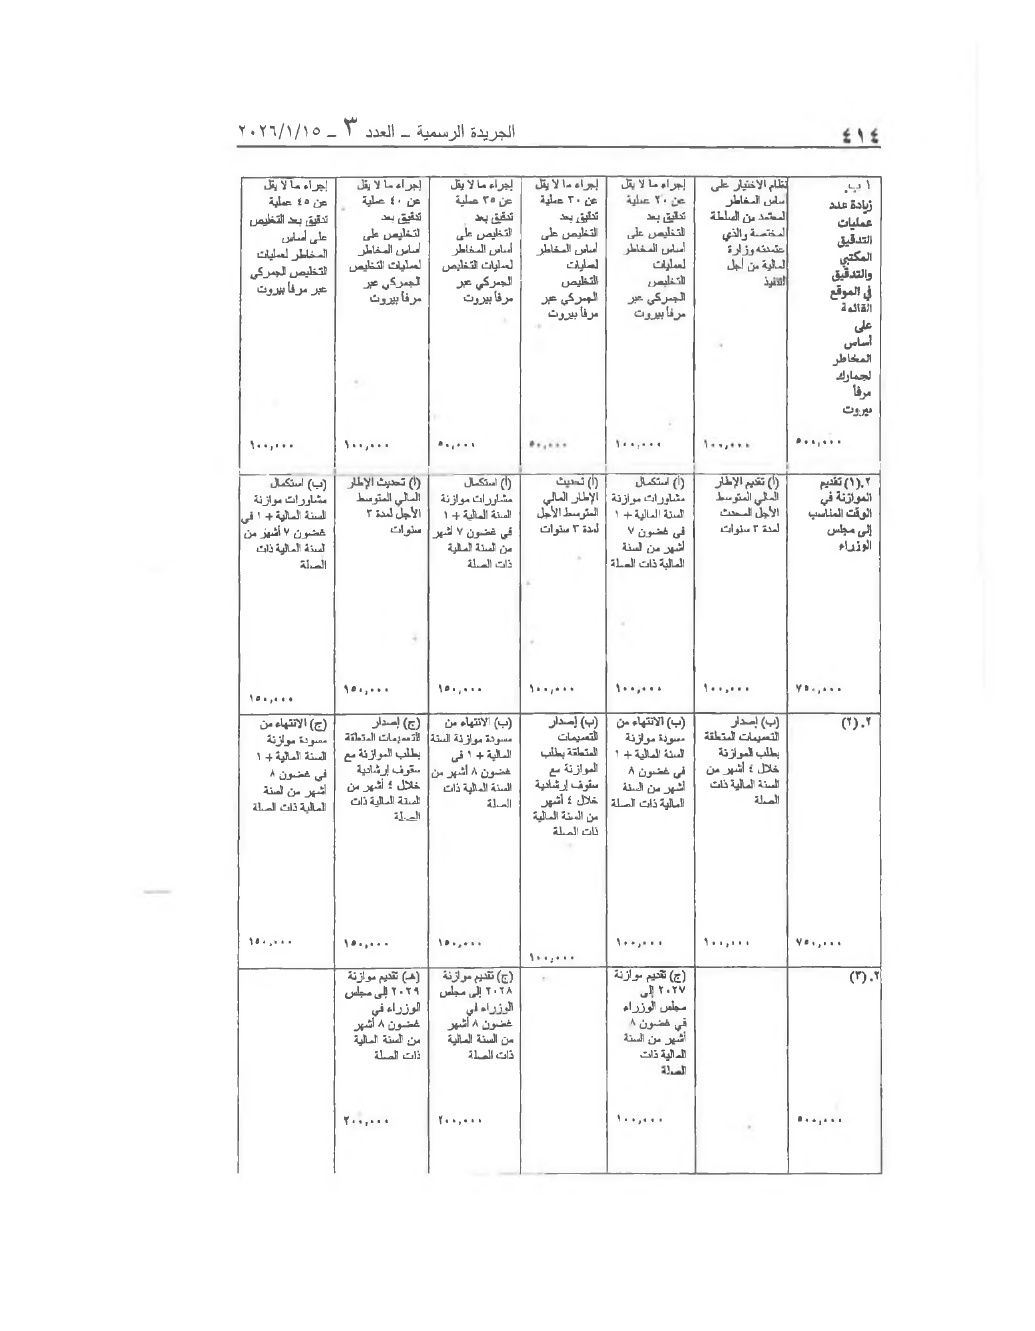
أ. / ١ ب. زيادة عدد عمليات التدقيق المكتبي والتدقيق في الموقع القائمة على أساس المخاطر لجمارك مرفأ بيروت ٥٠٠,٠٠٠ | نظام الاختيار على أساس المخاطر المعتمد من السلطة المختصة والذي اعتمدته وزارة المالية من أجل التنفيذ ۱۰۰,۰۰۰ | إجراء ما لا يقل عن ٢٠ عملية تدقيق بعد التخليص على أساس المخاطر لعمليات التخليص الجمركي عبر مرفأ بيروت ۱۰۰,۰۰۰ | إجراء ما لا يقل عن ٣٠ عملية تدقيق بعد التخليص على أساس المخاطر لعمليات التخليص الجمركي عبر مرفأ بيروت ٥٠,٠٠٠ | إجراء ما لا يقل عن ٣٥ عملية تدقيق بعد التخليص على أساس المخاطر لعمليات التخليص الجمركي عبر مرفأ بيروت ۵۰,۰۰۰
۲. (۱) تقديم الموازنة في الوقت المناسب إلى مجلس الوزراء ۷۵,۰۰۰ / ٧٥٠,٠٠٠ | (أ) تقديم الإطار المالي المتوسط الأجل المحدث لمدة ٣ سنوات ۱۰۰,۰۰۰ | (أ) استكمال مشاورات موازنة السنة المالية + ۱ في غضون ۷ أشهر من السنة المالية ذات الصلة ۱۰۰,۰۰۰ | (أ) تحديث الإطار المالي المتوسط الأجل لمدة ٣ سنوات ۱۰۰,۰۰۰ | (أ) استكمال مشاورات موازنة السنة المالية + ۱ في غضون ۷ أشهر من السنة المالية ذات الصلة ۵۰,۰۰۰
(۲).۲ ۷۵,۰۰۰ / ٢. (٢) ٧٥٠,٠٠٠ | (ب) إصدار التعميمات المتعلقة بطلب الموازنة خلال ٤ أشهر من السنة المالية ذات الصلة ۱۰۰,۰۰۰ | (ب) الانتهاء من مسودة موازنة السنة المالية + ۱ في غضون ٨ أشهر من السنة المالية ذات الصلة ۱۰۰,۰۰۰ | (ب) إصدار التعميمات المتعلقة بطلب الموازنة مع سقوف إرشادية خلال ٤ أشهر من السنة المالية ذات الصلة ۱۰۰,۰۰۰ | (ب) الانتهاء من مسودة موازنة السنة المالية + ۱ في غضون ٨ أشهر من السنة المالية ذات الصلة ۵۰,۰۰۰
(۳).۲ / ٢. (٣) ٥٠٠,٠٠٠ | | (ج) تقديم موازنة ۲۰۲۷ إلى مجلس الوزراء في غضون ٨ أشهر من السنة المالية ذات الصلة ۱۰۰,۰۰۰ | | (ج) تقديم موازنة ۲۰۲۸ إلى مجلس الوزراء في غضون ٨ أشهر من السنة المالية ذات الصلة
… / ٢٠٠,٠٠٠
إجراء ما لا يقل عن ٤٠ عملية تدقيق بعد التخليص على أساس المخاطر لعمليات التخليص الجمركي عبر مرفأ بيروت ۱۰۰,۰۰۰ | إجراء ما لا يقل عن ٤٥ عملية تدقيق بعد التخليص على أساس المخاطر لعمليات التخليص الجمركي عبر مرفأ بيروت ۱۰۰,۰۰۰
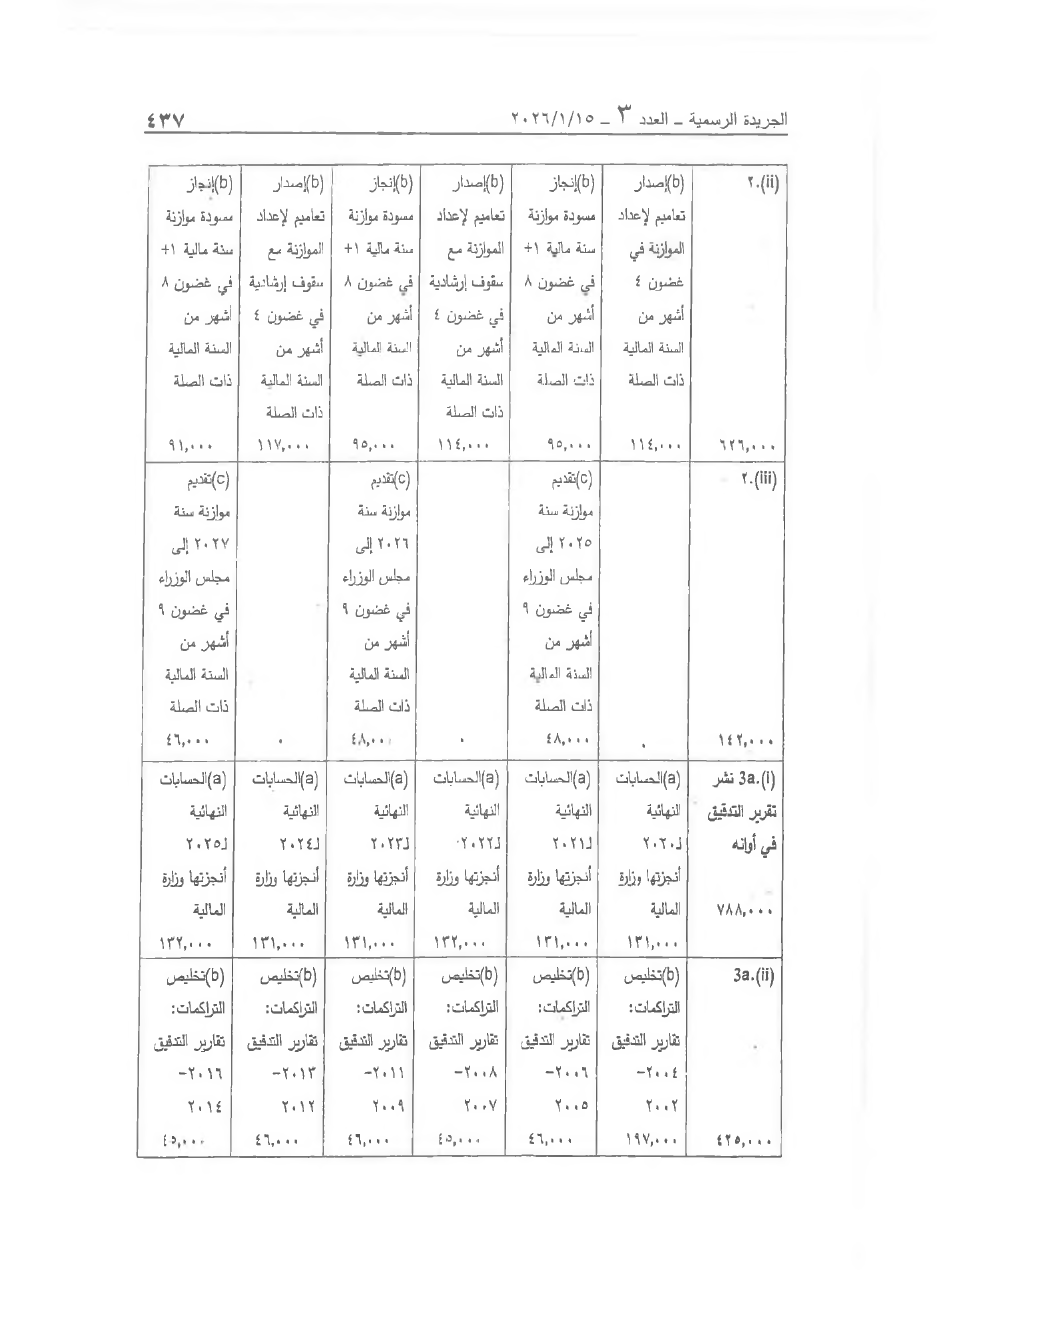
(أ) تحديث الإطار المالي المتوسط الأجل لمدة ٣ سنوات ۱۵۰,۰۰۰ | (ب) استكمال مشاورات موازنة السنة المالية + ۱ في غضون ۷ أشهر من السنة المالية ذات الصلة ۱۵۰,۰۰۰
(ج) إصدار التعميمات المتعلقة بطلب الموازنة مع سقوف إرشادية خلال ٤ أشهر من السنة المالية ذات الصلة ۱۵۰,۰۰۰ | (ج) الانتهاء من مسودة موازنة السنة المالية + ۱ في غضون ٨ أشهر من السنة المالية ذات الصلة ۱۵۰,۰۰۰
(هـ) تقديم موازنة ۲۰۲۹ إلى مجلس الوزراء في غضون ٨ أشهر من السنة المالية ذات الصلة ۲۰۰,۰۰۰ |
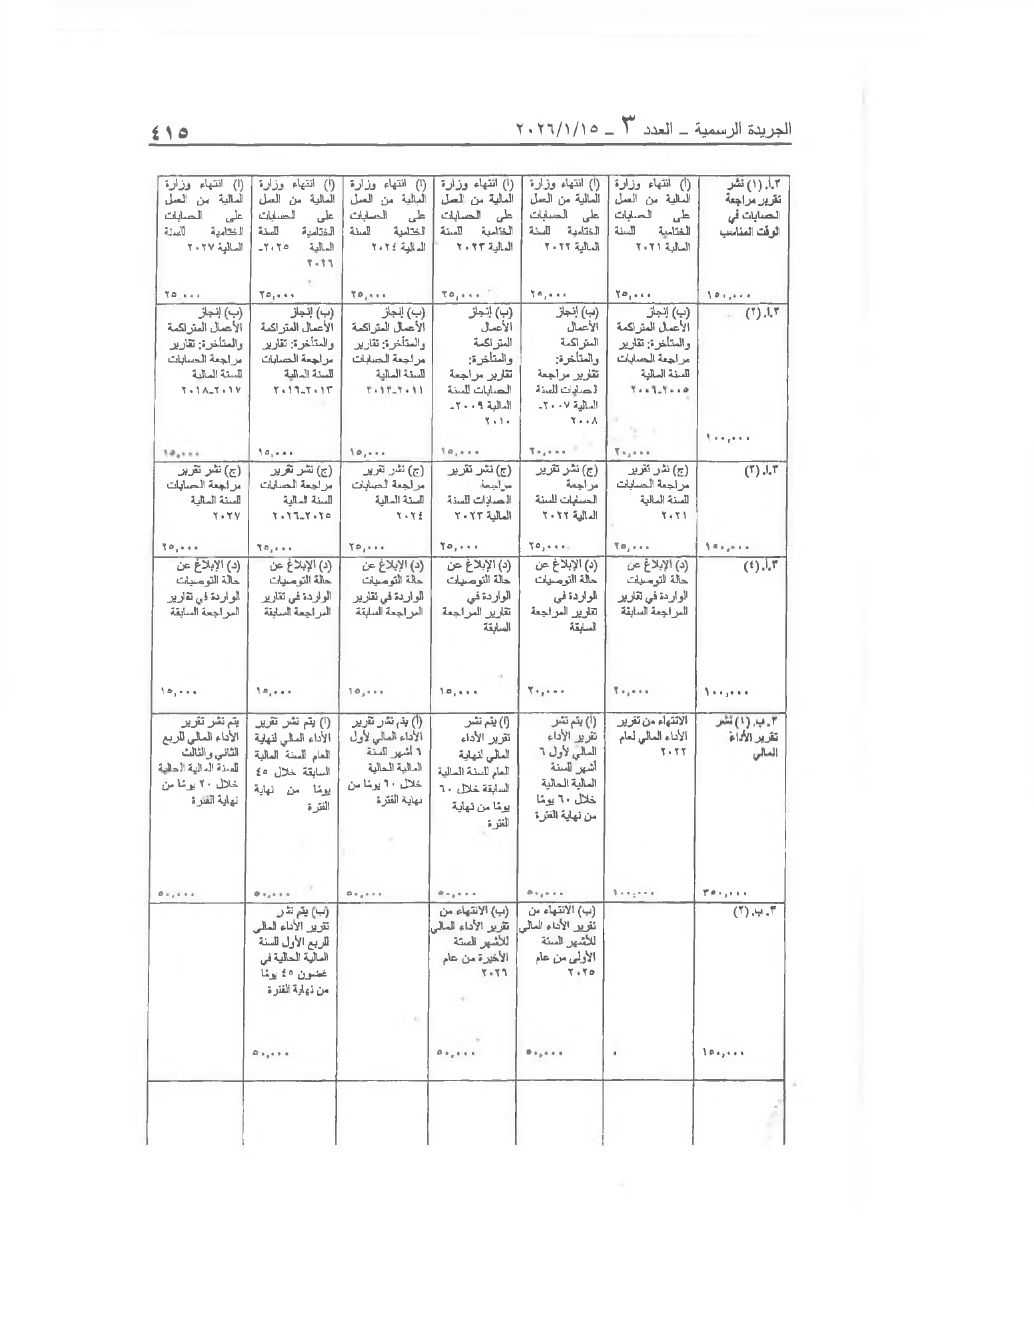
٣. أ. (١) نشر تقرير مراجعة الحسابات في الوقت المناسب … / ١٥٠,٠٠٠ | (أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة المالية ٢٠٢١ … / ٢٥,٠٠٠ | (أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة المالية ٢٠٢٢
١٥٠,٠٠٠ | / … ٢٥,٠٠٠ | ٢٥,٠٠٠ ٣.أ.(٢) / ٣. أ. (٢) ١٠٠,٠٠٠ | (ب) إنجاز الأعمال المتراكمة والمتأخرة: تقارير مراجعة الحسابات للسنة المالية ٢٠٠٥-٢٠٠٦ … / ٢٠,٠٠٠ | (ب) إنجاز الأعمال المتراكمة والمتأخرة: تقارير مراجعة الحسابات للسنة المالية ٢٠٠٧-٢٠٠٨
١٠٠,٠٠٠ | / … ٢٠,٠٠٠ | ٢٠,٠٠٠ ٣.أ.(٣) / ٣. أ. (٣) ١٥٠,٠٠٠ | (ج) نشر تقرير مراجعة الحسابات للسنة المالية ٢٠٢١ … / ٢٥,٠٠٠ | (ج) نشر تقرير مراجعة الحسابات للسنة المالية ٢٠٢٢
١٥٠,٠٠٠ | / … ٢٥,٠٠٠ | ٢٥,٠٠٠ ٣.أ.(٤) / ٣. أ. (٤) ١٠٠,٠٠٠ | (د) الإبلاغ عن حالة التوصيات الواردة في تقارير المراجعة السابقة … / ٢٠,٠٠٠ | (د) الإبلاغ عن حالة التوصيات الواردة في تقارير المراجعة السابقة
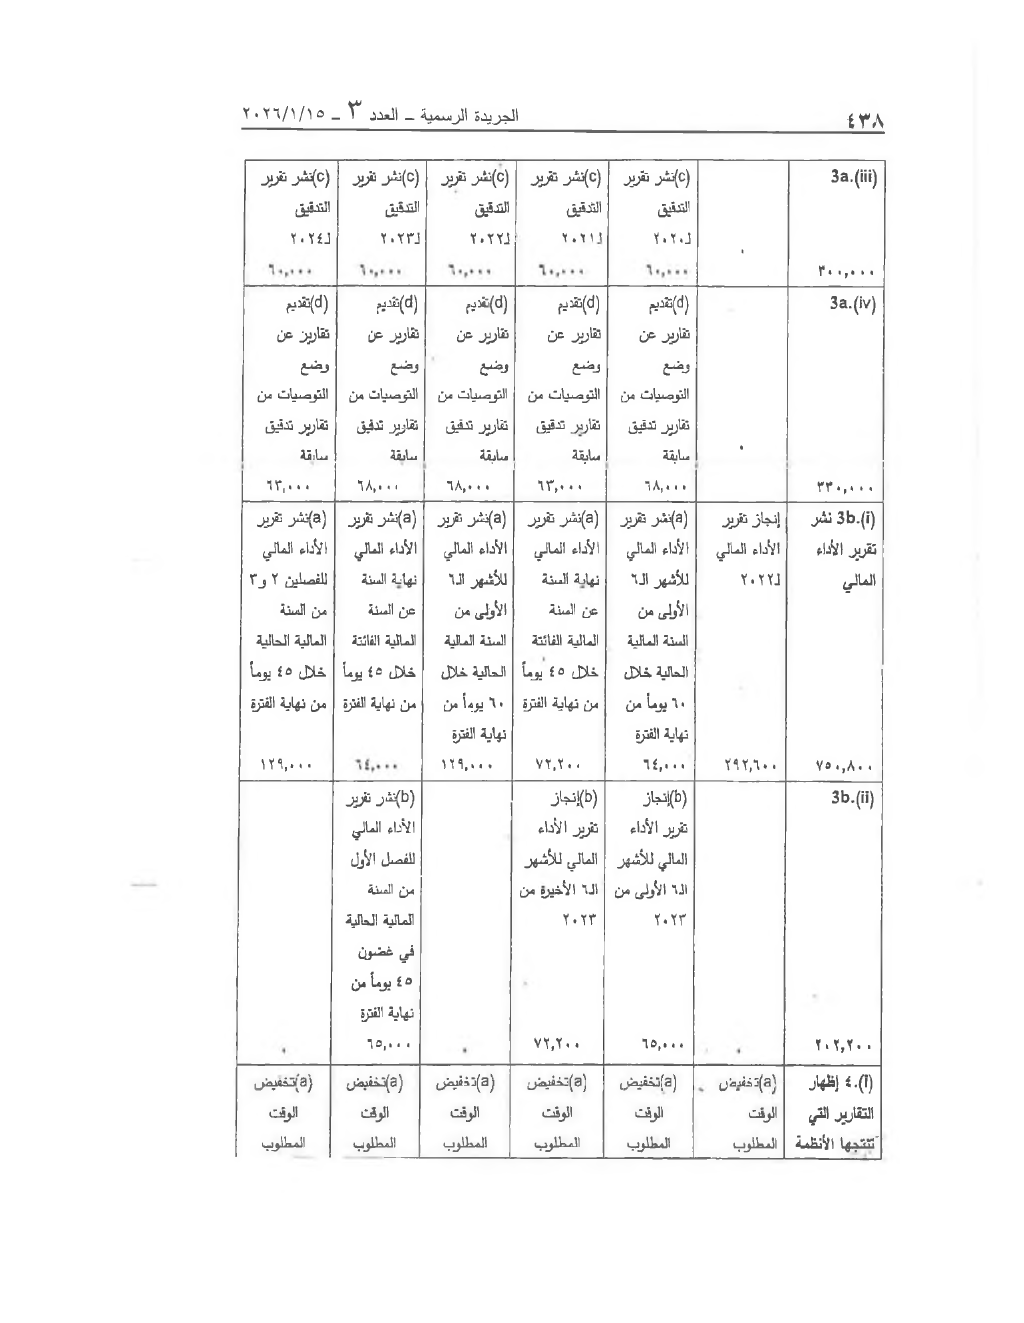
١٠٠,٠٠٠ | / … ٢٠,٠٠٠ ٣. ب. (١) نشر تقرير الأداء المالي … / ٣٥٠,٠٠٠ | الانتهاء من تقرير الأداء المالي لعام ٢٠٢٢ … / ١٠٠,٠٠٠ | (أ) يتم نشر تقرير الأداء المالي لأول ٦ أشهر للسنة المالية الحالية خلال ٦٠ يوما من نهاية الفترة
٣٥٠,٠٠٠ | ١٠٠,٠٠٠ | / … ٥٠,٠٠٠
٣.ب.(٢) / ٣. ب. (٢) ١٥٠,٠٠٠ | - | (ب) الانتهاء من تقرير الأداء المالي للأشهر الستة الأولى من عام ٢٠٢٥
١٥٠,٠٠٠ | | ٥٠,٠٠٠
(أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة المالية ٢٠٢٣ … / ٢٥,٠٠٠ | (أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة المالية ٢٠٢٤ … / ٢٥,٠٠٠ | (أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة المالية ٢٠٢٦ | (أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة -٢٠٢٥ | (أ) انتهاء وزارة المالية من العمل على الحسابات الختامية للسنة المالية ٢٠٢٧
٢٥,٠٠٠ | ٢٥,٠٠٠ | ٢٥,٠٠٠ | ٢٥,٠٠٠ | ٢٥,٠٠٠ / …
(ب) إنجاز الأعمال المتراكمة والمتأخرة: تقارير مراجعة الحسابات للسنة المالية ٢٠٠٩-٢٠١٠ … / ١٥,٠٠٠ | (ب) إنجاز الأعمال المتراكمة والمتأخرة: تقارير مراجعة الحسابات للسنة المالية ٢٠١١-٢٠١٣ / ٢٠١١-٢٠١٢ ١٥,٠٠٠ | (ب) إنجاز الأعمال المتراكمة والمتأخرة: تقارير مراجعة الحسابات للسنة المالية ٢٠١٣-٢٠١٦ … / ١٥,٠٠٠ | (ب) إنجاز الأعمال المتراكمة والمتأخرة: تقارير مراجعة الحسابات للسنة المالية ٢٠١٧-٢٠١٨
١٥,٠٠٠ | ١٥,٠٠٠ | ١٥,٠٠٠ | ١٥,٠٠٠ / …
(ج) نشر تقرير مراجعة الحسابات للسنة المالية ٢٠٢٣ … / ٢٥,٠٠٠ | (ج) نشر تقرير مراجعة الحسابات للسنة المالية ٢٠٢٤ … / ٢٥,٠٠٠ | (ج) نشر تقرير مراجعة الحسابات للسنة المالية ٢٠٢٥-٢٠٢٦ … / ٢٥,٠٠٠ | (ج) نشر تقرير مراجعة الحسابات للسنة المالية ٢٠٢٧
٢٥,٠٠٠ | ٢٥,٠٠٠ | ٢٥,٠٠٠ | ٢٥,٠٠٠ / …
(د) الإبلاغ عن حالة التوصيات الواردة في تقارير المراجعة السابقة … / ١٥,٠٠٠ | (د) الإبلاغ عن حالة التوصيات الواردة في تقارير المراجعة السابقة … / ١٥,٠٠٠ | (د) الإبلاغ عن حالة التوصيات الواردة في تقارير المراجعة السابقة … / ١٥,٠٠٠ | (د) الإبلاغ عن حالة التوصيات الواردة في تقارير المراجعة السابقة
١٥,٠٠٠ | ١٥,٠٠٠ | ١٥,٠٠٠ | ١٥,٠٠٠ / …
(أ) يتم نشر تقرير الأداء المالي لنهاية العام للسنة المالية السابقة خلال ٦٠ يوماً من نهاية الفترة … / ٥٠,٠٠٠ | (أ) يتم نشر تقرير الأداء المالي لأول ٦ أشهر للسنة المالية الحالية خلال ٦٠ يوماً من نهاية الفترة … / ٥٠,٠٠٠ | (أ) يتم نشر تقرير الأداء المالي لنهاية العام للسنة المالية السابقة خلال ٤٥ يوماً من نهاية الفترة … / ٥٠,٠٠٠ | يتم نشر تقرير الأداء المالي للربع الثاني والثالث للسنة المالية الحالية خلال ٢٠ يوما من نهاية الفترة
٥٠,٠٠٠ | ٥٠,٠٠٠ | ٥٠,٠٠٠ | ٥٠,٠٠٠ / …
(ب) الانتهاء من تقرير الأداء المالي للأشهر الستة الأخيرة من عام ٢٠٢٦ … / ٥٠,٠٠٠ | | (ب) يتم نشر تقرير الأداء المالي للربع الأول للسنة المالية الحالية في غضون ٤٥ يوما من نهاية الفترة |
٥٠,٠٠٠ | | ٥٠,٠٠٠ |
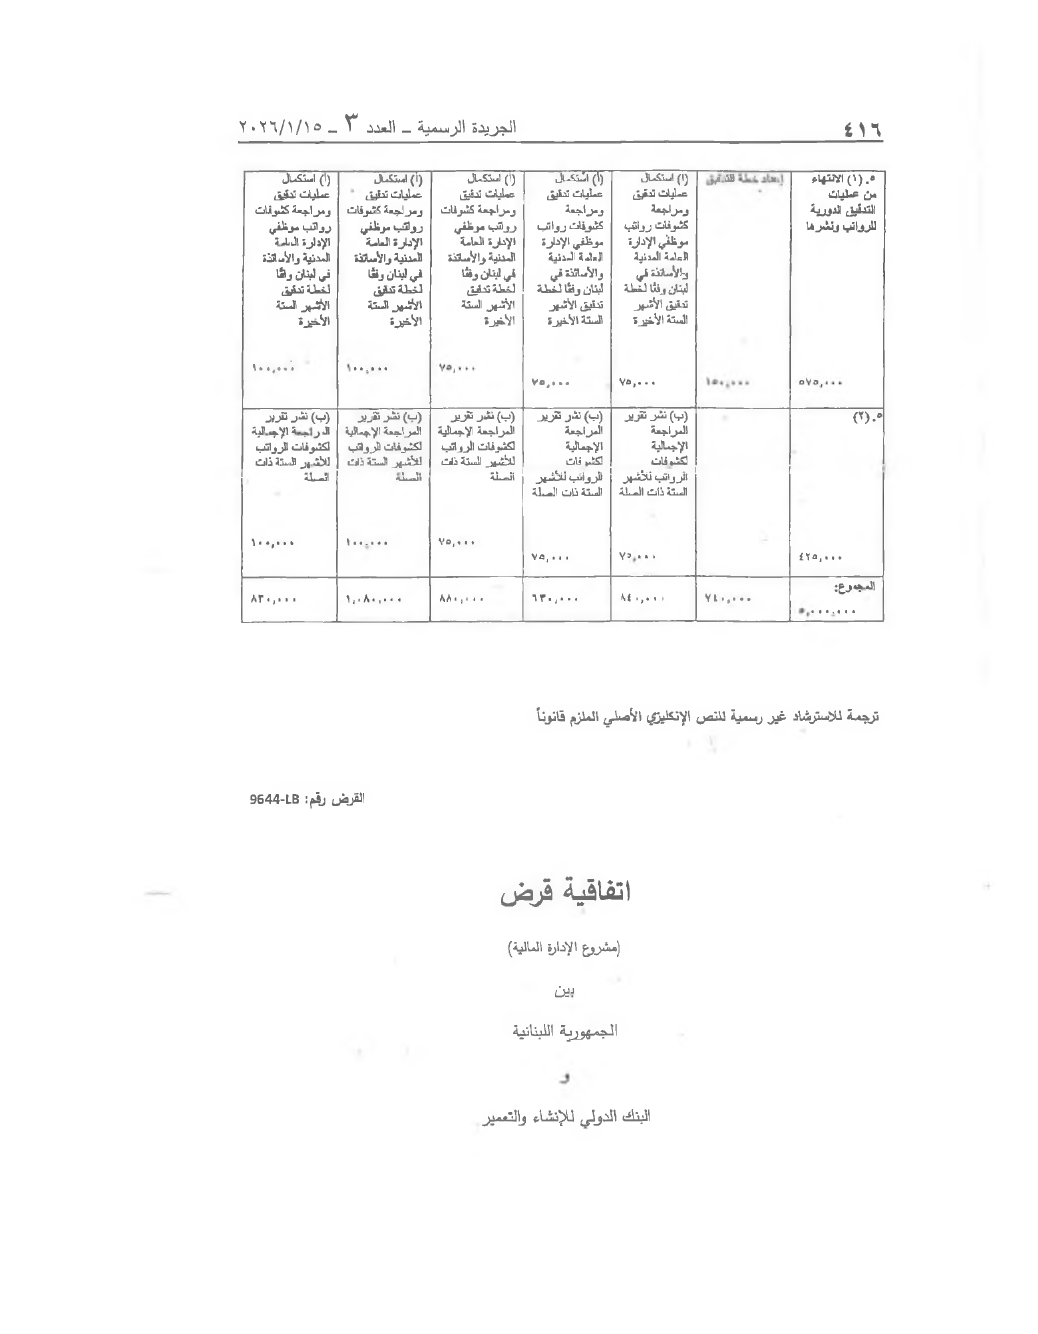
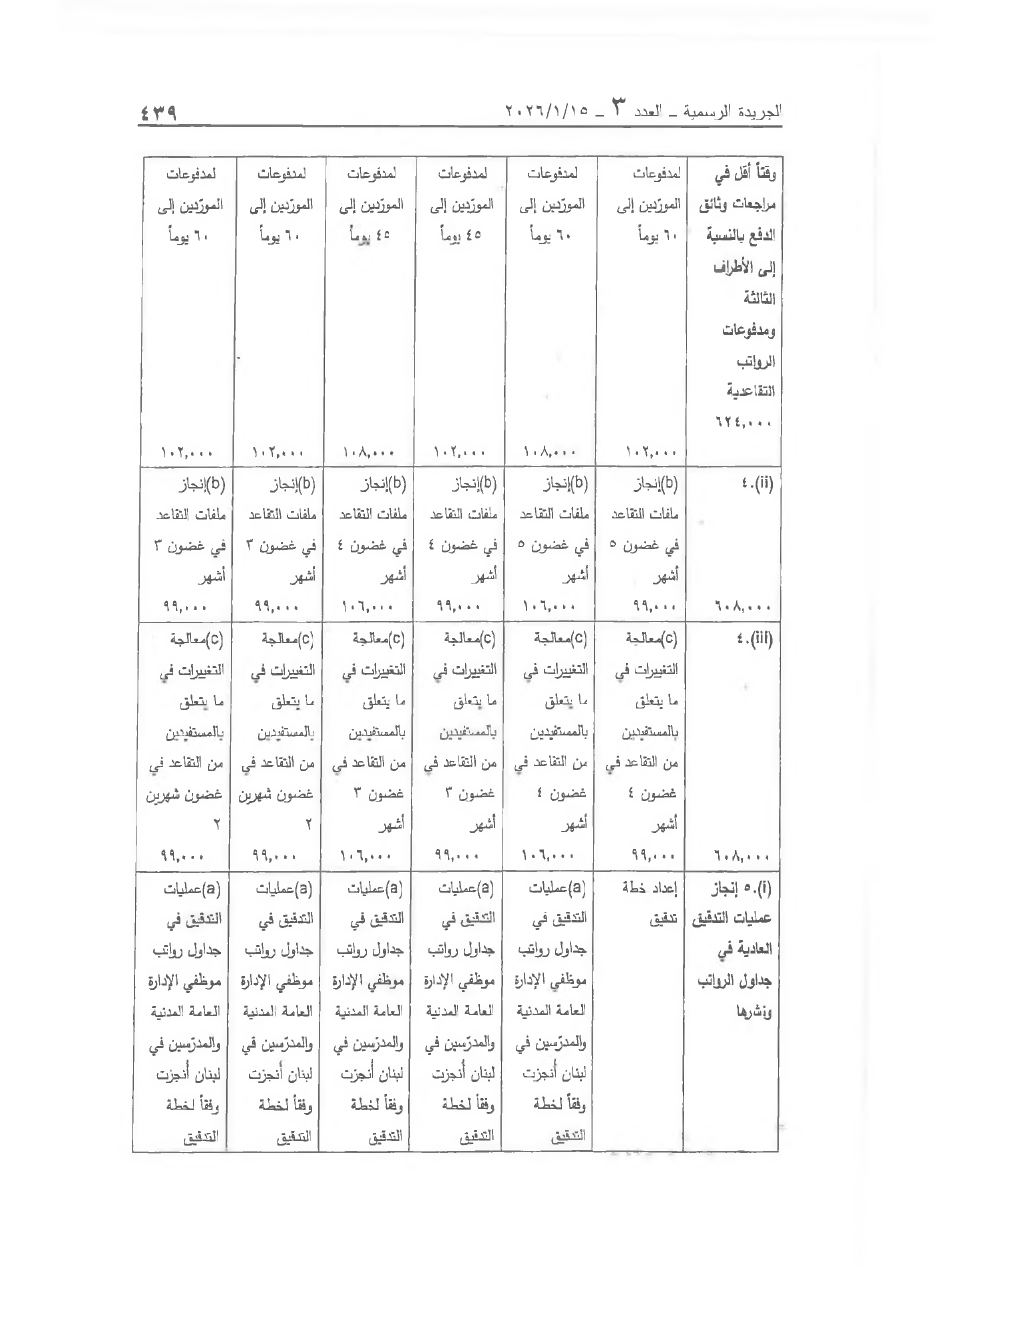
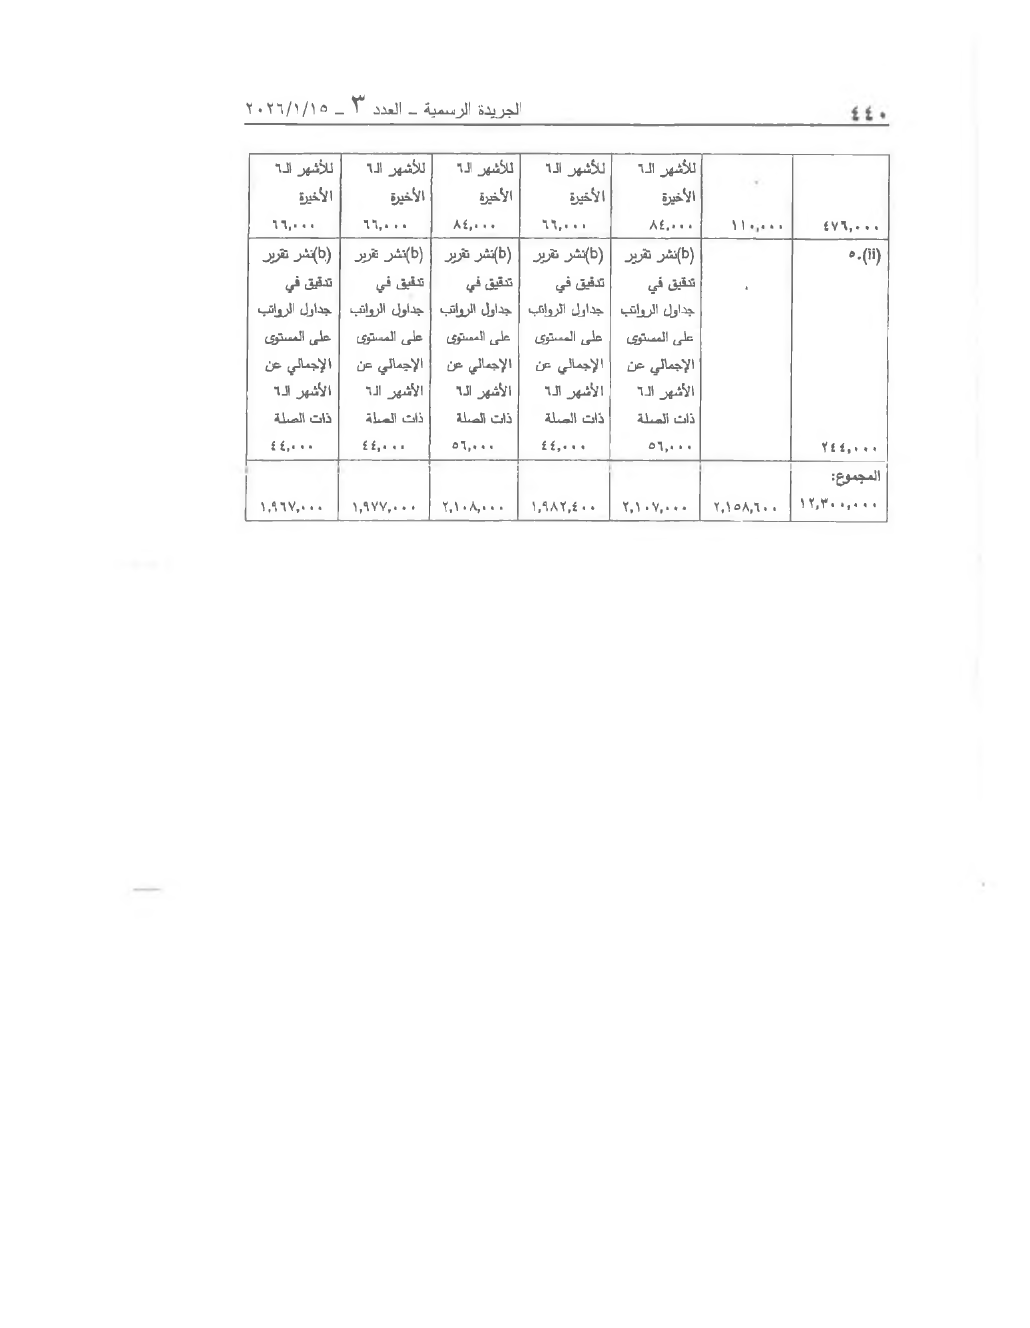
٥. (١) الانتهاء من عمليات التدقيق الدورية للرواتب ونشرها ٥٧٥,٠٠٠ | إعداد خطة التدقيق ١٥٠,٠٠٠ | (أ) استكمال عمليات تدقيق ومراجعة كشوفات رواتب موظفي الإدارة العامة المدنية والأساتذة في لبنان وفقًا لخطة تدقيق الأشهر الستة الأخيرة ٧٥,٠٠٠ | (أ) استكمال عمليات تدقيق ومراجعة كشوفات رواتب موظفي الإدارة العامة المدنية والأساتذة في لبنان وفقًا لخطة تدقيق الأشهر الستة الأخيرة ٧٥,٠٠٠ | (أ) استكمال عمليات تدقيق ومراجعة كشوفات رواتب موظفي الإدارة العامة المدنية والأساتذة في لبنان وفقًا لخطة تدقيق الأشهر الستة الأخيرة ٧٥,٠٠٠
(٢) .ه / ٥.(٢) ٤٢٥,٠٠٠ | | (ب) نشر تقرير المراجعة الإجمالية لكشوفات الرواتب للأشهر الستة ذات الصلة ٧٥,٠٠٠ | (ب) نشر تقرير المراجعة الإجمالية لكشوفات الرواتب للأشهر الستة ذات الصلة ٧٥,٠٠٠ | (ب) نشر تقرير المراجعة الإجمالية لكشوفات الرواتب للأشهر الستة ذات الصلة ٧٥,٠٠٠
المجموع: ٥,٠٠٠,٠٠٠ | ٧٤٠,٠٠٠ | ٨٤٠,٠٠٠ | ٦٣٠,٠٠٠ | ٨٨٠,٠٠٠
ترجمة للاسترشاد غير رسمية للنص الإنكليزي الأصلي الملزم قانوناً
اتفاقية قرض
(مشروع الإدارة المالية)
بين
الجمهورية اللبنانية
و
البنك الدولي للإنشاء والتعمير
(أ) استكمال عمليات تدقيق ومراجعة كشوفات رواتب موظفي الإدارة العامة المدنية والأساتذة في لبنان وفقًا لخطة تدقيق الأشهر الستة الأخيرة ١٠٠,٠٠٠ | (أ) استكمال عمليات تدقيق ومراجعة كشوفات رواتب موظفي الإدارة العامة المدنية والأساتذة في لبنان وفقًا لخطة تدقيق الأشهر الستة الأخيرة ١٠٠,٠٠٠
(ب) نشر تقرير المراجعة الإجمالية لكشوفات الرواتب للأشهر الستة ذات الصلة ١٠٠,٠٠٠ | (ب) نشر تقرير المراجعة الإجمالية لكشوفات الرواتب للأشهر الستة ذات الصلة ١٠٠,٠٠٠
١,٠٨٠,٠٠٠ | ٨٣٠,٠٠٠
القرض رقم: 9644-LB
| duration of the project. 3. Regularly through the duration of the project. 5. At the start of enrolling the staff in the performance allowance scheme, and updates every 6 months. | verification process
| 1. Quarterly basis. | 1. Project Supervision Report
| Within 3 months after the effective date 2. Starting from the 6th month after the effectiveness date | Project Supervision Report and Audit Reports
oration | 1. Within 4- 6 weeks | 1. Project Supervision Report
| | 3. Reconciliation of the flow of funds, and the disbursements with the project expenditures. 4. Details of staff entitled to receiving the allowances will be shared with the Bank, including their job descriptions and the rationale for their selection. Their details regarding attendance and other matters will be shared with the IVA in accordance with the verification protocols. | 3. PCU 4. PCU
3. | World Bank and MoF protocols on reporting on project activities (IFRs, Aide Memoires, ISMs, procurement reviews, ex-post audits, and so on) experience delays. | 1. Governance and operational reporting template to be developed that is filled by the PCU and discussed monthly with the World Bank Task Team and the MoF. | 1.PCU, MoF
4. | No internal audit function within the MoF | 1.The project will provide capacity and support to the Central Inspection (CI) to strengthen its resources and capacity to carry out internal control reviews and risk-based internal audits. 2. Internal reviews of project activities to be carried out periodically (6 months) and reports to be shared with the World Bank. | 1.MoF and CI 2.CI and PCU
5. | Weak | 1. Fiduciary Specialists | PCU in collab / collabo
A, | after the effectiveness date and throughout the project | 2. … / Spot checks by World Bank Task Team 2. Within 4 weeks after the effectiveness date 3. Starting from 4-6 weeks after the effectiveness date 4. Throughout the project duration 5. Throughout the project duration | 6. … / Post-procurement review reports 6. Throughout the project duration | 2. Spot checks by World Bank Task Team 5. Post-procurement review reports / …
on | 1. Within 3 months after the effective date 2. Within two months after the effective date 3. Throughout the project duration / … | 1. Project Supervision by the World Bank Task Team 2. Project Progress Reports … / 2. Within two months after the effective date | 3. Project Supervision by Task Team
… / 3. Throughout the project duration nance Issues
| Accountability for implementation of project activities | hired within the PCU to guide and review compliance with hands-on support, as needed, provided by the World Bank fiduciary team. … / | with the MoF, Co CI, IoF and CTB 2. Grievance redressal system to be designed and put in place. 3. Grievance redressal procedures to be publicized among citizens and stakeholders. 4. Regular monitoring of complaints received and resolved. 5. Semi-annual review of complaints received and responses to identify corruption vulnerabilities and determine mitigation efforts. … / | World Bank 6. Post-procurement reviews to be conducted at least once a year. | with the MoF, Co CI, IoF and CTB World Bank / …
6. | Weak accountability to citizens and stakeholders | 1. Project Stakeholder Engagement Plan to be formulated. … / | PCU in collaborati with the MoF for steps 1 to 3. 2. A project oversight body that includes public representatives and representatives of civil society organizations (CSOs). 3. Citizen feedback on project activities to be obtained periodically. | PCU in collaborati with the MoF for steps 1 to 3. / …
Fiduciary-related Govern
oration d Bank. | Within three months after the effectiveness date. | Project financial management supervision Spot checks by World Bank Task Team
cial WB (ex- ment e / he MoF. | Throughout the project duration Throughout the project duration 3. Within 3 months of project effectiveness. | Project Supervision Reports Audit reports
| Throughout the project duration | 1. Project Supervision Report 2. Project Progress Reports
1. | Delays and bottlenecks In / in disbursements of funds resulting in delays in implementation. | Disbursement time-lags to be monitored and continuous dialogue with the Treasury, CoA and BdL will be made to reduce lag times. | PCU in collabo with the Worl
2. | Emergency situations used as a basis for substantial variations in workplans and procurement plans, thereby leading to cost overruns, and ineligible expenditures. | 1.Any changes to the workplan must be approved/No Objection from the World Bank, and must be accompanied by a clear indication of any changes to procurement plans as well. 2.Financial audits and ex-post / ex- post procurement assessments to confirm deviations from work plans and procurement procedures. 3. Project to adopt stronger internal control procedures for emergencies, which will be reflected in a project operations manual. | 1.PCU 2. PCU (Finan audits) and W post procure / procurer reviews) 3. PCU with th
3. | Opportunities for fraud and corruption, for example, bid rigging and inflation of prices of goods and services, amplified by the use of emergency procurement procedures. | The project will apply the World Bank Procurement Regulations and will use the World Bank standard procurement documents. 2.The project will be carried out in accordance with the provisions of the 'Guidelines / ‘Guidelines on Preventing and Combating Fraud and Corruption in Projects Financed by IBRD Loans and IDA Credits and Grants' / Grants’ (Anti-Corruption Guidelines. 3.Procurement plans and notices will be published | PCU, MoF PCU PCU
| At effectiveness date
| rld | At effectiveness date | 1. Legal agreement
| Submit project audit reports within 6 months at the end of each year.
|
| | through the STEP system and MoF website. 2. Regular and periodic spot checks of procurement transactions to assess integrity and efficiency of procurement process and outcomes. | PCU, World Bank
4. | Projects activities implemented by multiple agencies, thus rendering financial management coordination and implementation more challenging. | A PCU will be hosted at the MoF. A ring-fenced system with strict and specific controls will be reflected in the financial management chapter of an operational manual. | PCU, MoF, CI, IoF, CoA, and CTB.
5. | Project will include financing of recurrent costs through the payment of allowances to a select number of staff at the MoF. This will involve a substantial number of transactions, thus increasing the risk of divergence and misuse of project funds. | Payments made under the project will be in US Dollars to preserve the value of the funds. In addition, the direct payment method will be available to use as needed. This will be agreed as with other World Bank-financed projects conducted with the BdL. The IVA's scope will be expanded to verify the payments to eligible staff. | MoF, BDL, and Wor Bank
6. | The country's public oversight body, the Court of Accounts (CoA), audits all public funds; however, it does not have the capacities/ resources to | The project will be audited by an independent external auditor with terms of reference acceptable to the Bank. | PCU, World Bank
| audit the project, which would give limited assurance regarding the use of the funds.
| |
Report No: RES00893
nni
THE WORLD BANK
IBRD • IDA | WORLD BANK GROUP
RESTRUCTURING PAPER
ON A
PROPOSED PROJECT RESTRUCTURING
OF
Fiscal Management Project
APPROVED ON 14-Feb-2024
TO
The Lebanese Republic
Governance
- Middle East And North Africa
Regional Vice President: | Ousmane Dione
Regional Director: | Nadir Mohammed
Country Director: | Jean-Christophe Carret
Practice Manager: | Clelia Kalliopi Helena Rontoyan
Task Team Leader(s): | Rima Abdul-Amir Koteiche
ABBREVIATIONS AND ACRONYMS
ASYCUDA | Automated System for Customs Data
DRM | Domestic Revenue Mobilization
FMP | Lebanon Fiscal Management Project
FM | Financial Management
GoL | Government of Lebanon
IBRD | International Bank for Reconstruction and Developm
IFMIS | Integrated Financial Management System
IP | Implementation Progress
ISR | Implementation Status and Results Report
ITAS | Integrated Tax Administration System
LFF | Lebanon Financing Facility
LTO | Large Taxpayer Office
M&E | Monitoring and Evaluation
MoF | Ministry of Finance
MS | Moderately Satisfactory
PBCs | Performance-Based Conditions
PDO | Project Development Objectives
PFM | Public Financial Management
RKC | Revised Kyoto Convention
SAFE | Safe Framework of Standards
TFA | Trade Facilitation Agreement
VAT | Value Added Tax
WCO | World Customs Organization
Operation Name
Fiscal Management Project
Geographical Identifier
Lebanon
Current Closing Date
31-Mar-2027
Responsible Agency
Minister of Finance
banese Republic restore the basic functions for domestic revenue
public resources.
Disbursed | Undisbursed | % Disbursed
BASIC DATA
Product Information
Operation ID
P181155
Product/Financing Instrument
Investment Project Financing (IPF)
Approval Date
14-Feb-2024
Environmental and Social Risk Classification (ESRC)
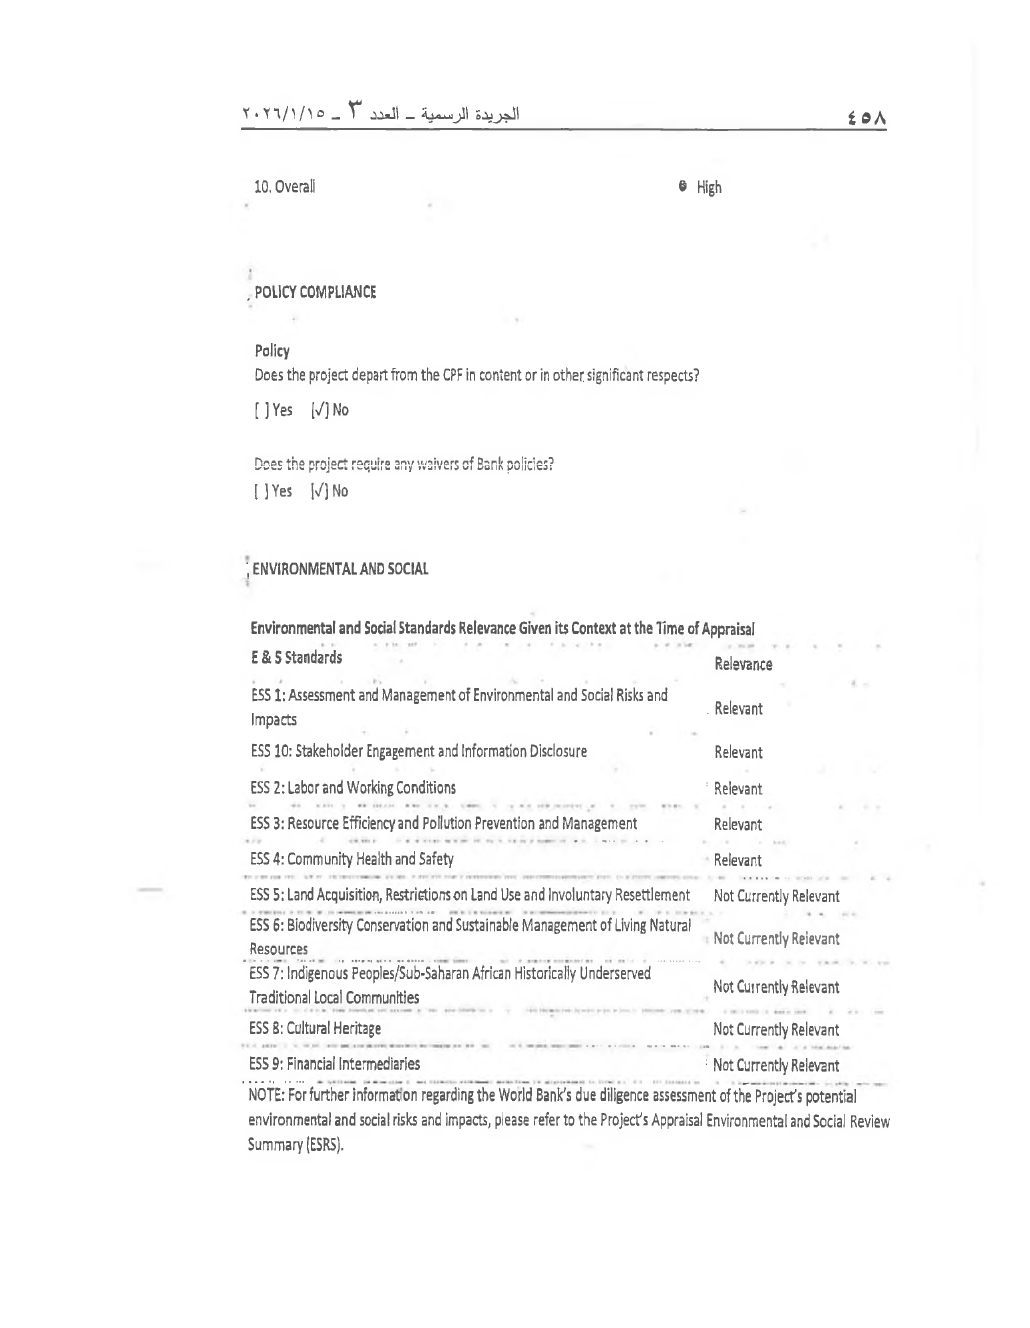
Moderate
Organizations
Borrower
The Lebanese Republic
OPERATION STATUS
Project Development Objective (DO)
Original Development Objective
Project development objective is to support the Let / Leb
mobilization and accountable allocation and use of
Disbursement Summary (in USD million)
Source of Funds | Net Commitment
28.50 | 0.00
- | 0
4.85 | 11.80
No
… / ٢٠٢٦/١/١٥ | ٥١٣ IBRD | 28.50 | 0.00
IDA | - | -
Grants | 5.50 | 0.65
Policy Waivers
Does this restructuring trigger the need for any policy waiver(s)?
TABLE OF CONTENTS
I. PROJECT STATUS AND RATIONALE FOR RESTRUCTURING
II. DESCRIPTION OF PROPOSED CHANGES
III. PROPOSED CHANGES
IV. DETAILED CHANGE(S)
I. PROJECT STATUS AND RATIONALE FOR RESTRUCTURING
Project Status
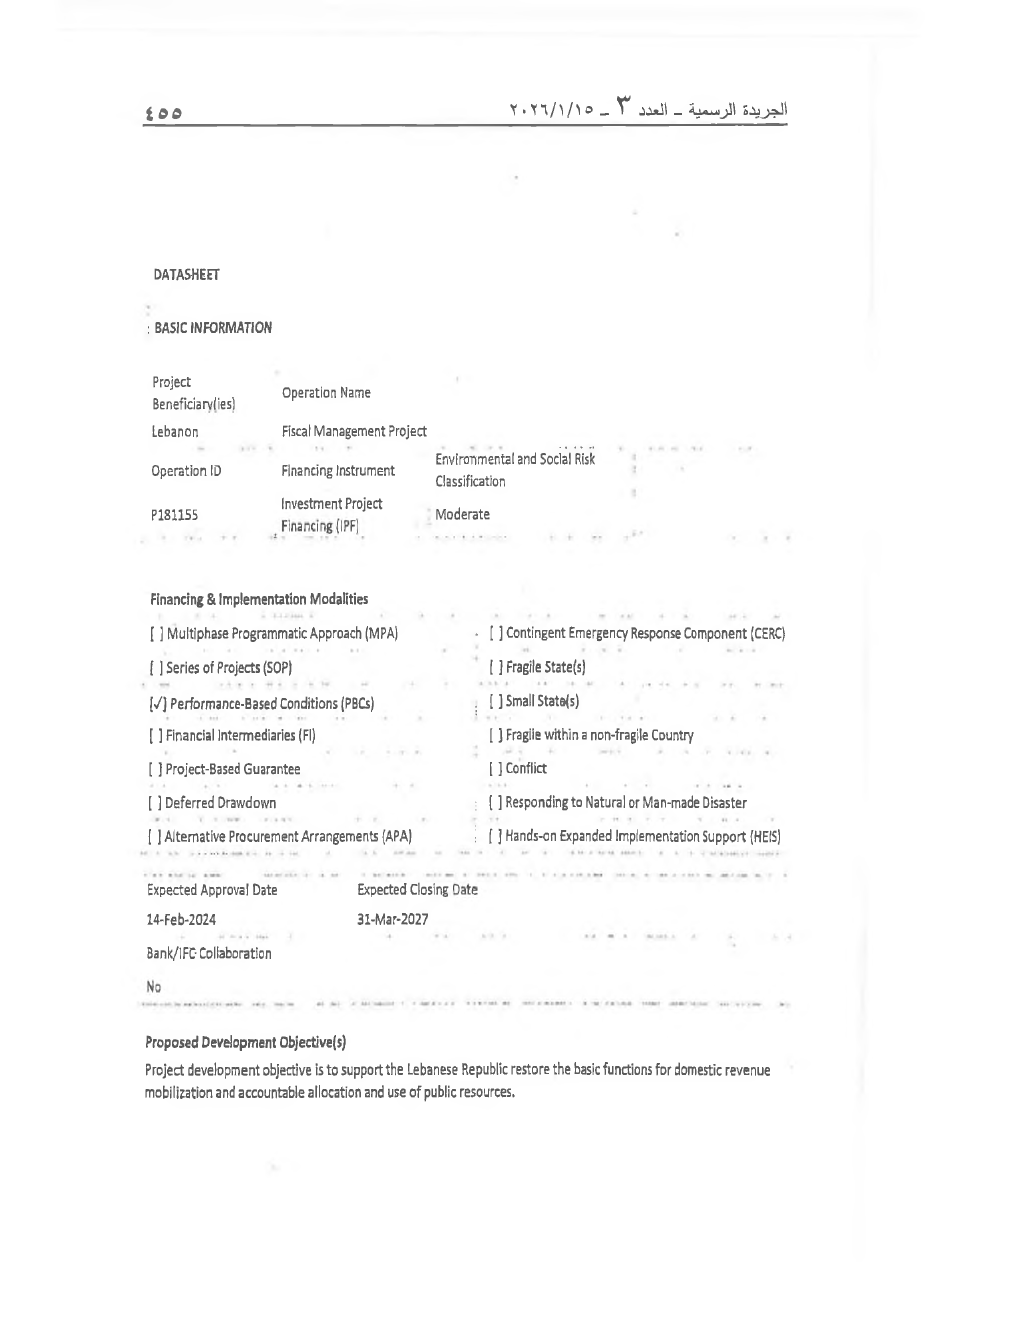
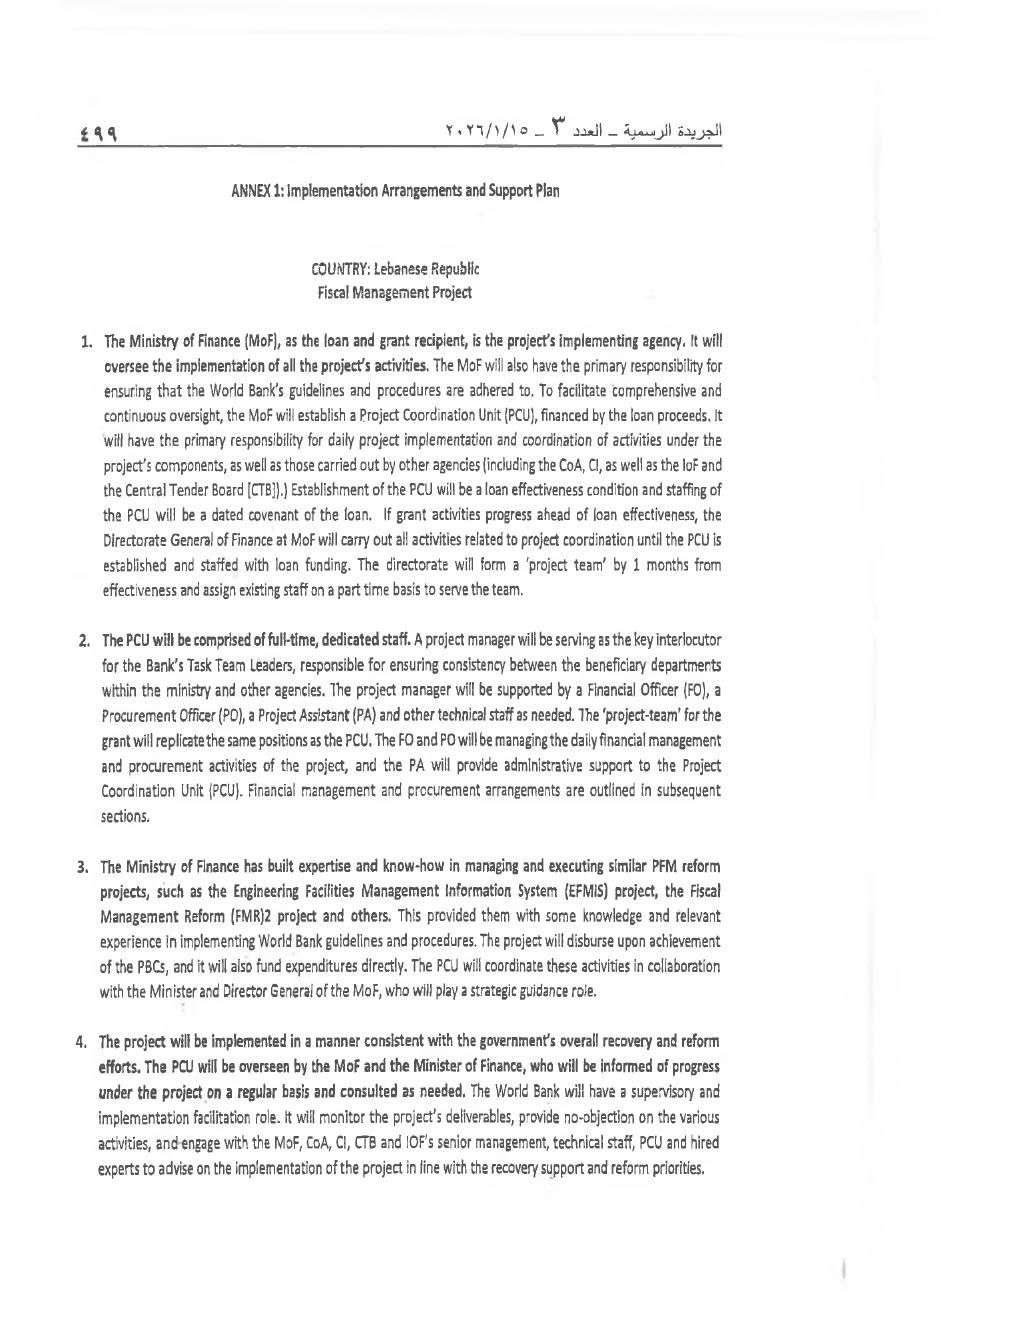
1. The US$28.50 million loan and the US$5.5 million grant from the Lebanon Financing Facility (LFF) for the lebanon / Lebanon Fiscal Management Project (FMP) were approved by the World Bank Board of Executive Directors on February 14, 2024, with a closing date of March 31, 2027. The Project Development Objectives (PDO) is to support the Lebanese Republic restore the basic functions of domestic revenue mobilization and accountable allocation and use of public resources. The project comprises five components: (1) Stabilizing Domestic Revenue Administration; (2) Restoring Fiscal Controls, (3) Revitalizing Oversight and Accountability Institutions and Procurement Capacity Building, (4) Project Management, (5) Contingent Emergency Response Component - CERC. The project design includes an allocation of US$12.3 million to be disbursed based on the achievement of five Performance-Based Conditions (PBCs).
2. Project Performance. The grant agreement for the LFF grant was signed on July 22, 2024, and was declared effective on October 15, 2024, while the loan agreement for the IBRD loan was signed on September 27, 2024, and the deadline for declaring the loan effective was extended to August 11, 2025, at the Government's / Government’s request. Due to the delay in declaring the loan as effective, the Project Development Objective (PDO) and Implementation Progress (IP) are rated Moderately Satisfactory (MS). Financial Management (FM), Procurement, and Monitoring and Evaluation (M&E) are rated Moderately Satisfactory (MS). There are no audit reports due yet; the first audit report will cover fiscal year 2025 and will be due by June 30, 2026. The status of implementation of the Project components is summarized below.
3. Component 1: Stabilizing Domestic Revenue Administration (US$14.1 million, of which loan US$10.6 million and grant US$3.5 million). This component aims at providing essential support to critical revenue functions, which is a pre-condition to increasing the collection of tax and non-tax revenues. This component will receive funding upon the achievement of PBC # / PBC# 1a and PBC #1b. The component will fund technical assistance, training, operating costs and essential revenue IT system maintenance and upgrades. Additionally, funding will be provided to install solar panels (at a cost of approximately US$1 million) for electricity generation in the buildings of these agencies as required. The procurement for the acquisition of ICT hardware and software was launched for US$3.5 million, out of which US$1.5 million are committed and under implementation (fully financed from the LFF grant).
4. Component 2: Restoring Fiscal Controls (US$ 15 million: loan US$13 million; grant US$ 2 million). The objective of the component is to reestablish the critical pillars for allocating and utilizing resources to meet urgent needs, as well as to set the foundation for recovery. The activities under this component will be funded upon the completion of the targets under PBC #2, PBC #3a, PBC #3b and PBC #4. In addition, the component provides technical assistance, training, and ICT equipment in budget preparation areas, including procurement planning, and fiscal and financial reporting. Furthermore, funding will be provided to install solar panels for electricty / electricity
generation (at a cost of approximately US$1 million) in the buildings of these departments and agencies as required. The PBC#4 "system-generated reports show reduced time for reviews of Payment documents for third parties and pension payments" was achieved. Hence, it is decided to drop that PBC#4 in the restructuring. Additionally, the procurement for ICT hardware and software for MoF of US$2 million were launched, contracts were signed and are under implementation (fully financed by the LFF grant).
5. Component 3: Revitalizing Oversight and Accountability Institutions and Procurement Capacity Building (USD$2.4 million: loan US$2.4 million; grant US$0). This component aims to help enhance: (a) the role of oversight, audit and capacity of the Court of Accounts (CoA), Central Inspection (CI), the Public Procurement Authority and other selected public procurement entities and expand their engagement with the citizens; and (b) the role of capacity building of the Institute of Finance (IoF). The proposed activities under this subcomponent will be funded upon the completion of the targets under PBC #3a and PBC #5. Additionally, technical assistance, training, and IT enhancements will be funded. Finally, funding will be provided to install solar panels in the buildings of these agencies, as required for electricity generation (at a cost of approximately US$0.8 million). There is no progress to-date awaiting the ratification of the related project loan.
6. Component 4: Project Management (US$2.5 million: loan US$2.5 million; grant US$0) This component will support the management, coordination, communications and monitoring and evaluation (M&E) for Project activities. The component will fund the maintenance of a Project Coordination Unit (PCU) under the Ministry of Finance. The PCU will be staffed with a full-time Project coordinator, fiduciary specialists and a monitoring and evaluation specialist. In addition, a part-time Environmental and Social (E&S) Specialist will be assigned to manage the E&S requirements of the proposed Project. Also, communication expertise will be contracted or assigned as needed. Project management staff salaries (other than civil servants' salaries), selected allowances, training, and basic facilities for managing the proposed Project will be funded under this component. In addition, the component will fund the cost of an IVA to verify the PBCs. There are no activities that are launched yet as the loan has not been ratified yet.
7. Component 5: Contingent Emergency Response Component - CERC (US$ 0). This component will support the provision of an immediate response to an Eligible Crisis or Emergency, as needed. It will be considered in the case of the occurrence of an Eligible Crisis or Emergency as defined under the loan agreement. In the event that the CERC is activated, a CERC Operations Manual will be prepared during Project implementation to govern the operation of the component.
Rationale for Restructuring
8. The Government of Lebanon (GoL) has requested the World Bank to restructure the Lebanon FMP to reallocate funds from the incentive scheme for Ministry of Finance (MoF) staff, as the incentive scheme for staff is no longer a priority, to IT system upgrades and enhancements to support Public Financial Management (PFM) reforms to
القرض رقم: 9644-LB
اتفاقية القرض
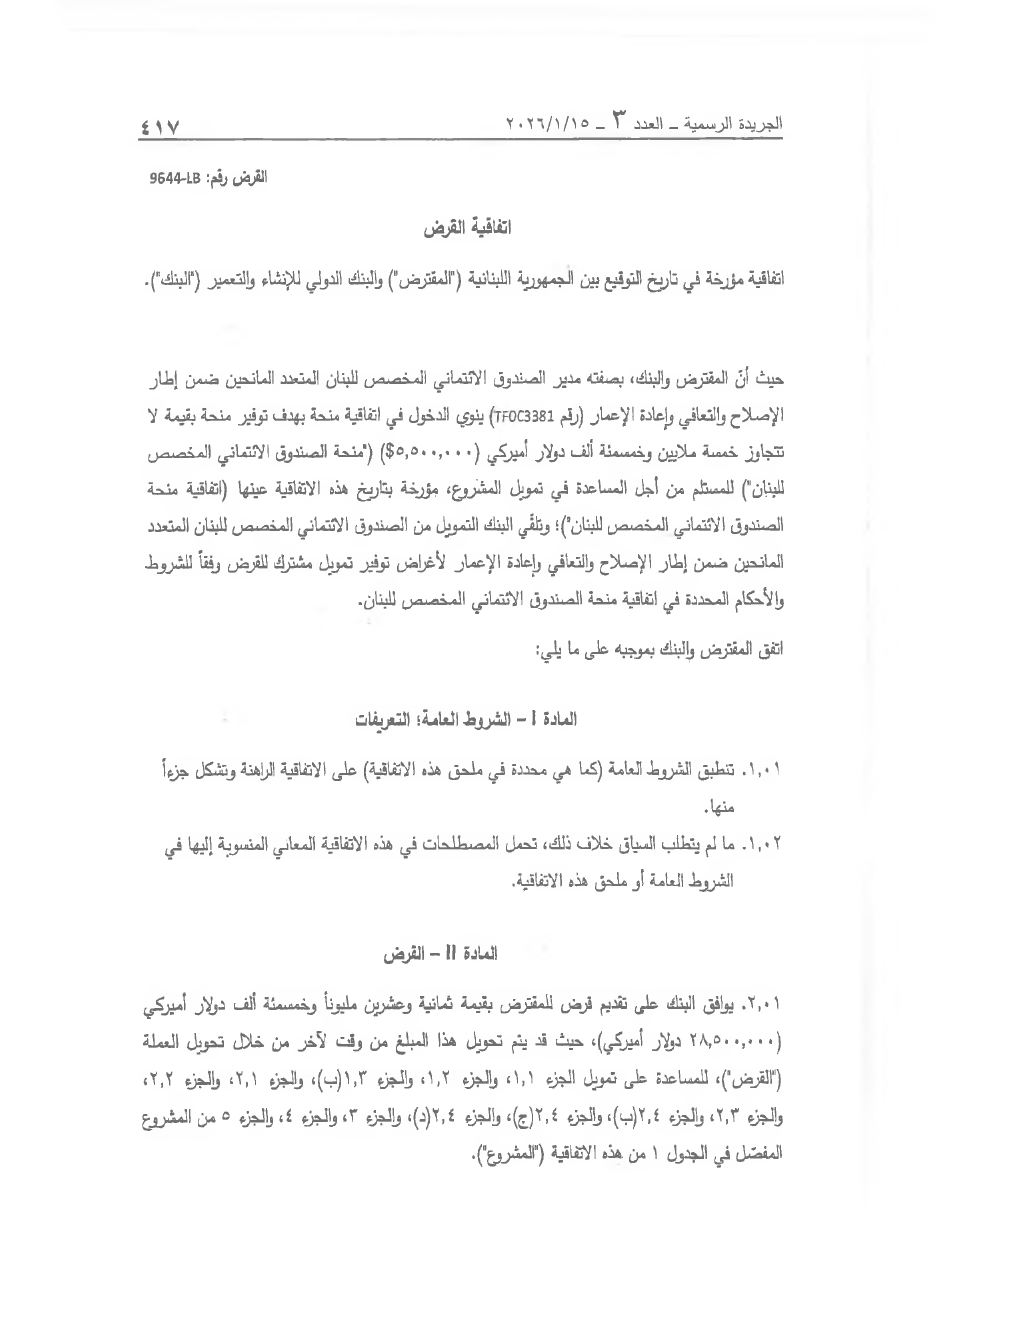
اتفاقية مؤرخة في تاريخ التوقيع بين الجمهورية اللبنانية ("المقترض") والبنك الدولي للإنشاء والتعمير ("البنك").
حيث أن المقترض والبنك، بصفته مدير الصندوق الائتماني المخصص للبنان المتعدد المانحين ضمن إطار الإصلاح والتعافي وإعادة الإعمار (رقم TF0C3381) ينوي الدخول في اتفاقية منحة بهدف توفير منحة بقيمة لا تتجاوز خمسة ملايين وخمسمئة ألف دولار أميركي ($٥,٥٠٠,٠٠٠) / (٥,٥٠٠,٠٠٠$) ("منحة الصندوق الائتماني المخصص للبنان") للمستلم من أجل المساعدة في تمويل المشروع، مؤرخة بتاريخ هذه الاتفاقية عينها (اتفاقية منحة الصندوق الائتماني المخصص للبنان)؛ وتلقي البنك التمويل من الصندوق الائتماني المخصص للبنان المتعدد المانحين ضمن إطار الإصلاح والتعافي وإعادة الإعمار لأغراض توفير تمويل مشترك للقرض وفقاً للشروط والأحكام المحددة في اتفاقية منحة الصندوق الائتماني المخصص للبنان.
اتفق المقترض والبنك بموجبه على ما يلي:
المادة I - الشروط العامة؛ التعريفات
١,٠١. تنطبق الشروط العامة (كما هي محددة في ملحق هذه الاتفاقية) على الاتفاقية الراهنة وتشكل جزءاً منها.
١,٠٢. ما لم يتطلب السياق خلاف ذلك، تحمل المصطلحات في هذه الاتفاقية المعاني المنسوبة إليها في الشروط العامة أو ملحق هذه الاتفاقية.
المادة II - القرض
٢,٠١. يوافق البنك على تقديم قرض للمقترض بقيمة ثمانية وعشرين مليوناً وخمسمئة ألف دولار أميركي (٢٨,٥٠٠,٠٠٠ دولار أميركي)، حيث قد يتم تحويل هذا المبلغ من وقت لآخر من خلال تحويل العملة ("القرض")، للمساعدة على تمويل الجزء ١,١، والجزء ١,٢، والجزء ١,٣(ب)، والجزء ٢,١، والجزء ٢,٢، والجزء ٢,٣، والجزء ٢,٤(ب)، والجزء ٢,٤(ج)، والجزء ٢,٤(د)، والجزء ٣، والجزء ٤، والجزء ٥ من المشروع المفصل في الجدول ١ من هذه الاتفاقية ("المشروع").
support Lebanon in achieving its broader fiscal governance objectives and ensuring sustainable economic recovery.
9. The PDO will remain unchanged, and the restructuring aligns with the PDO to support Lebanon in restoring basic functions for domestic revenue mobilization and accountable allocation and use of public resources. It includes, inter alia, a revision in the allocation of funds from the payment of staff allowances (which are being dropped) to IT investments, ensuring efficient use of Project funds. The existing IT systems at the MoF are fragmented, outdated, and heavily reliant on manual data entry, posing high risks to business continuity; and their replacement by a Procurement of a new modern Integrated Financial Management System (IFMIS) system aims to support the collection and analysis of timely, relevant and reliable financial data in respect of GoL's / GoL’s revenues and spending. Procurement of a new Integrated Tax Administration System (ITAS) will make tax administration operations efficient, facilitate taxpayer compliance, and enable the collection and analysis of relevant taxpayer data for informed decision and policymaking. The restructuring also includes the development of a Learning Management System (e-modules on PFM and public procurement) to build the capacity and technical skills of civil servants, ensuring sustainable improvements in PFM and public procurement capacity. The current PBCs and the overall allocation need revision based on the changes being made to the Project under the restructuring. The Project closing date will be extended by twenty-one months, from March 31, 2027, until December 31, 2028, to accommodate the procurement and implementation of the enhancements to the IT systems.
10. The Government remains committed to achieving the PDO. A revised implementation plan was agreed to complete project activities by the proposed revised closing date, which is acceptable to the Bank.
II. DESCRIPTION OF PROPOSED CHANGES
11. Key changes include:
(a) Reallocation:
▪ Component Costs: A total of US$2.6 million is being reallocated from Component 3 to Component 2, as reflected in Table 1. This adjustment will support additional activities under Components 1, 2, and 3, while the total loan amount remains unchanged. As a result, the cost of Component 2 will increase from US$10.4 million to US$13 million, and Component 3 will decrease from US$5 million to US$2.4 million. The cost of Component 1 will remain unchanged; however, the initially allocated US$5.5 million for the staff incentive scheme under this component will now be redirected to finance the development and implementation of the Integrated Tax Administration System (ITAS).
TABLE 1: CHANGES IN COMPONENT COSTS
Components | Original Budget Allocation Loan financing (Million USD) | Budget Allocation Loan financing after the Restructuring (Million USD) | Budget Allocation from LFF grant (Unchanged) (Million USD) | Budget Allocation Loan and LFF grant after the restructuring (Million USD)
1: Stabilizing DRM | 10.6 | 10.6 | 3.5 | 14.1
2: Restoring fiscal control | 10.4 | 13 | 2 | 15
3: Re-vitalizing oversight and accountability institutions and procurement capacity building | 5 | 2.4 | 0 | 2.4
4: Project Management | 2.5 | 2.5 | 0 | 2.5
Total | 28.5 | 28.5 | 5.5 | 34
▪ Disbursement Categories: As a result of the restructuring and the elimination of the incentive scheme, the amount allocated to Category 1 will be reallocated to Category 2, as detailed in Table 2.
TABLE 2 CHANGE IN CATEGORIES
Category | Original Allocation US$ | Revised Allocation US$
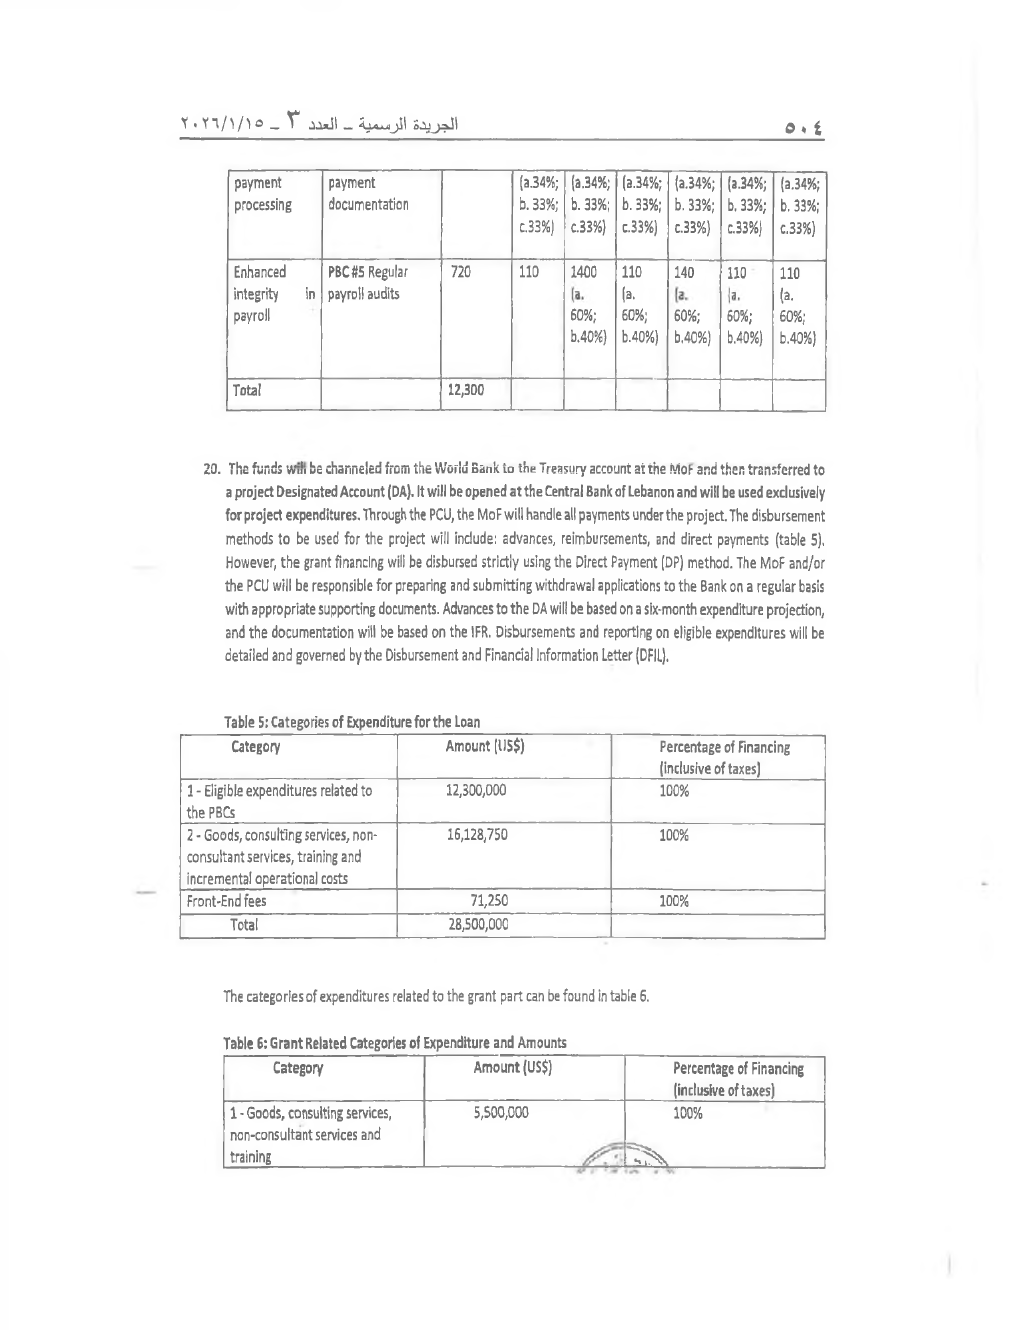
(1) ) Goods, works, non-consulting services, consulting services, Operating Costs, and Training for the Eligible Expenditures Program under the Project | 12,300,000 | 5,000,000
(2) Goods, works, non-consulting services, and consulting services, Operating Costs, Training under the Project (except for expenditures under category 1 and Parts 1.3 (a) and 2,4 (a) of the project | 16,128,750 | 23,428,750
(3) Front-end Fee | 71,250 | 71,250
TOTAL AMOUNT | 28,500,000 | 28,500,000
(b) Performance-Based Conditions (PBCs) adjustment (See / (see Annex 1 for details of the PBCs):
• / ■ Allocations: The current allocation of US$12.3 million for PBCs is proposed to be revised to US$5 million, and the allocation for each PBC has been revised, as shown in Table 3. PBC #4: —System-generated reports show reduced time for reviews of payment documents for third parties and pension payments, will be cancelled. The remaining PBCs will be made scalable, with provisions for the rollover of undisbursed funds to subsequent years.
TABLE 3 CHANGE IN PBC ALLOCATION
Performance Based Conditions | Original Allocation US$ | Revised Allocation US$
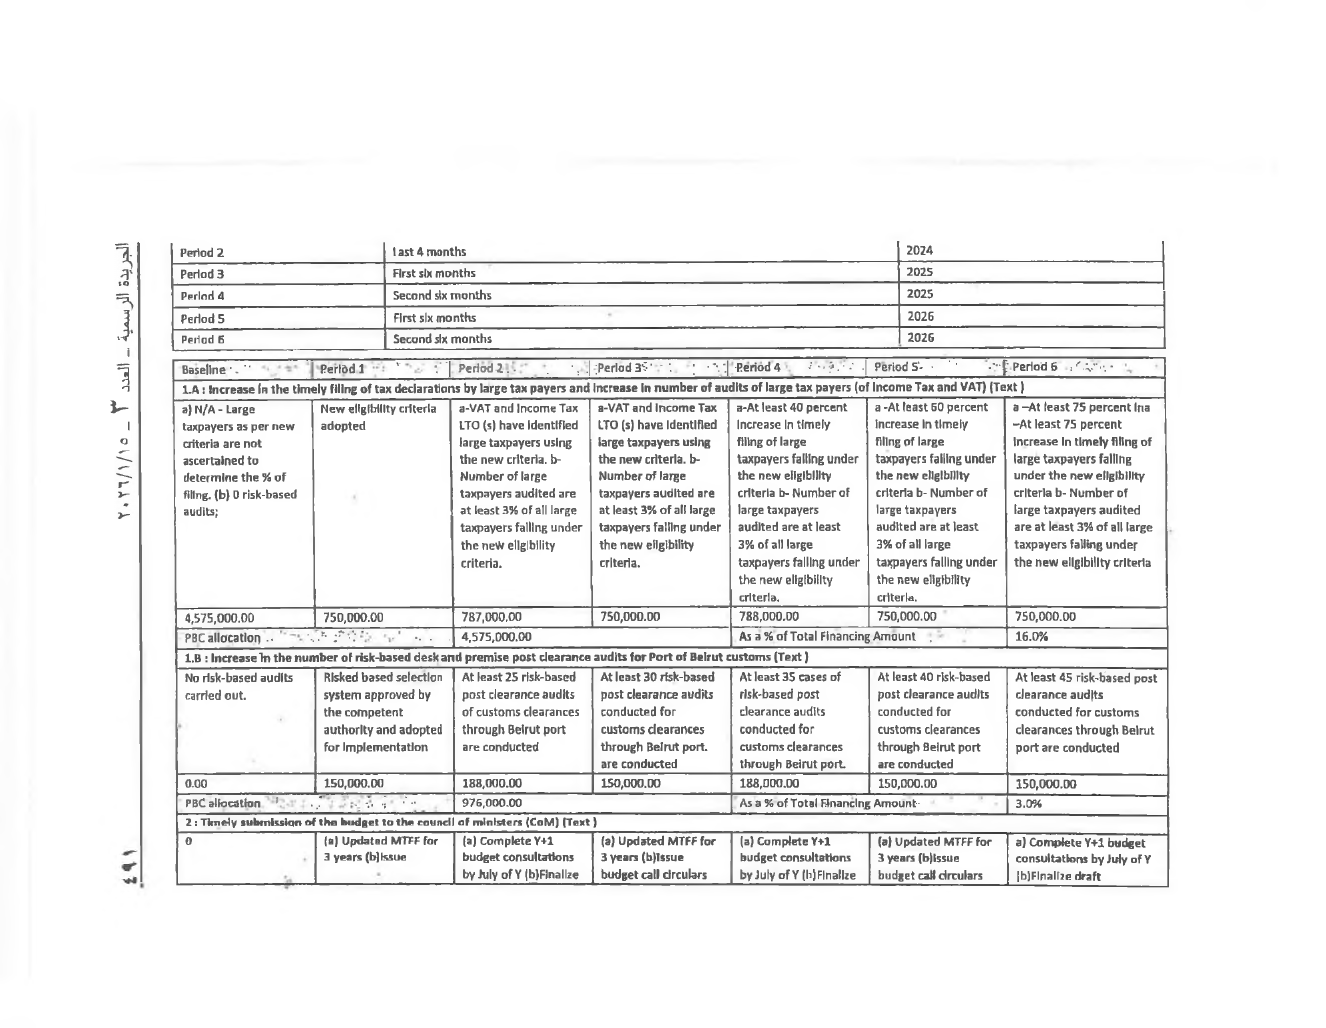
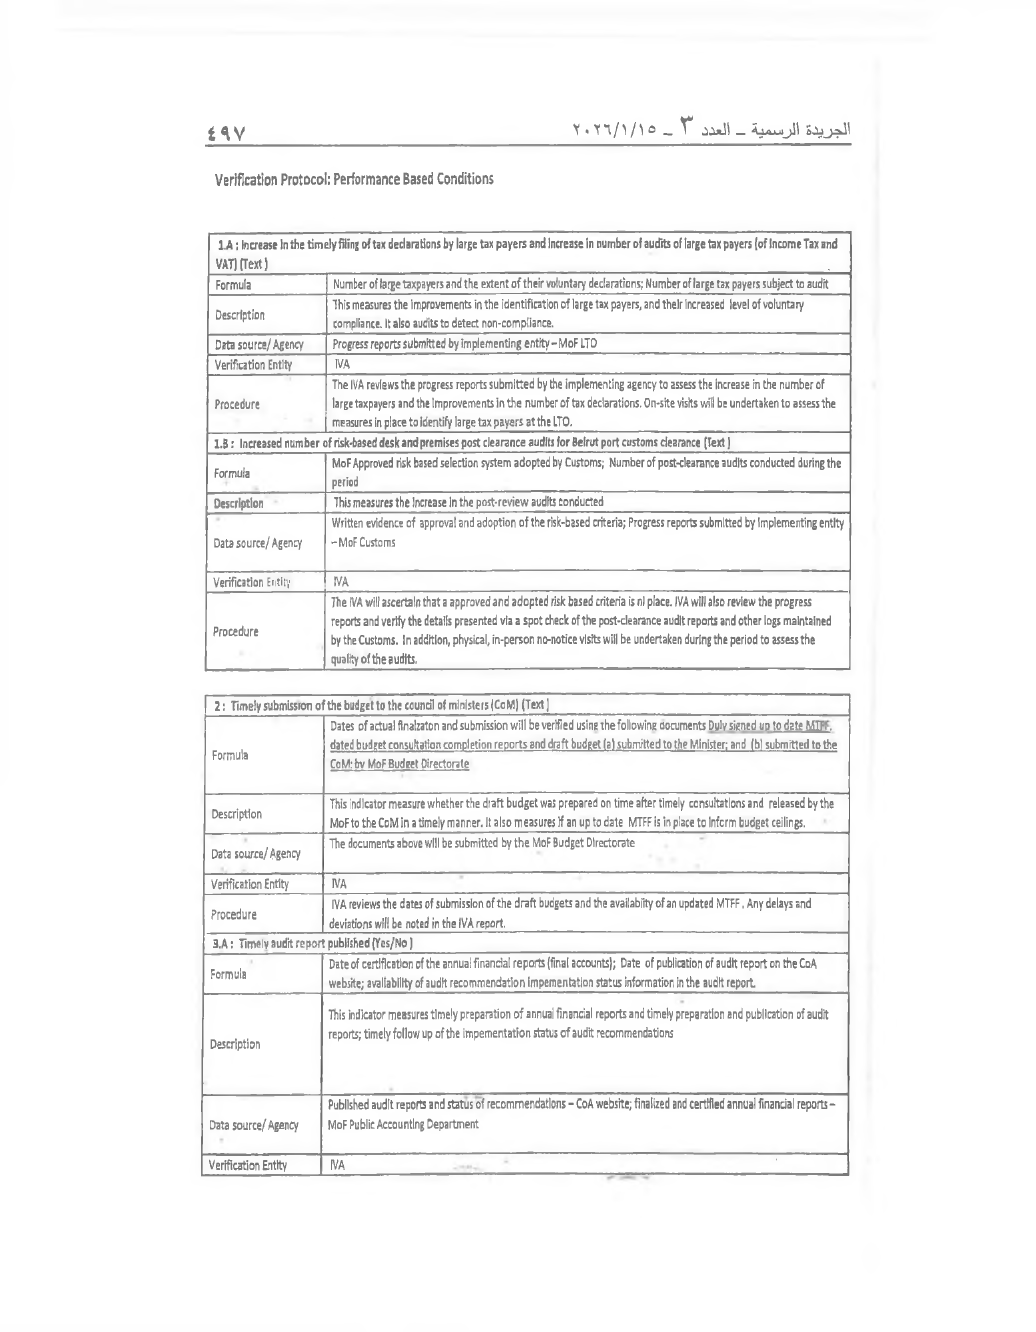
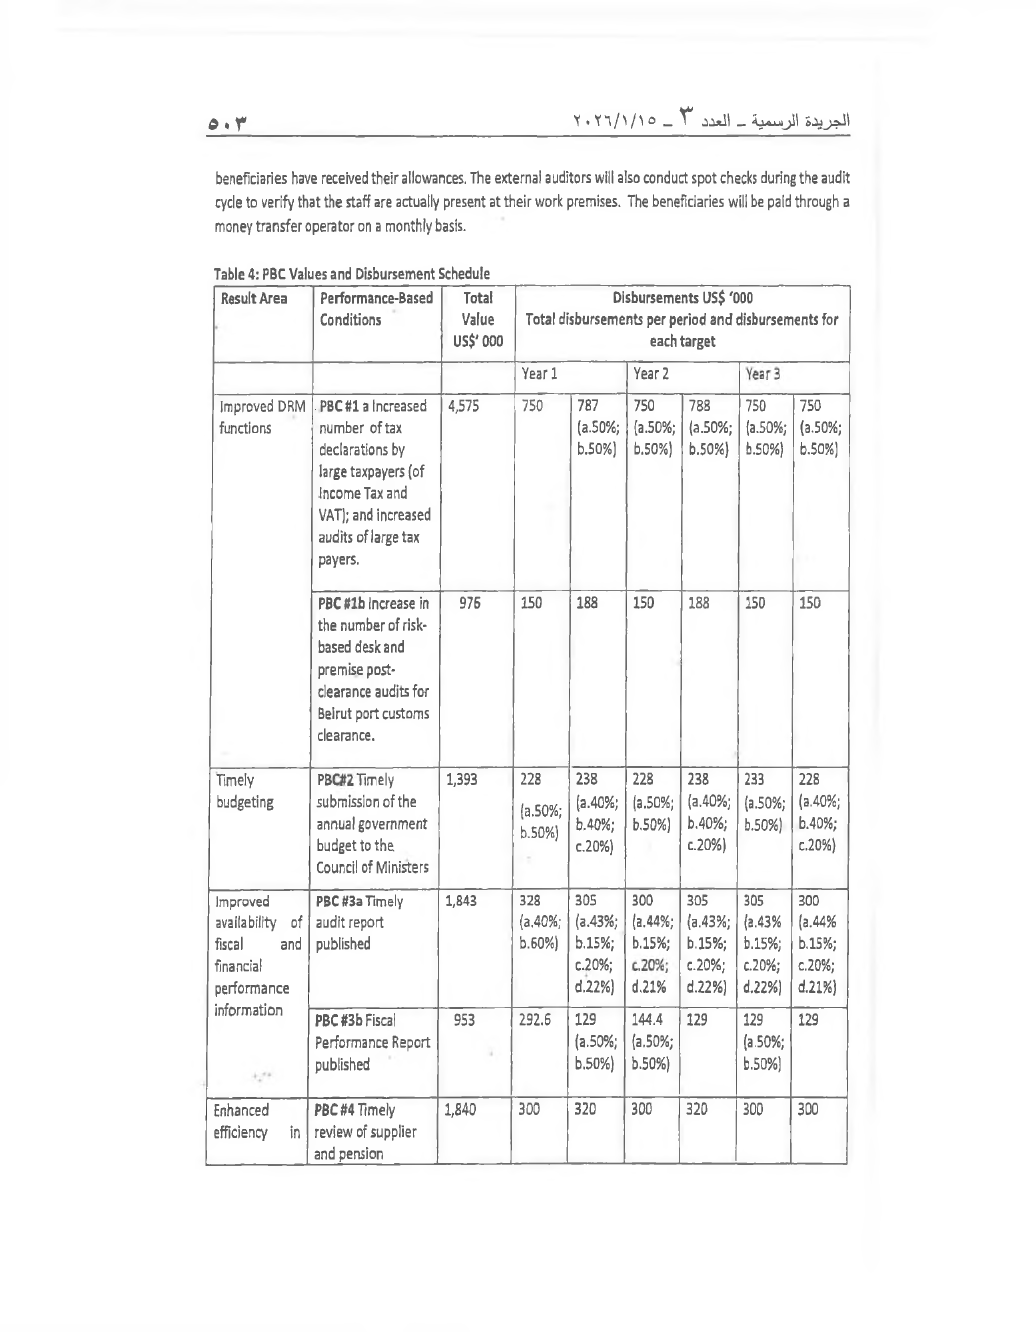
1a. Increased timely filing of tax declarations and timely payment of taxes by large taxpayers (of Income Tax and VAT) up to 75% of all large taxpayers | 4,575,000.00 | 500,000.00
1b. Increased number of risk-based desk and premises post clearance audits for Beirut port customs clearance | 976,000.00 | 500,000.00
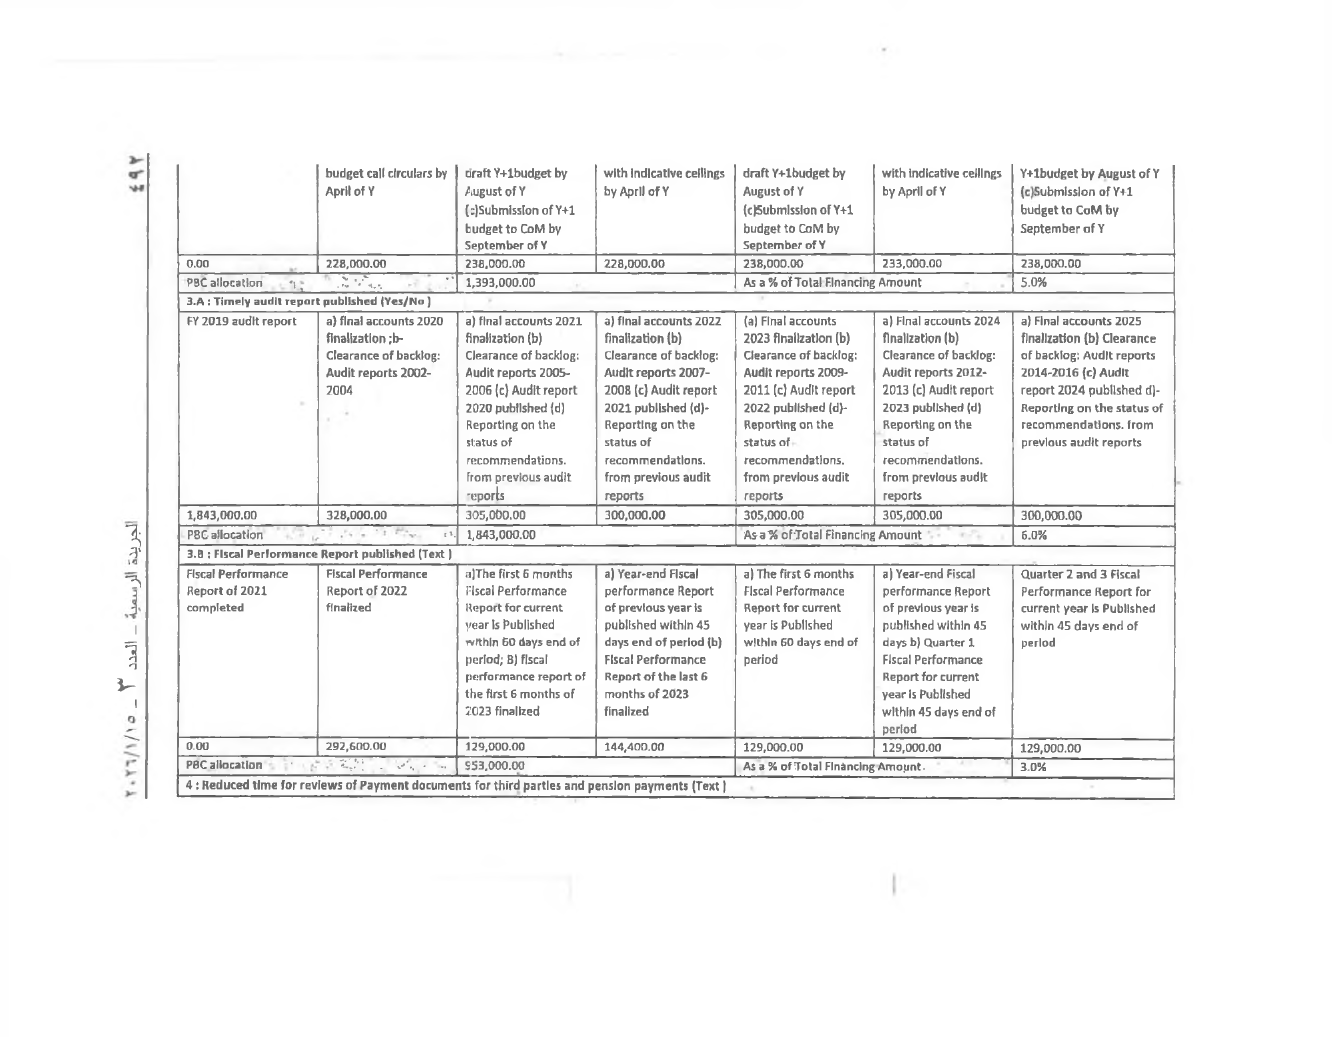
2. Timely submission to the Council of Ministers of a budget linked to macro fiscal framework | 1,393,000.00 | 2,000,000.00
3a. Timely audit report published | 1,843,000.00 | 500,000.00
3b. Fiscal Performance Report published | 953,000.00 | 500,000.00.
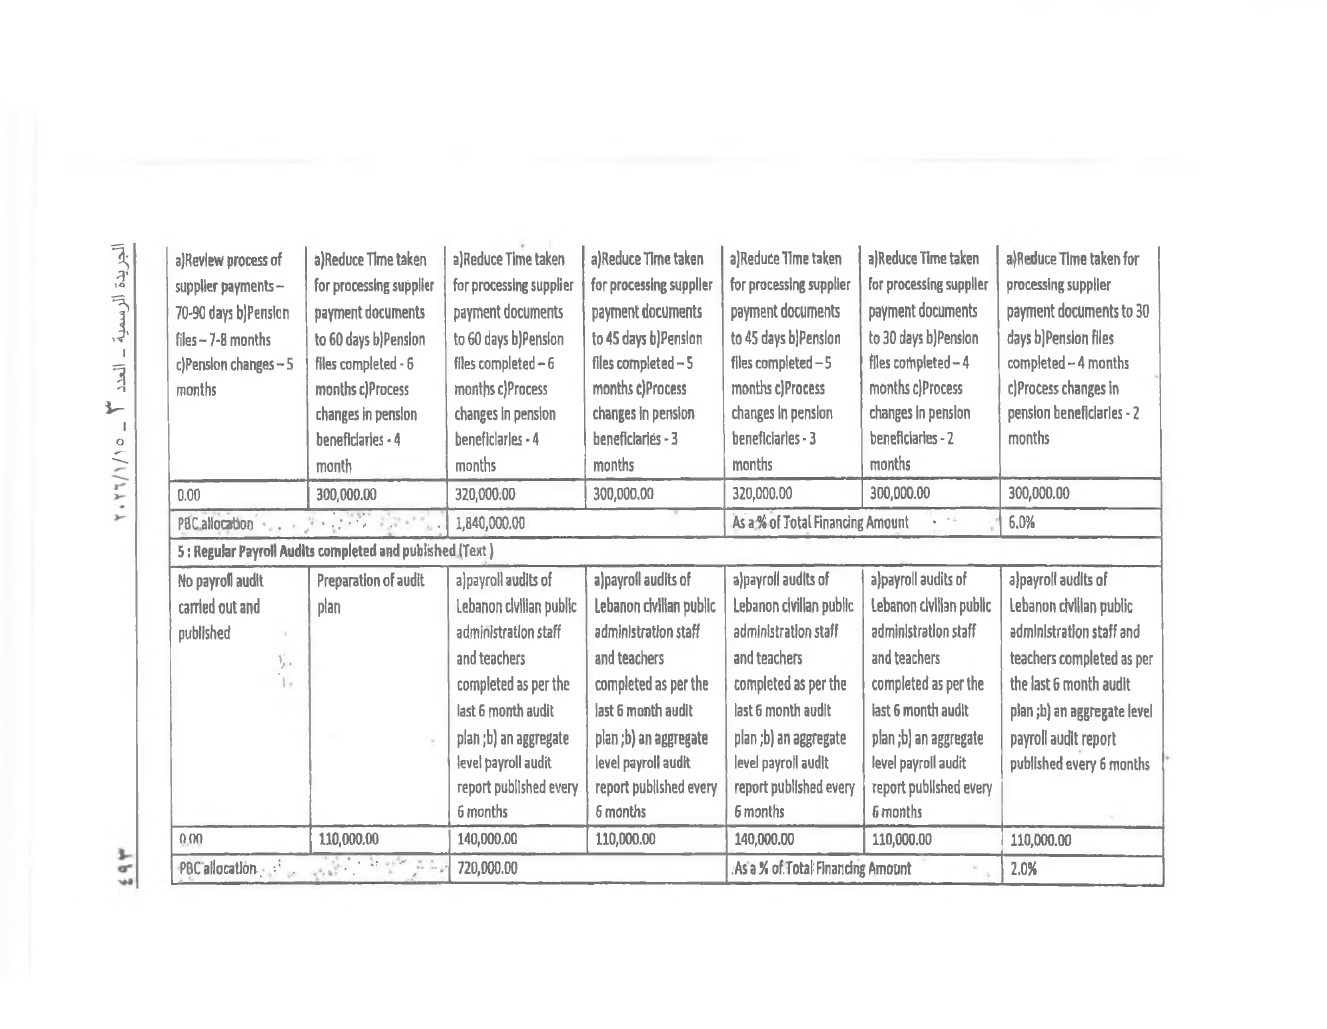
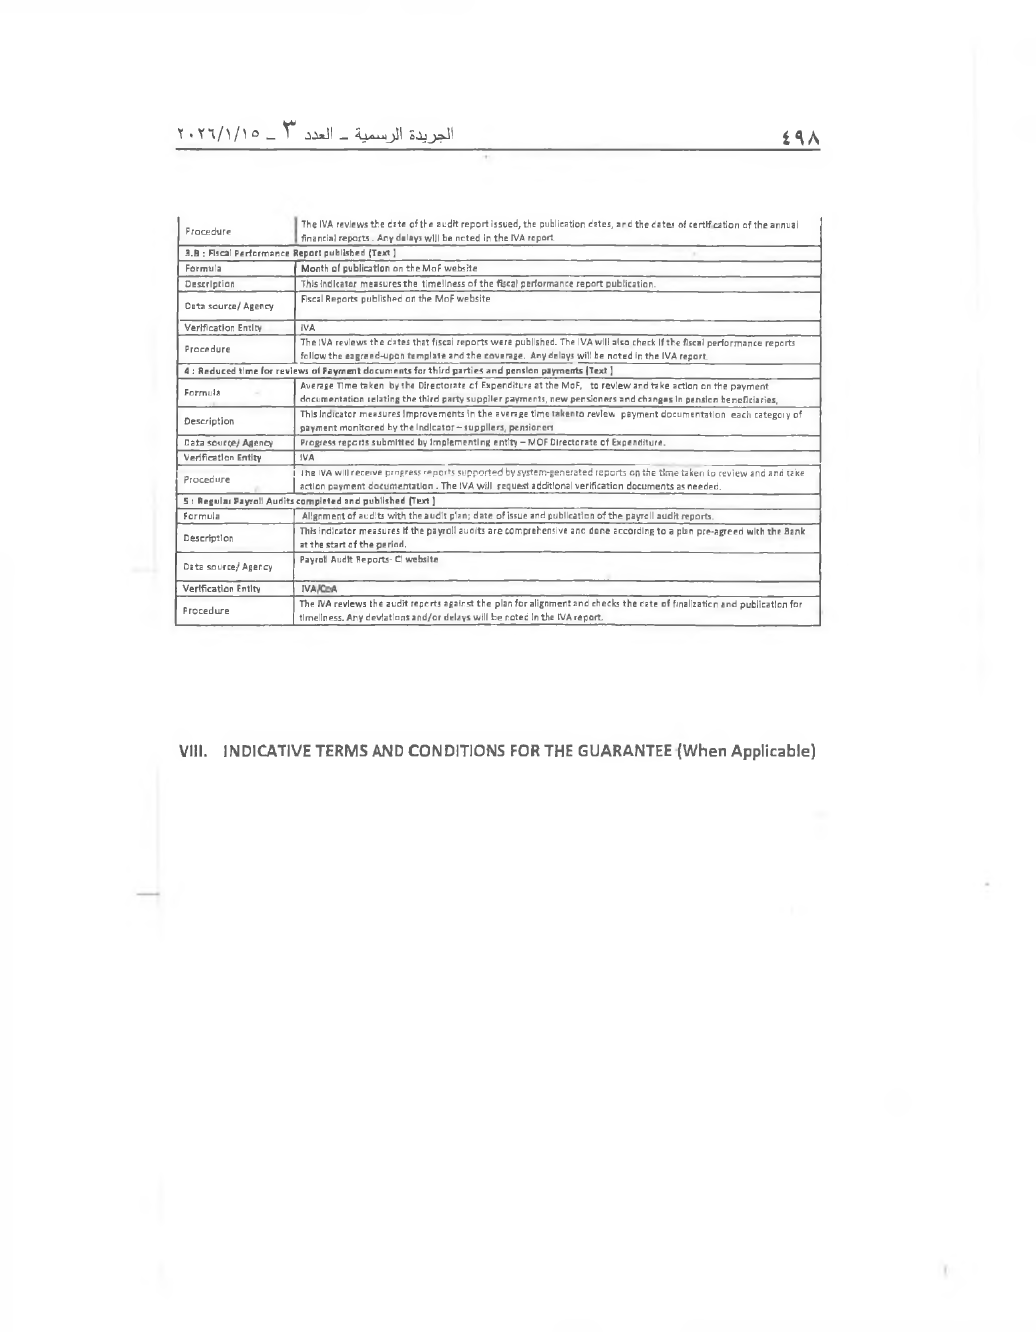
4. Reduced time for reviews of Payment documents for third parties and pension payments | 1,840,000.00 | Cancelled
5. Regular Payroll Audits published | 720,000.00 | 1,000,000.00
TOTAL: | 12,300,000.00 | 5,000,000.00
(c) Closing date. The closing dates of the loan will be extended to December 31, 2028, i.e., for a period of 21 months each, to accommodate the complex IT system implementation and ensure achievement of the PDO.
The grant closing date will be extended from June 30, 2025, to October 31, 2025, with no grace period, in line with the internal LFF exceptional extension approval.
(d) The Results Framework (RF). PDO and IRI are proposed to be modified to change the dates for the intermediate target dates by 21 months in the light of the new closing date and the status of the date of the restructuring.
(e) Disbursement Estimates. The disbursement estimates are proposed to be revised based on disbursements to date and the estimated disbursements during the remainder of the extended project period based on the revised project implementation plan agreed with the Bank.
Changes to Project Components
The Project components after the restructuring will be as follows:
12. Component 1: Stabilizing Domestic Revenue Administration (US$14.1 million: loan US$ 10.6 million and grant US$ 3.5 million). The proposed description of Component 1 is as follows: The amount of US$5.5 million that is currently allocated for allowance will be fully re-allocated to the development and implementation of an Integrated Tax Administration System (ITAS). The new modern system will contribute to achieving enhanced operational efficiency, improved compliance, reduction in revenue leakages, better revenue management, and enhanced service delivery.
Component 2: Restoring Fiscal Controls (US$ 15 million: loan US$13 million; grant US$ 2 million). The following changes will be made to the description of Component 2: The allowances for civil servants ($4.2 million) will be no more provided, instead all the related funding will be used for the development of an "Integrated Public Financial Management System" (IFMIS) / (IFMS) capable of producing timely, relevant, and reliable financial data to enable evidence-based policy making to promote fiscal discipline, optimize resource allocation, and improve operational efficiency and fiscal transparency. Additional re-allocation of $2.6 million from component 3 is done to secure the necessary funding for IFMIS. The restructuring will also cover further reforms, and technical assistance will be provided to review the Budget classification and Chart of Accounts (BC-CoA). It will also lay the foundation of / pf a treasury Single Account (TSA) framework with the aim of improving liquidity management and availability of real-time information on budget execution (both revenues and expenditures). Additionally, the IT support function within MoF will be strengthened with additional IT consultants as needed, to document the current system, manage data migration from current to new hardware; train end users; fix glitches and carry out necessary updates to the current software while a new IFMIS is developed and implemented. Business process re-engineering (BPR) will also be carried out to streamline MoF workflows and improve efficiency including legal recognition of the validity of digital PFM process.
13. Component 3: Revitalizing Oversight and Accountability Institutions and Procurement Capacity Building (USD$2.4 million: loan US$2.4 million; grant US$0). The following changes will be made to the description of Component 3: The allowances for civil servants will no more be provided. Instead, the funding will be used for
technical assistance, operating costs needed for these oversight bodies, training, and IT enhancements so to build capacity of civil servants on PFM, public procurement. This will entail the development of e-learning platforms and e-modules so to provide structured learning opportunities, technical support and continuous improvement of educational resources for public servants. E-learning platforms allow flexibility, accessibility and cost effectiveness, and reduces the need for physical infrastructure and travel leading to significant cost savings.
Implementation arrangements
14. Environmental and Social (E&S) Arrangements. The restructuring does not introduce any new activities; however, the SEP and other Environmental and Social Framework (ESF) documents will be updated to reflect the revised component allocations and will be redisclosed no later than 60 days after the loan becomes effective.
15. Financial Management (FM) Arrangements. The existing FM arrangements will remain in place.
16. Procurement Arrangements. Procurement arrangements for the project will remain unchanged. Planned procurement following the restructuring will include procurement of IFMIS and ITAS. The project procurement strategy for development (PPSD) will be updated based on the new planned activities and as needed. The Bank may, at the request of the Borrower, provide Hands-on Expanded Implementation Support (HEIS) to help expedite the procurement arrangements.
III. PROPOSED CHANGES
Operation Information | Proposed Changes | Operation Information | Proposed Changes
Results | Yes | Loan Closing Date Extension | Yes
Disbursements Estimates | Yes | Reallocations | Yes
Components | Yes | Implementation Schedule | Yes
Development Objective | No | Loan Cancellations | No
Financial Management | No
Procurement | No
Institutional Arrangement | No
Action | Proposed Component Name | Proposed Cost (USD)
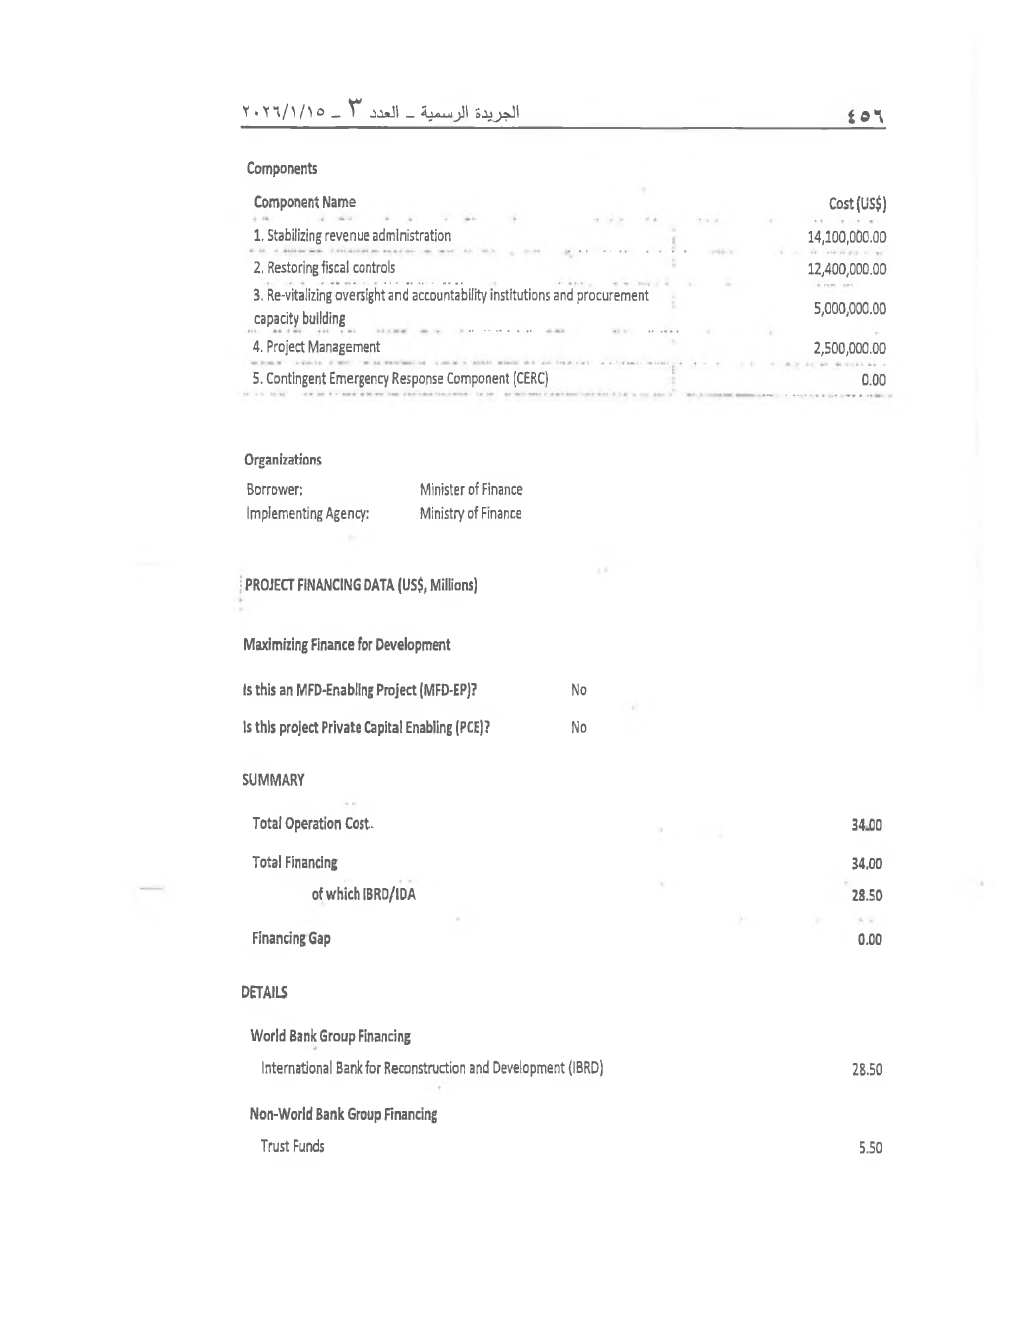
No Change | 1. Stabilizing Domestic Revenue Administration | 14,100,000.00
Revised | 2. Restoring fiscal controls | 15,000,000.00
Revised | 3. Re-vitalizing oversight and accountability institutions and procurement capacity building | 2,400,000.00
No Change | 4. Project Management | 2,500,000.00
No Change | 5. Contingent Emergency Response Component (CERC) | 0.00
34,000,000.00
Summary Description (Operation Abstract) | No
Legal Operational Policies | No
MFD/PCE | No
Risks | No
Legal Covenants | No
Conditions | No
Implementation Modalities | No
Disbursements Arrangements | No
DDO | No
Additional Regional Institutions | No
Clients | No
Appraisal Summary | No
IV. DETAILED CHANGE(S)
COMPONENTS
Current Component Name | Current Cost (USD)
1. Stabilizing Domestic Revenue Administration | 14,100,000.00
2. Restoring fiscal controls | 12,400,000.00
3. Re-vitalizing oversight and accountability institutions and procurement capacity building | 5,000,000.00
4. Project Management | 2,500,000.00
5. Contingent Emergency Response Component (CERC) | 0.00
TOTAL | 34,000,000.00
COSTS & FINANCING
No
No
Revised Closing(s) | Proposed Closing | Proposed Deadline for Withdrawal Applications
31-Mar-2027 | 31-Dec-2028 | 30-Apr-2029
30-Jun-2025 | 31-Oct-2025 | 31-Oct-2025
Cancellations (if any): 0.00 | New Allocation:
0.00 | 0.00 Financing % (Type Total) / …
Actuals + Committed | Proposed Allocation | … / Financing % (Type Total) Current | Proposed
0.00 | 5,000,000.00 | 100.00 | 0.00
0.00 | 23,428,750.00 | 100.00 | 0.00
0.00 | 0.00 | 100.00 | 0.00
0.00 | 0.00 | 100.00 | 0.00
71,250.00 | 71,250.00 | 0.00 | 0.00
28,500,000.00
Cancellations (if any): 0.00 | New Allocation:
0.00 | 0.00
Actuals + Committed | Proposed Allocation | Financing % (Type Total)
Private Capital Facilitation
Is this an MFD-Enabling Project (MFD-EP)?
last / Last approved as part of PAD Data Sheet (Approval) on 14-Feb-2024
Is this project Private Capital Enabling (PCE)?
Last approved as part of PAD Data Sheet (Approval) on 14-Feb-2024
LOANS
Loan Closing
Loan/Credit/Trust Fund | Status | Original Closing
IBRD-96440 | Not Effective | 31-Mar-2027
TF-C3381 | Effective | 30-Jun-2025
Reallocations
IBRD-96440-001 | Currency: USD
Category No. | Expenditure Category | Current Allocation
1 | EG P1.1a,1.2a,2.1a-2.3a,3.1ai,3.1bi; | 12,300,000.00
2 | G,W,NCS,CS,OC,T EX P1.3a,2.4a,CAT11; | 16,128,750.00
4 | INTEREST RATE CAP AND COLLAR; | 0.00
5 | EMERGENCY EXP PART 5; | 0.00
… / | FRONT END FEE; | 71,250.00
… / | Total | 28,500,000.00
TF-C3381-001 | Currency: USD
Category No. | Expenditure Category | Current Allocation
Current | Proposed
100.00 | 0.00
Actual
0.00
648,742.45
0.00
0.00
0.00
0.00
No
1 | G;NCS;CS;OC;T Parts 1.3a & 2.4a; | 5,500,000.00 | 1,881,303.85 | 5,500,000.00
Total | 5,500,000.00 | 5,500,000.00
DISBURSEMENTS
Operation Dates & Projection Details
Reasons to change the full Disbursement date and/or the projection
Restructuring
Implementation Start Date | Operation Closing Date
14-Feb-2024 | 31-Mar-2027
Projected Date for Full Disbursement
30-Apr-2029
Expected Disbursements (in US $) (Absolute)
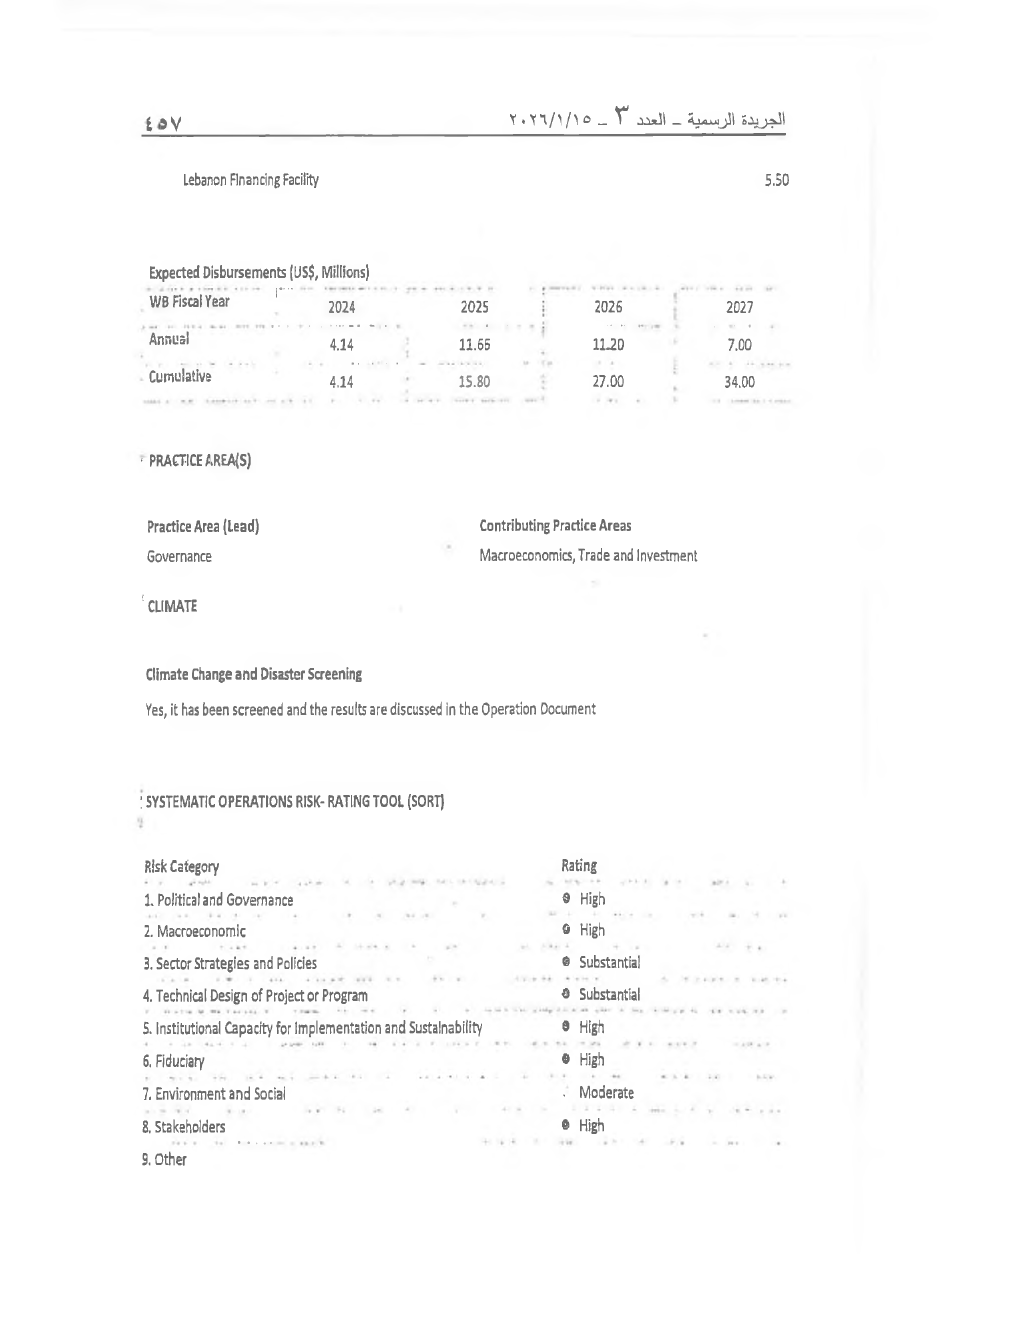
Year | Original Estimation at Preparation (Approval Package - 14 Feb 2024) | Revised Estimation
FY2024 | 4,136,907.31 | 0.00
FY2025 | 11,660,713.43 | 3,500,000.00
FY2026 | 11,202,379.26 | 6,000,000.00
FY2027 | 7,000,000.00 | 9,000,000.00
FY2028 | 0.00 | 15,500,000.00
FY2029 | 0.00 | 0.00
ENVIRONMENTAL & SOCIAL
Environmental & Social Assessment
According to the E/S Specialist are there changes proposed to the operation's design that would impact the Bank's E&S assessment?"
Actual (Current) | Closing Period
Result | Date | Result | Month/Year
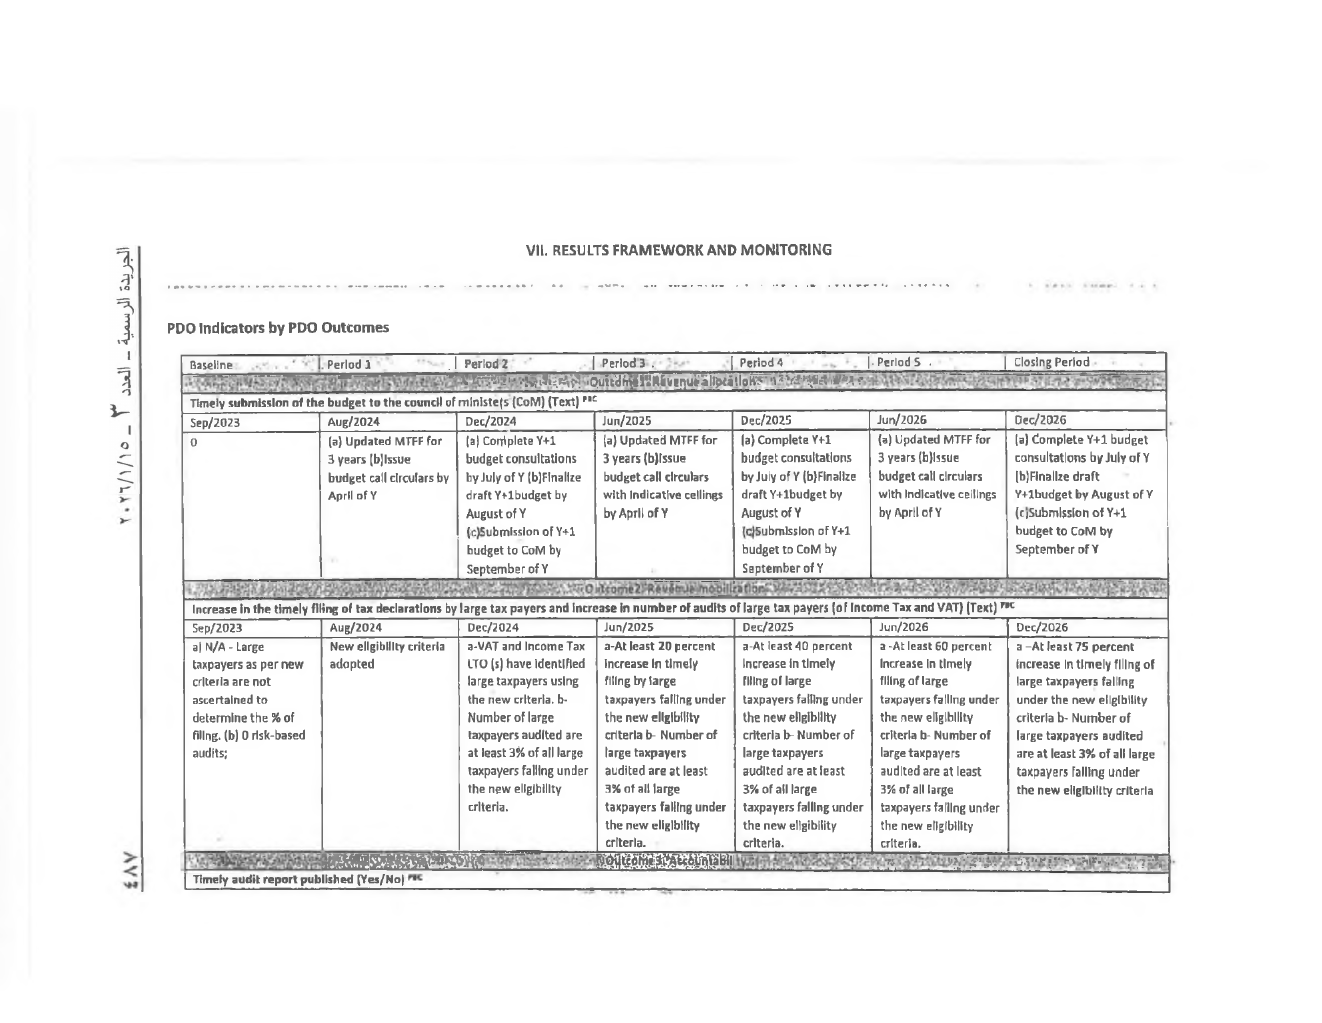
0 | 31-Mar-2025 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY (b) Finalize draft FY+1 budget within 8 months of the relevant FY | Dec/2028
Actual (Current) | Closing Period
Result | Date | Result | Month/Year
me as baseline | 31-Mar-2025 | (a) At least 75 percent of the Identified / identified large taxpayers timely file declarations and pay taxes (b) Number of large taxpayers audited are at least | Dec/2028
RESULTS
COUNTRY: Lebanon
Fiscal Management Project
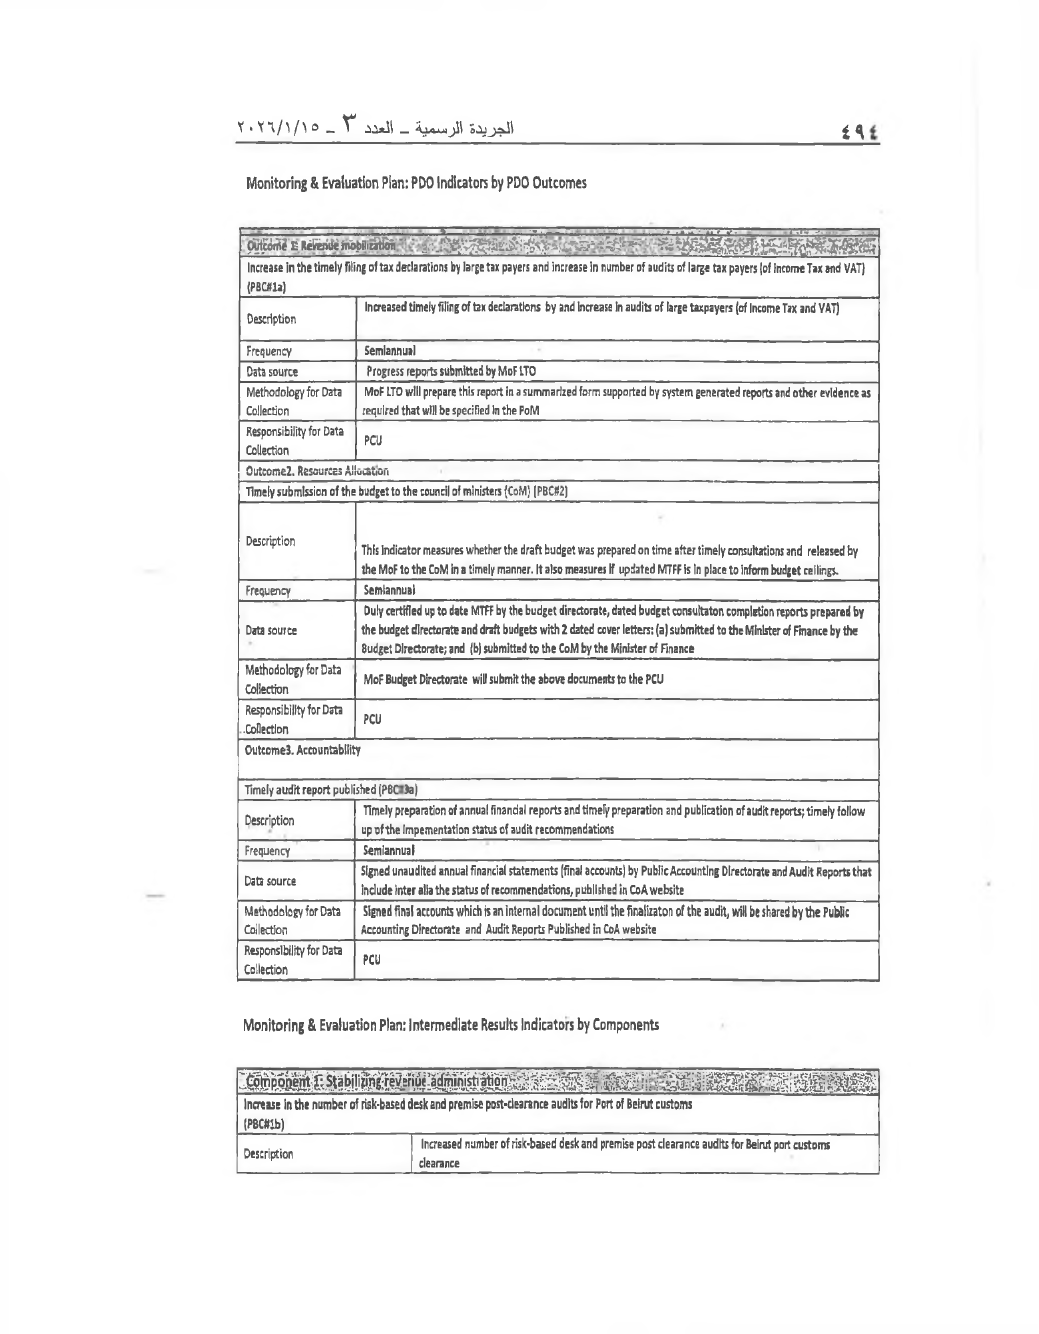
PDO Indicators by PDO Outcomes
Outcome1. Revenue Allocation / allocation
Indicator Name | Baseline | Actual (Previous)
Result | Month/Year | Result | Date
Revised / Revise Timely submission of the budget to the council of ministers (CoM) (Text) PBC | 0 | Sep/2023 | 0 | 31-Mar-2025
Outcome2. Revenue Mobilization / mobilization
Indicator Name | Baseline | Actual (Previous)
Result | Month/Year | Result | Date
Revised / Revise Increase in the timely filing of tax declarations by large tax payers and increase in number of audits of large tax payers (of Income Tax and VAT) (Text) PBC | (a) N/A - Large taxpayers as per new criteria are not ascertained to determine the % of filing (b) 0 risk-based audits | Sep/2023 | Same as baseline | 31-Mar-2025
… / | Sa الجريدة الرسمية - العدد ٣ - ٢٠٢٦/١/١٥
| | | | 3% of all large taxpayers falling under the new eligibility criteria |
Actual (Previous) | Actual (Current) | Closing Period
Result | Date | Result | Date | Result | Month/Year
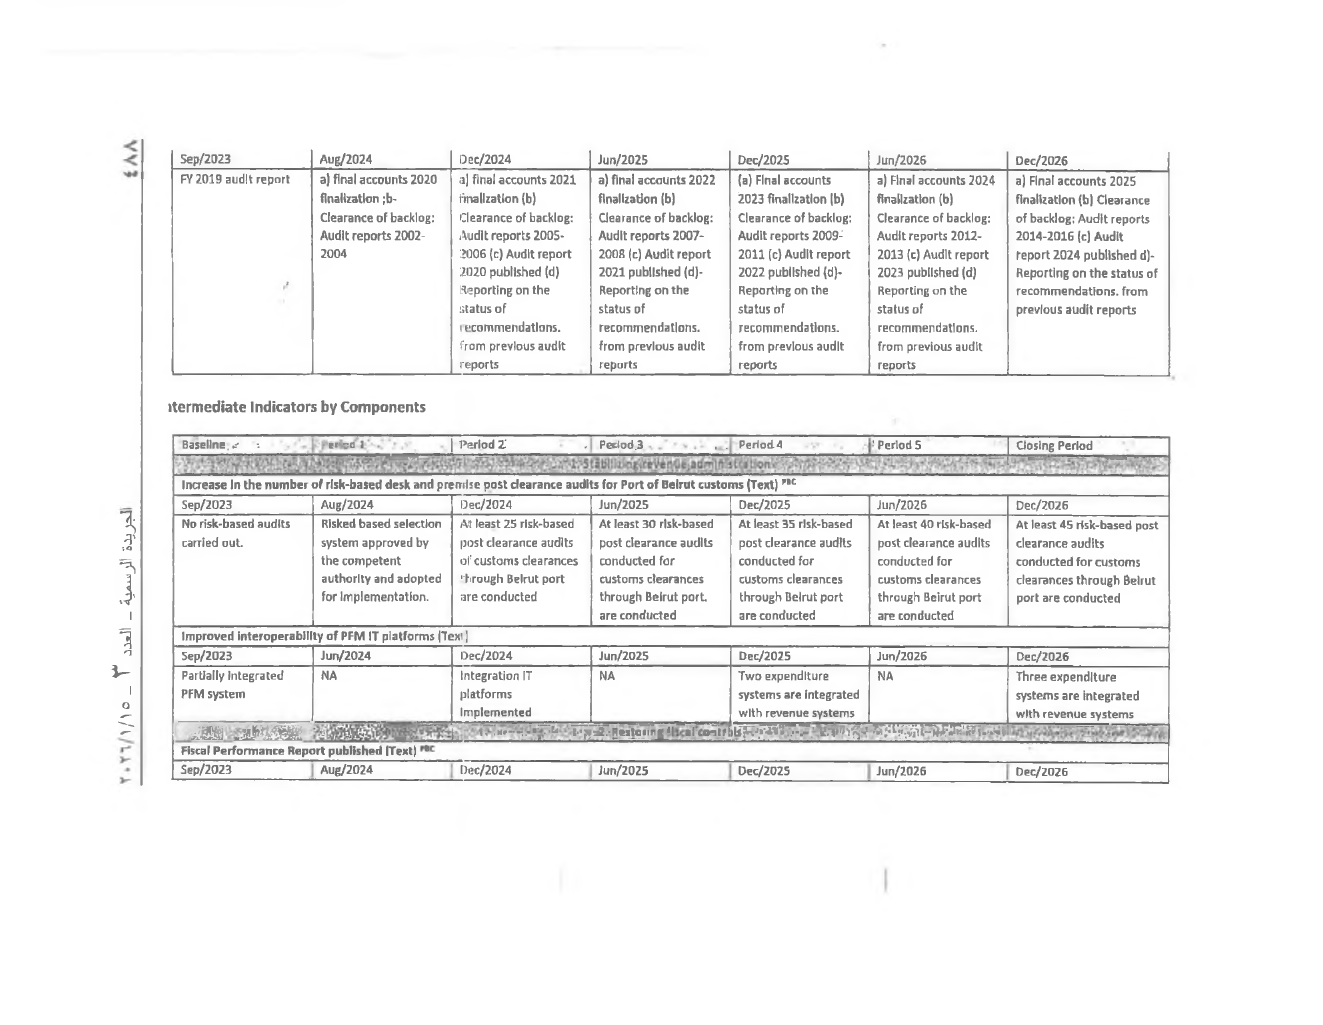
Same as baseline | 30-Jun-2025 | Same as baseline | 30-Jun-2025 | (a) Final accounts 2027 finalized by MoF (b) Clearance of backlog: Audit reports FY 2017-2018 (c) Audit report FY 2027 published (d) Reporting on the status of recommendations from previous audit reports | Dec/2028
Actual (Previous) | Actual (Current) | Closing Period
Result | Date | Result | Date | Result | Month/Year
same as baseline | 31-Mar-2025 | same as baseline | 31-Mar-2025 | At least 45 risk-based post clearance audits conducted for customs clearances | Dec/2028
… / Outcome 3: Accountability Indicator Name | Baseline
| Result | Month/Year
Revise Timely audit report published [Yes/No] PBC | FY 2020 audit report | Sep/2023
Intermediate Results Indicators by Components
1. Stabilizing Domestic Revenue Administration
Indicator Name | Baseline
| Result | Month/Year
Revise Increase in the number of risk-based desk and premise post clearance audits for Port of Beirut customs (Text) PBC | No risk-based audits carried out | Sep/2023
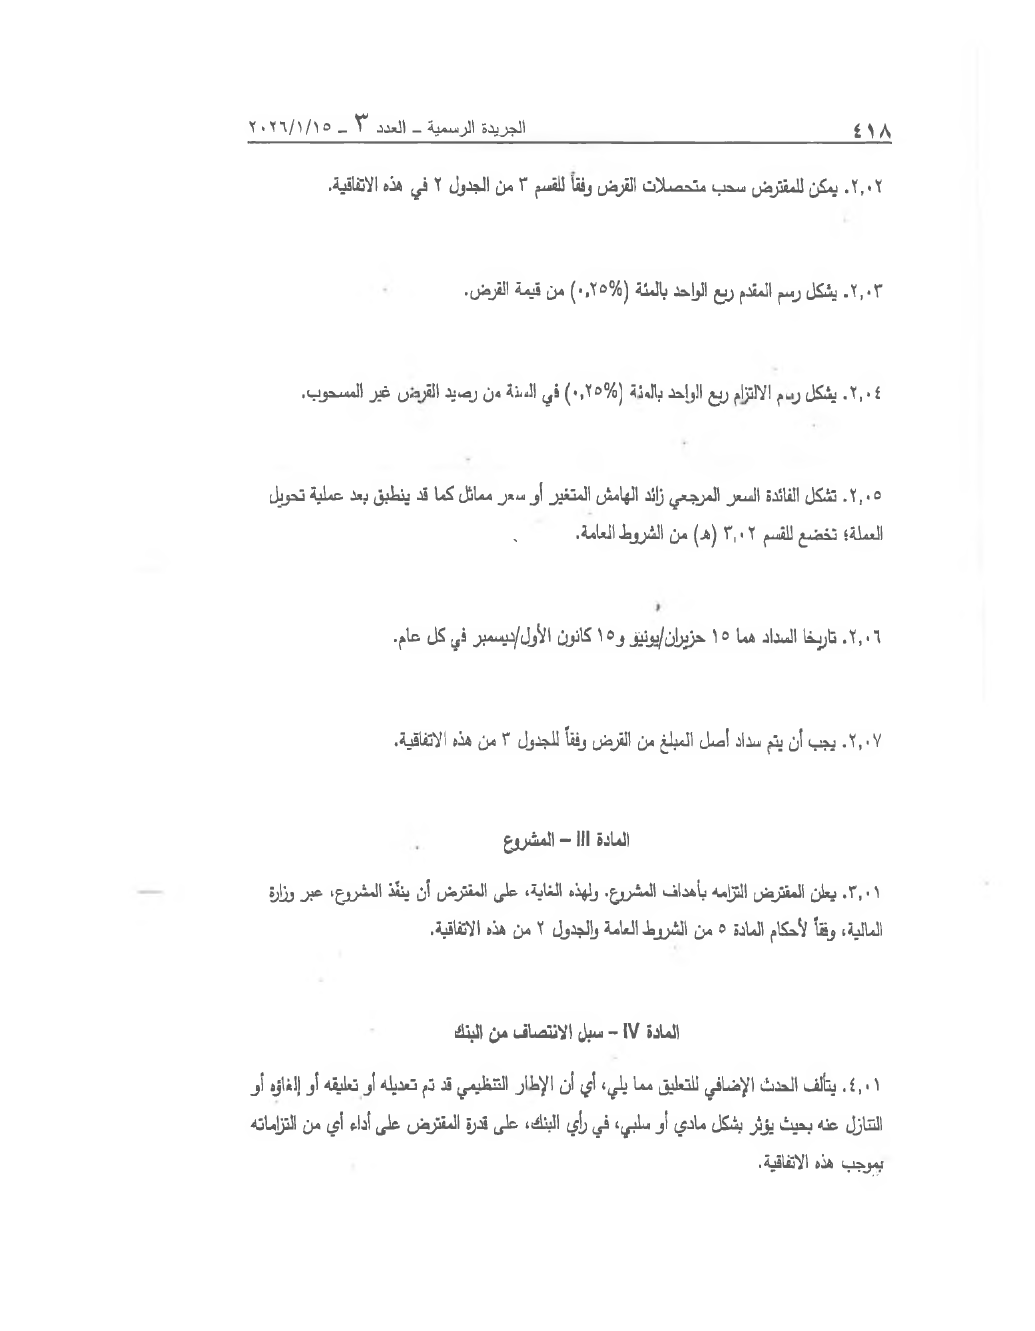
٢,٠٢. يمكن للمقترض سحب متحصلات القرض وفقاً للقسم ٣ من الجدول ٢ في هذه الاتفاقية.
٢,٠٣. يشكل رسم المقدم ربع الواحد بالمئة (٠,٢٥%) من قيمة القرض.
٢,٠٤. يشكل رسم الالتزام ربع الواحد بالمئة (٠,٢٥%) في السنة من رصيد القرض غير المسحوب.
٢,٠٥. تشكل الفائدة السعر المرجعي زائد الهامش المتغير أو سعر مماثل كما قد ينطبق بعد عملية تحويل العملة؛ تخضع للقسم ٣,٠٢ (هـ) من الشروط العامة.
٢,٠٦. تاريخا السداد هما ١٥ حزيران/يونيو و١٥ كانون الأول/ديسمبر في كل عام.
٢,٠٧. يجب أن يتم سداد أصل المبلغ من القرض وفقاً للجدول ٣ من هذه الاتفاقية.
المادة III - المشروع
٣,٠١. يعلن المقترض التزامه بأهداف المشروع. ولهذه الغاية، على المقترض أن ينفّذ المشروع، عبر وزارة المالية، وفقاً لأحكام المادة ٥ من الشروط العامة والجدول ٢ من هذه الاتفاقية.
المادة IV - سبل الانتصاف من البنك
٤,٠١. يتألف الحدث الإضافي للتعليق مما يلي، أي أن الإطار التنظيمي قد تم تعديله أو تعليقه أو إلغاؤه أو التنازل عنه بحيث يؤثر بشكل مادي أو سلبي، في رأي البنك، على قدرة المقترض على أداء أي من التزاماته بموجب هذه الاتفاقية.
same as baseline | 31-Mar-2025 | same as baseline | 31-Mar-2025 | Three expenditure systems are integrated with revenue systems | Dec/2028
Actual (Previous) | Actual (Current) | Closing Period
Result | Date | Result | Date | Result | Month/Year
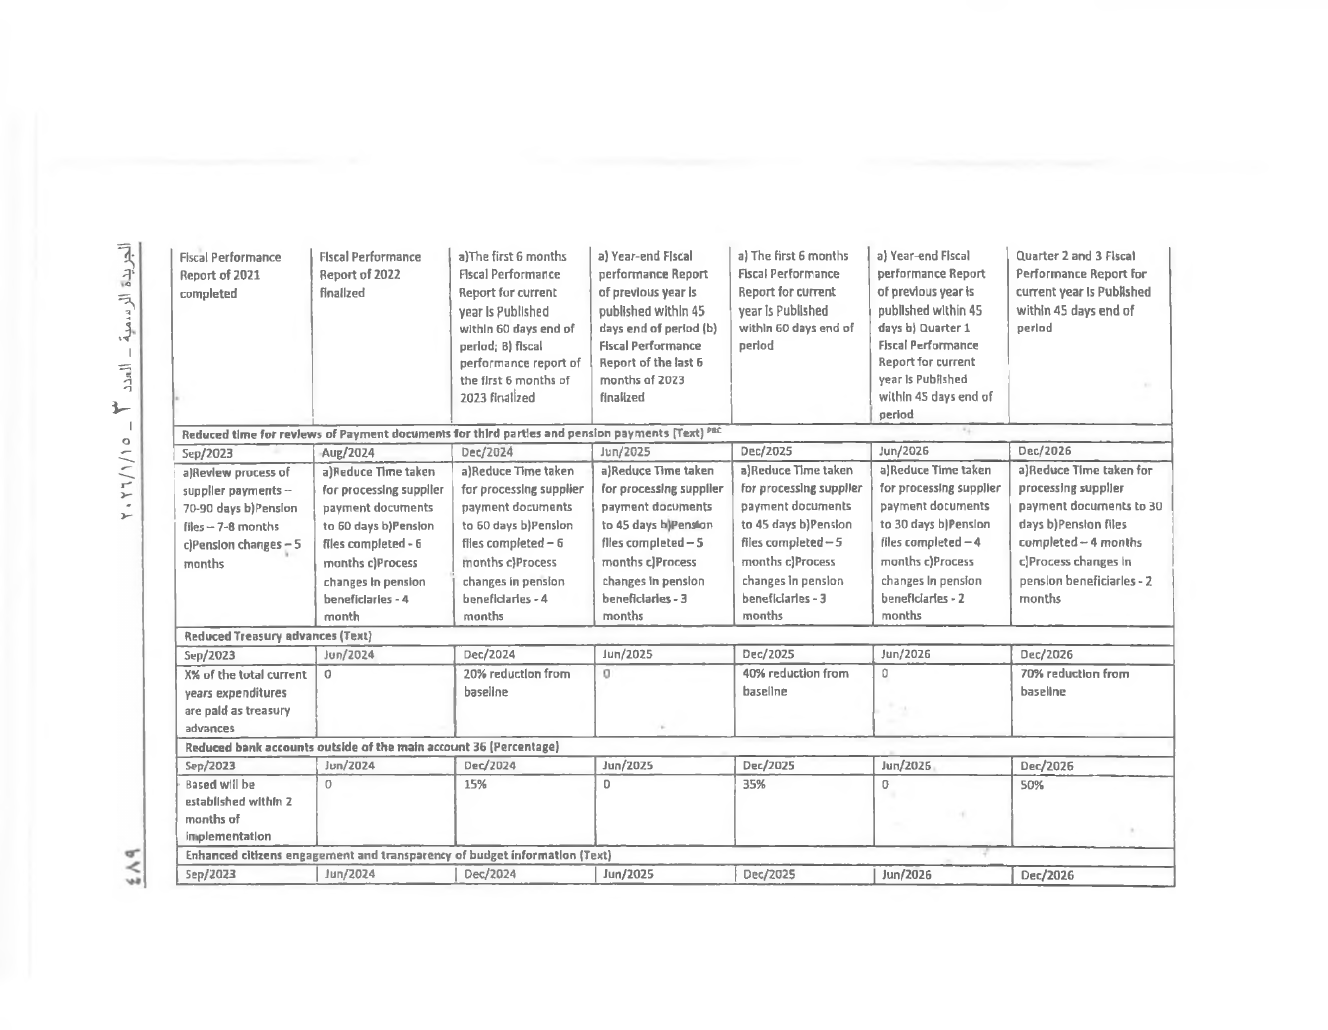
same as baseline | 31-Mar-2025 | same as baseline | 31-Mar-2025 | Quarter 2 and 3 Fiscal Performance Report for current FY is published within 20 days of the end of the period | Dec/2028
TBD once project implementation commences | 31-Mar-2025 | TBD once project Implementation / implementation commences | 31-Mar-2025 | 70% reduction from baseline | Dec/2028
TBD once implementation commences | 31-Mar-2025 | TBD once Implementation / implementation commences | 31-Mar-2025 | 50% | Dec/2028
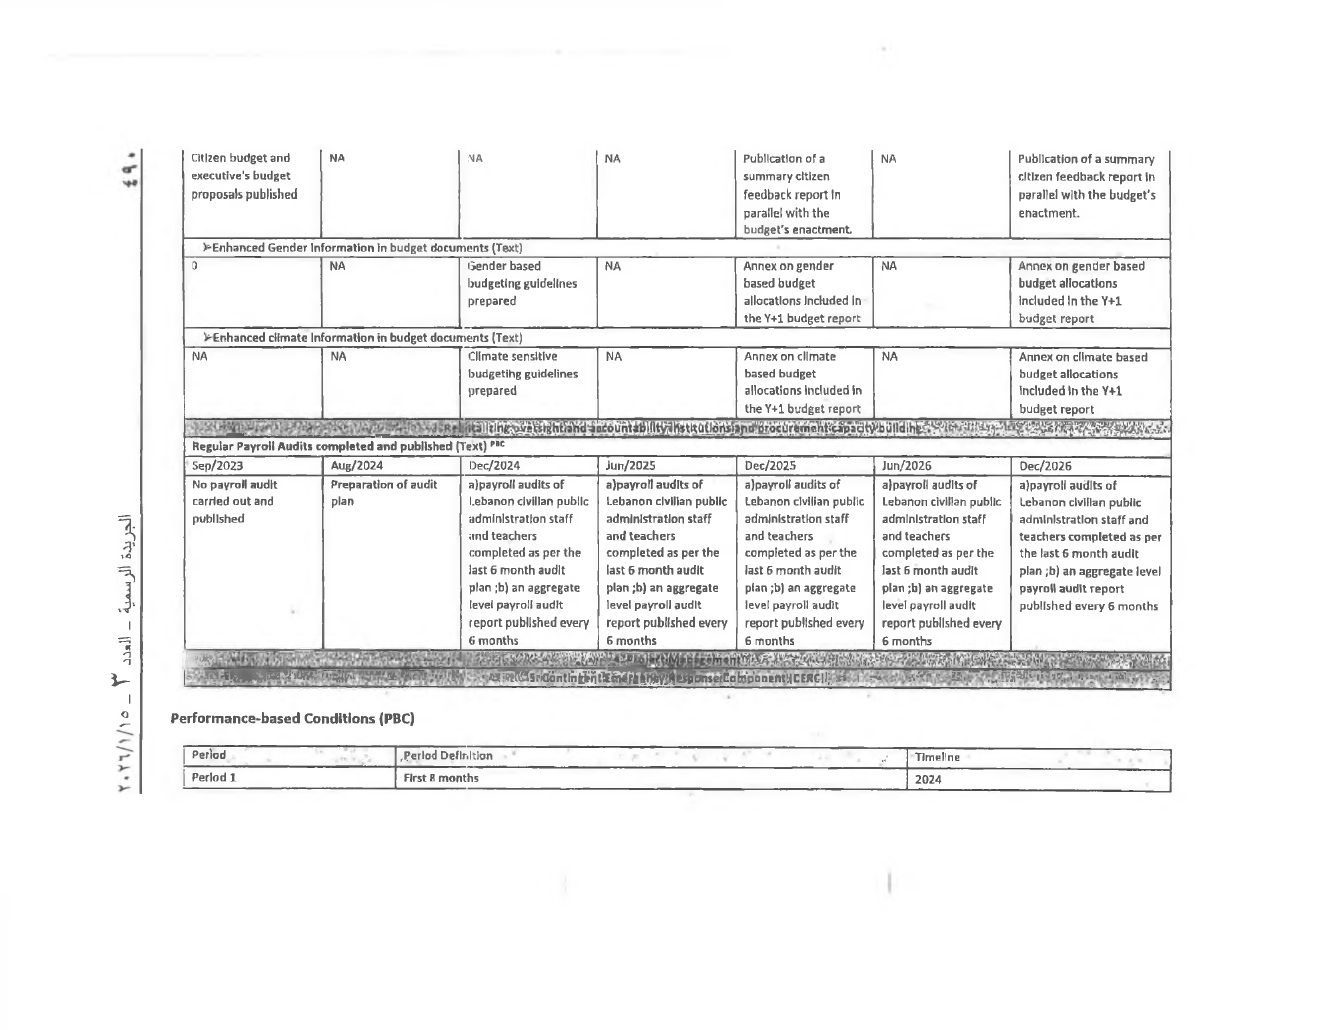
same as baseline | 31-Mar-2025 | same as baseline | 31-Mar-2025 | Publication of a summary citizen feedback report in | Dec/2028
Revised / Revise Improved interoperability of PFM IT platforms (Text) | Partially integrated PFM system | Sep/2023
2. Restoring fiscal controls (Revised) / Revise
Indicator Name | Baseline
Result | Month/Year
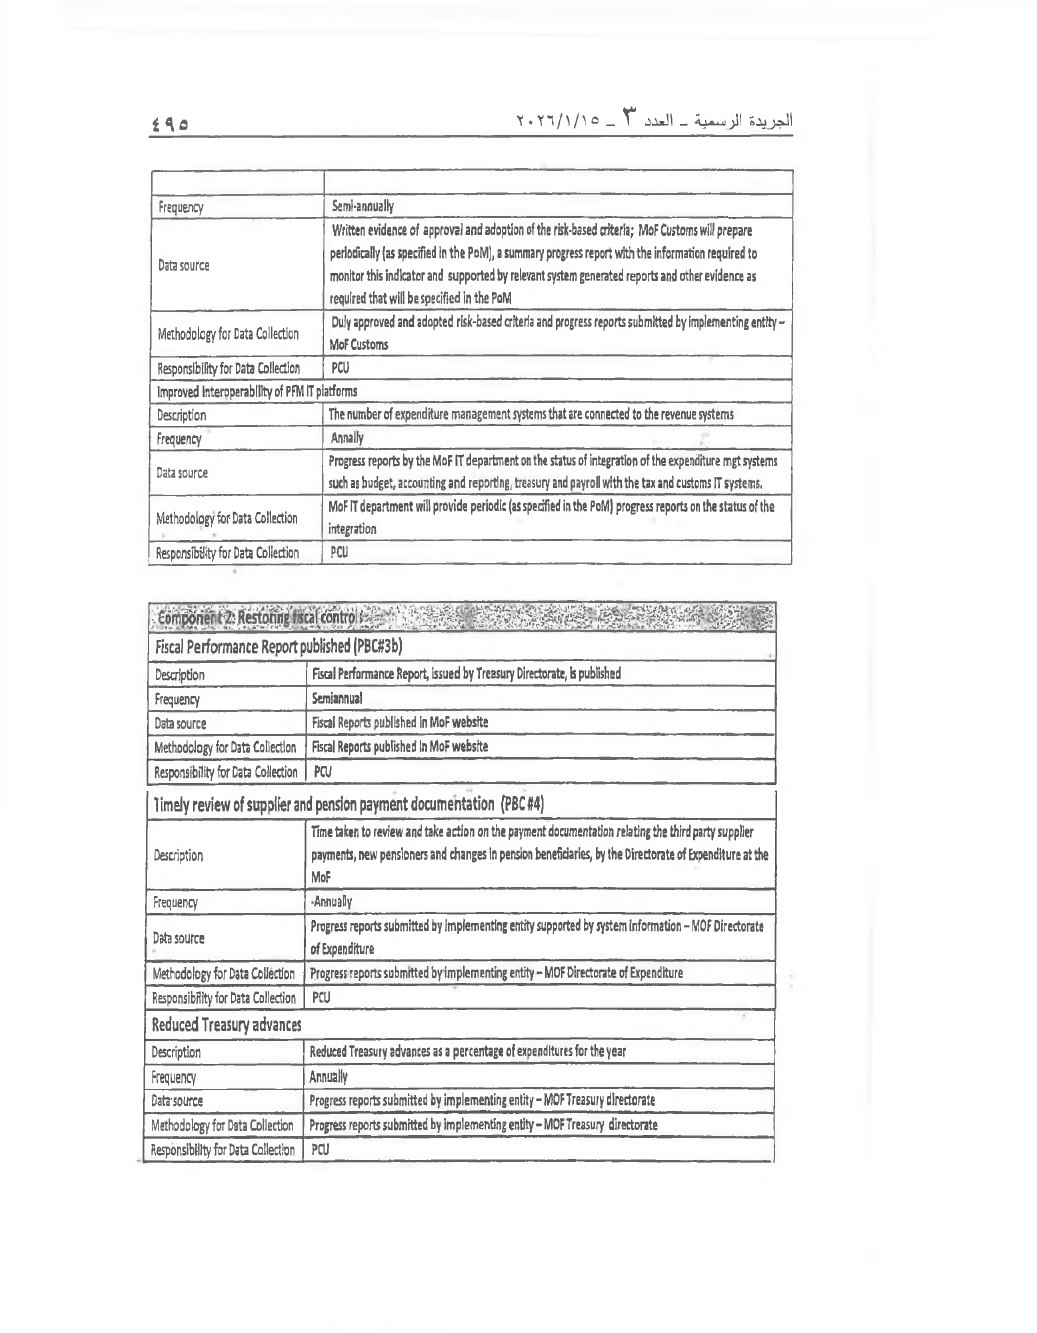
Revised / Revise Fiscal Performance Report published (Text) PBC | Fiscal Performance Report of 2021 completed | Sep/2023
Revised / Revise Reduced Treasury advances (Text) | % (to be determined during implementation) of the total current years expenditures are paid as treasury advances of the total current years expenditures are paid as treasury advances | Sep/2023
Revised / Revise Reduced bank accounts outside of the main account 36 (Percentage) | Based will be established within 2 months of implementation | Sep/2023
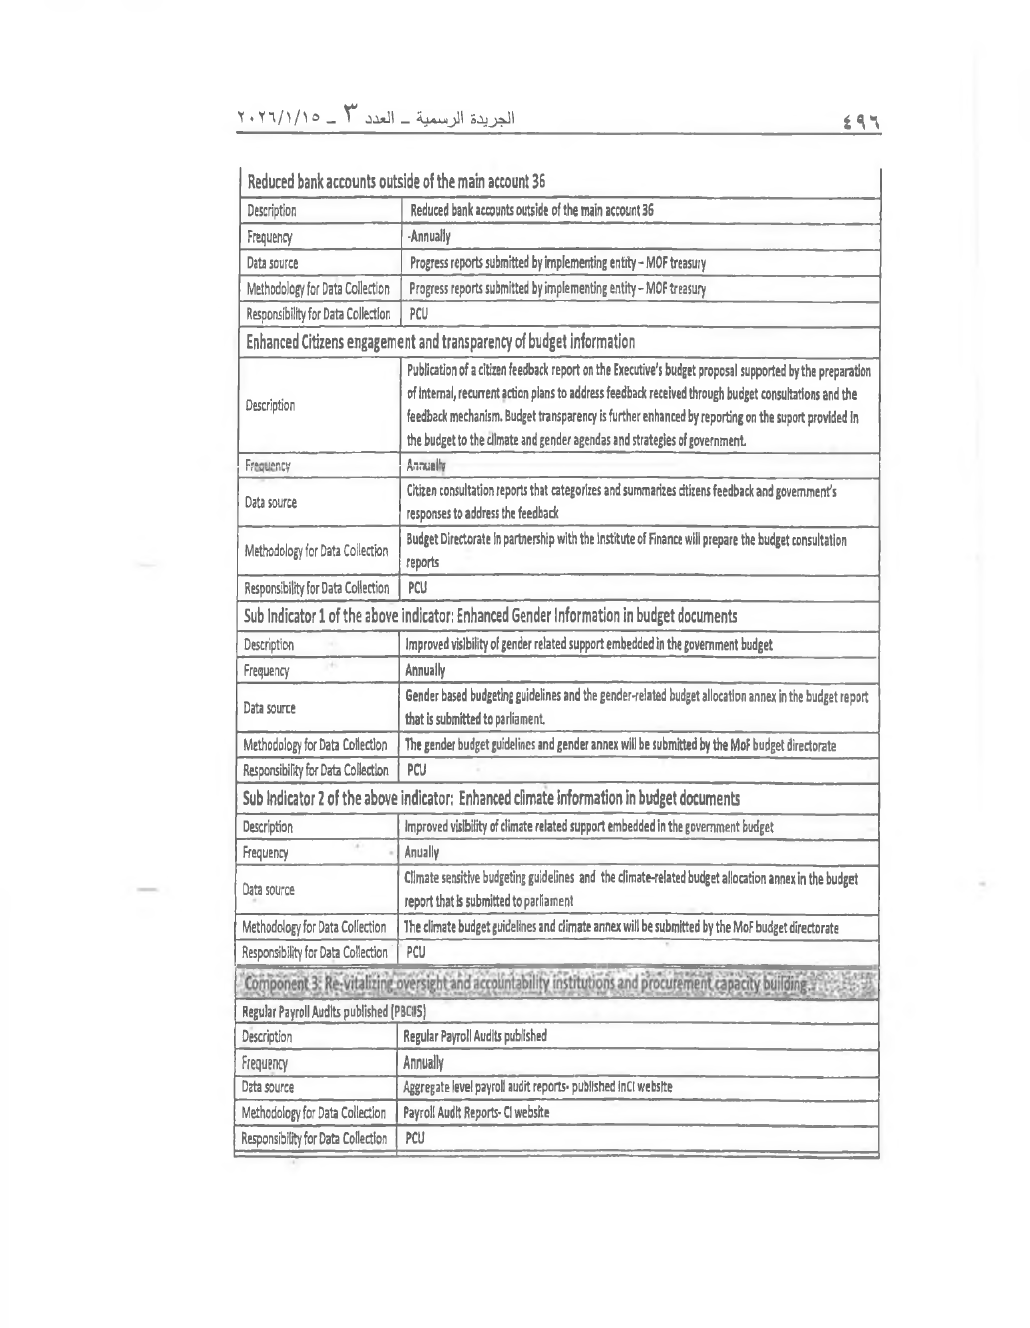
Revised / Revise Enhanced citizens engagement and transparency of budget information (Text) | Citizen budget and executive's budget proposals published | Sep/2023
… / الجريدة الرسمية ـ العدد ٣ ـ ٢٠٢٦/١/١٥
| | | | | | | parallel with the budget's enactment
| Enhanced Gender Information in budget documents (Text) | 0 | | same as baseline | | same as baseline | | Annex on gender based budget allocations included in the FY+1 budget report
| Enhanced climate information in budget documents (Text) | NA | | No climate information in 2024 budget | | No climate information in 2024 budget | | Annex on climate based budget allocations included in the FY+1 budget report
| 3: Revitalizing oversight and accountability institutions and procurement capacity building Revised
Indicator Name | Baseline | Actual (Previous) | Actual (Current) | Closing Period
| Result | Month/Year | Result | Date | Result | Date | Result | Month/Year
Revise Regular Payroll Audits completed and published (Text) PBC | No payroll audit carried out and published | Sep/2023 | same as baseline | 31-Mar-2025 | same as baseline | 31-Mar-2025 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan plan (b) An aggregate level payroll audit report published for the relevant 6 months | Dec/2028
Performance-based Conditions (PBC)
PBC Name | Baseline | Actual (Current) | End Target
| | Result | Date
… / | ٥٢٧
02-Jun-2025 | (a) At least 75 percent of the identified large taxpayers timely file declarations and pay taxes. (b) Number of large taxpayers audited are at least 3% of all large taxpayers falling under the new eligibility criteria | / … 100,000.00
02-Jun-2025 | (a) At least 45 risk-based post clearance audits conducted for customs clearances through Beirut port are conducted | / … 100,000.00
02-Jun-2025 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY (b) Finalize / (b)Finalize draft FY+1 budget within 8 months of the relevant FY | / … 300,000.00
15-May-2024 | (a) Final accounts 2027 finalized by MoF (b) Clearance of backlog: Audit reports 2017-2018 (c) Audit report 2027 published d)- Reporting on the status of recommendations. from previous audit reports | / … 80,000.00
02-Jun-2025 | (a) Quarter / (a)Quarter 2 and 3 Fiscal Performance Report for current
(a) N/A - Large taxpayers as per new criteria are not ascertained to determine the % of filing (b) 0 risk-based audits | same as baseline
0.00 |
No risk-based audits carried out | same as baseline
0.00 |
0 | same as baseline
0.00 |
FY 2020 audit report | same as baseline
0.00 |
Fiscal Performance Report of 2021 completed | same as baseline
Revise 1.A Increase in the timely filing of tax declarations by large tax payers and increase in number of audits of large tax payers (of Income Tax and VAT) (Text) | Value / …
Total Allocation:500,000.00 | … / Value | Allocated Amount
Revise 1.B Increase in the number of risk-based desk and premise post clearance audits for Port of Beirut customs (Text) | Value / …
Total Allocation:500,000.00 | … / Value | Allocated Amount
Revise 2 Timely submission of the budget to the council of ministers (CoM) (Text) | Value / …
Total Allocation:2,000,000.00 | … / Value | Allocated Amount
Revise 3.A Timely audit report published (Yes/No) | Value / …
Total Allocation:500,000.00 | … / Value | Allocated Amount
| Value
… / | | year is published within 20 days end of period )
… / | | 50,000.00
… / | 02-Jun-2025 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months
… / | | 200,000.00
Review / Revise 3.B Fiscal Performance Report published (Text) Total Allocation:500,000.00
| | | | Allocated Amount | 0.00
Review / | Revise 5 Regular Payroll Audits completed and published (Text) Total Allocation:1,000,000.00 | Value | No payroll audit carried out and published | same as baseline
| Allocated Amount | 0.00
… / | ٥٢٩
Period 2 | Period 3 | Period 4 | Period 5 | Period 6
(a) VAT and Income Tax LTO (s) have identified large taxpayers using the new criteria for review of declarations. b- Number of large taxpayers audited is at least 3% of all large taxpayers falling under the new eligibility criteria. | (a) At least 30 percent of the identified large taxpayers file timely declarations and pay taxes. (b) Number of large taxpayers audited is at least 3% of all large taxpayers falling under the new eligibilty / eligibility criteria. | (a) At least 40 percent of the identified large taxpayers timely file declarations and pay taxes. (b) Number of large taxpayers audited is at least 3% of all large taxpayers falling under the new eligibility criteria. | (a ) At least 60 percent of the identified large taxpayers timely file declarations and pay taxes. (b) Number of large taxpayers audited is at least 3% of all large taxpayers falling under the new eligibility criteria. | (a) At least 75 percent of the identified large taxpayers timely file declarations and pay taxes. (b) Number of large taxpayers audited is at least 3% of all large taxpayers falling under the new eligibility criteria.
100,000.00 | 50,000.00 | 50,000.00 | 100,000.00 | 100,000.00
(a) At least 20 risk-based post clearance audits of customs clearances through Beirut port are conducted | (a) At least 30 risk-based post clearance audits conducted for customs clearances through Beirut port are conducted | (a) At least 35 cases of risk-based post clearance audits conducted for customs clearances through Beirut port. | (a) At least 40 risk-based post clearance audits conducted for customs clearances through Beirut port are conducted | (a) At least 45 risk-based post clearance audits conducted for customs clearances through Beirut port are conducted
100,000.00 | 50,000.00 | 50,000.00 | 100,000.00 | 100,000.00
PBC
No. | Indicator | Baseline | Actual Current | Period 1
… / 1.a | Increase in the timely filing of tax declarations by large tax payers and Increase / increase in number of audits of large tax payers (of Income Tax and VAT) (Text) Allocation: … / 500,000.00 | (a) N/A - Large taxpayers as per new criteria are not ascertained to determine the % of filing (b) 0 risk-based audits | same as baseline Not Due | (a) New eligibility criteria adopted
1.a / … | 500,000.00 / … | 0.00 | 15/May/2024 | 100,000.00
… / 1.b | Increase in the number of risk-based desk and premise post clearance audits for Port … / of Beirut customs (Text) | No risk-based audits carried out | same as baseline Not Due | (a) Risked based selection system approved by the competent authorit / authority and adopted by the MoF for implementation
1.b / … | of Beirut customs (Text) / … | 0.00 | 15/May/2024 | 100,000.00
… / الجريدة الرسمية - العدد ٣ - ١٥/١/٢٠٢٦
| Allocation: 500,000.00 | | | | | | | | | Timely submission of the budget to the council of ministers (CoM) (Text) Allocation: … / 2,000,000.00 | … / Allocation: 500,000.00 0.00 | 0 | - 15/May/2024 | same as baseline Not Due … / 200,000.00 | (a) Updated MTFF for 3 years (b) Issue budget call circulars within 4 months of FY … / 300,000.00 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY (b) Finalized draft FY +1 budget within 8 months of the relevant FY(c) Submission of 2027 budget to CoM within 8 months of the relevant FY … / 200,000.00 | (a) Updated MTFF for 3 years (b) Issued budget call circulars with indicative ceilings within 4 months of the relevant FY … / 500,000.00 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY (b) Finalized draft FY +1 budget within 8 months of the relevant FY (c) Submission of 2028 budget to CoM within 8 months of the relevant FY … / 500,000.00 | (a) Updated MTFF for 3 years (b) Issued budget call circulars with indicative ceilings within 4 months of the relevant FY (c) Submission of 2029 budget to CoM within 8 months of the relevant FY … / 300,000.00 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY (b) Finalize / (b)Finalize draft FY+1 budget within 8 months of the relevant FY
2 | 2,000,000.00 | 0.00 | 15/May/2024 | 200,000.00 | 300,000.00 | 200,000.00 | 500,000.00 | 500,000.00 | 300,000.00 / …
| / 3.a Timely audit report published (Yes/No) Allocation: … / 500,000.00 0.00 | FY 2020 audit report … / 15/May/2024 | same as baseline Not Due … / 90,000.00 | (a) Final accounts 2021 finalized by MoF (b) Clearance of backlog: Audit reports 2005-2006 … / (c) Audit report 2021 published (d) Reporting on the status of recommendation. / recommendations, from previous audit reports … / 90,000.00 | (a) Final accounts 2022 finalized by MoF (b) Clearance of backlog: Audit reports 2007-2008 (c) Audit report 2022 published (d) Reporting on the status of recommendations, from previous audit reports … / 80,000.00 | (a) Final accounts 2023 finalized by MoF (b) Clearance of backlog: Audit reports 2009-2010 (c) Audit report 2023 published (d)- Reporting on the status of recommendations, from previous audit reports … / 80,000.00 | (a) Final accounts 2024 finalized by MoF (b) Clearance of backlog: Audit reports 2011-2012 (c) Audit report 2024 published (d)- Reporting on the status of recommendations, from previous audit reports … / 80,000.00 | (a) Final accounts 2025-2026 finalized by MoF (b) Clearance of backlog: Audit reports 2013-2016 (c) Audit report 2025-2026 published (d) Reporting on the status of recommendations, from previous audit reports … / 80,000.00 | (a) Final accounts 2027 finalized by MoF (b) Clearance of backlog: Audit reports 2017-2018 (c) Audit report 2027 published d)- Reporting on the status of recommendations, from previous audit reports
3. | 500,000.00 | 0.00 | 15/May/2024 | 90,000.00 | 90,000.00 | 80,000.00 | 80,000.00 | 80,000.00 | 80,000.00 ٥٣١ / …
Fiscal Performance Report published (Text) | Fiscal Performance Report of 2021 completed | same as baseline Not Due | (a) Fiscal Performance Report of 2022 finalized | (a)The first 6 months Fiscal Performance Report for current year is published / Published within 60 days end of period (b) Fiscal / fiscal performance report of the first 6 months of 2025 finalized | a) Year-end Fiscal performance Report of previous year is published within 60 days end of period (b) Fiscal Performance Report of the last 6 months of 2026 finalized | (a) The first 6 months Fiscal Performance Report for current year is published within 60 days end of period | (a) Year-end Fiscal Performance Report of previous year is published within 45 days (b) Quarter 1 Fiscal Performance Report for current year is published within 45 days end of period | (a)Quarter 2 and 3 Fiscal Performance Report for current year is published within 20 days end of period )
Allocation: / …
3.b | … / 4 Allocation: 500,000.00 | 0.00 | 15/May/2024 | 100,000.00 | 100,000.00 | 100,000.00 | 50,000.00 | 100,000.00 | 50,000.00 / …
Regular Payroll Audits completed and published (Text) … / Allocation: | … / 1,000,000.00 0.00 | No payroll audit carried out and published | … / 0.00 15/May/2024 | same as baseline Not Due | … / 15/May/2024 100,000.00 | (a) Preparation of audit plan | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months / 150,000.00 100,000.00 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months | … / 150,000.00 100,000.00 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months | … / 150,000.00 50,000.00 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months | … / 150,000.00 100,000.00 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months | … / 200,000.00 50,000.00 | (a) Payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan (b) An aggregate level payroll audit report published for the relevant 6 months
Allocation: 4 / … | 1,000,000.00 | 0.00 | 15/May/2024 | 150,000.00 | 150,000.00 | 150,000.00 | 150,000.00 | / … 200,000.00 | 200,000.00 / …
133 Agreement Between the UN and the IBRD, entered into force, 1946, 16 U.N.T.S. 346. [Hereinafter UN-World Bank Agreement].
134 Art. 8 § 4 of the UN-World Bank Agreement provides, UN agrees that in the interpretation of Art. 17, para. 3 of the Charter, which provides that the General Assembly shall examine the administrative budgets of the specialized agencies with a view to making recommendations to those agencies, it will take into consideration that theBank does not rely for its annual budget upon its members, and that the appropriate authorities of the Bank enjoy full autonomy in deciding the form and content of the Bank’s budget.
135 Art. 2 § 1 of the World Bank Articles of Agreement provides that membership shall be open in accordance with such terms “as may be prescribed by the Bank.” Art. 2 S. 2(b) provides that the capital stock of the Bank may be increased when the Bank deems it advisable by a three-fourths majority of the total voting power. Art. 2 S. 3(b) provides that the Bank shall prescribe rules laying down the conditions under which members may subscribe shares of the authorized capital stock of the Bank in addition to their minimum subscriptions.
136 “The rights and obligations of the Bank and the Borrower under the Loan Agreement and the Bonds shall be valid and enforceable in accordance with their terms notwithstanding the law of any state, or political division, thereof, to the contrary.” Skogly, supra note 11, at 42.
وحيث انه بالنظر لتوافر كافة الشروط المفترض توافرها بالمعاهدة الدولية تكون اتفاقية القرض الحاضرة معاهدة دولية بمفهوم المادة 52 و65 من الدستور وليس مجرد مذكرة تفاهم؛
2- آلية الابرام
وحيث انه يستفاد من المادة 52 من الدستور انه " يتولى رئيس الجمهورية المفاوضة في عقد المعاهدات الدولية وابرامها بالاتفاق مع رئيس الحكومة. ولا تصبح مبرمة الا بعد موافقة مجلس الوزراء. وتطلع الحكومة مجلس النواب عليها حينما تمكنها من ذلك مصلحة البلاد وسلامة الدولة. اما المعاهدات التي تنطوي على شروط تتعلق بمالية الدولة والمعاهدات التجارية وسائر المعاهدات التي لا يجوز فسخها سنة فسنة، فلا يمكن ابرامها الا بعد موافقة مجلس النواب"،
H.E. Youssef El Khalil
Minister of Finance
Ministry of Finance
Beirut, Lebanon
(Transmission by email: [email protected])
Subject: Lebanon Fiscal Management Project
Notification of Board Approval
Excellency,
We are pleased to inform you that the Board of Executive Directors of the International Bank for Reconstruction and Development and the International Development Association (the Bank) has approved on February 14, 2024, a loan in the amount of twenty eight million and five hundred thousand United States Dollars (US$28,500,000), in addition to a grant from the Lebanon Financing Facility (LFF) for five million and five hundred thousand United States Dollars (US$5,500,000) for the Lebanon Fiscal Management Project. The development objective of the Fiscal Management Project is to restore the basic functions for domestic revenue mobilization and accountable allocation and use of public resources.
We look forward to an early signing of the Loan Agreement and Grant Agreement, and swift ratification of the loan by the Lebanese Parliament.
Sincerely yours,
Jean-Christophe Carret
Country Director, Middle East Department
Middle East and North Africa Region
cc: Mr. Abdulaziz Ebrahim Al Mulla, Executive Director, World Bank Group
Ms. Wafaa Charafeddine, Advisor to the Executive Director, World Bank Group
٤,٠٢. يتألف الحدث الإضافي للتسريع من الآتي، أي حدوث الحالة المحددة في القسم ٤,٠١ من هذه الاتفاقية واستمرارها لمدة ستين (٦٠) يوماً بعد تقديم إشعار بالحالة من قبل البنك إلى المقترض.
المادة V – التفعيل؛ الإنهاء
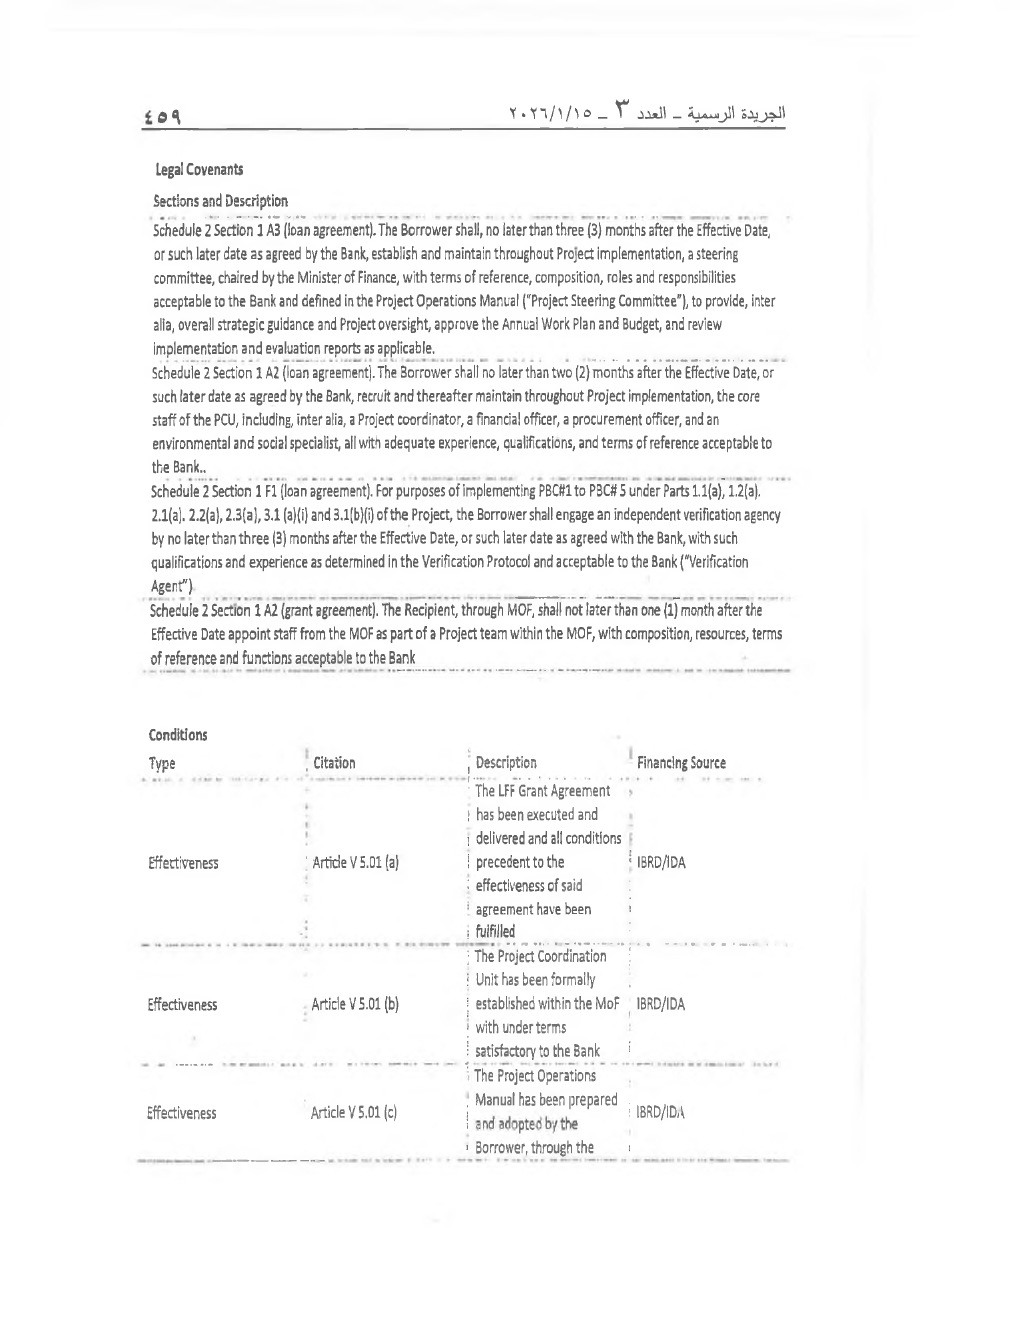
٥,٠١. تتألف الشروط الإضافية للتفعيل من الآتي:
(أ) تم تنفيذ اتفاقية منحة الصندوق الائتماني المخصص للبنان وتسليمها، كما تمت تلبية كافة الشروط السابقة لتفعيل الاتفاقية المذكورة ؛
(ب) تم تأسيس وحدة تنسيق المشروع بصورة رسمية داخل وزارة المالية في ظل شروط مُرضية بالنسبة إلى البنك؛ و
(ج) تم إعداد دليل عمليات المشروع واعتماده من قبل المقترض من خلال وزارة المالية، وفقاً لشروط مُرضية بالنسبة إلى البنك.
٥,٠٢. الموعد النهائي لنفاذ العقد هو مئة وثمانين يوماً (١٨٠) بعد تاريخ التوقيع.
٥,٠٣. لأغراض القسم ٩,٠٥ (ب) من الشروط العامة، التاريخ الذي تنتهي فيه التزامات المقترض بموجب هذه الاتفاقية (بخلاف تلك التي تنص على التزامات الدفع) هو عشرين (٢٠) سنة بعد تاريخ التوقيع.
المادة VI – الممثلون؛ العناوين
٦,٠١. الممثل عن المقترض هو الوزير المسؤول عن المالية.
٦,٠٢. لأغراض القسم ١٠,٠١ من الشروط العامة:
(أ) عنوان المقترض هو:
وزارة المالية
The World Bank
… / | Bourie House 119, 5th Floor | Tel : (961-1) 963 300 INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT
… / | Abdallah Bayhum Street | Fax: (961-1) 963 455 INTERNATIONAL DEVELOPMENT ASSOCIATION
… / | Marfaa, Solidere | Email: [email protected] Jean-Christophe Carret
Country / | P.O. Box 11-8577 Division Director, Middle East Department
… / | Beirut, Lebanon Middle East & North Africa Region
Bourie House 119. 5th Floor Abdallah Bayhum Street Marfaa. Solidere P.O. Box 11-8577 Beirut, Lebanon Tel: (961-1) 963 300 Fax: (961-1) 963 433 Email: [email protected] / …
Date: June 17, 2025
H.E. Yassine Jaber
Minister of Finance
Ministry of Finance
Rue de L'Etoile
Parallèle à Riad Solh
Beirut
Lebanese Republic
Re: Fiscal Management Project
(Loan No. 9644-LB)
Amendment to the Loan Agreement
Excellency:
We refer to the Loan Agreement between the Lebanese Republic (the Borrower) and the International Bank for Reconstruction and Development (the Bank) dated September 27, 2024 (the Loan Agreement) for the above-mentioned Project. Please note that the capitalized terms used in this letter (Amendment Letter) and not otherwise defined herein have the meaning ascribed to them in the Loan Agreement.
We also refer to your letter dated February 26, 2025, requesting specific amendments to the Loan Agreement. We are pleased to inform you that the Bank accedes to your request and proposes, through this Amendment Letter, to amend the Loan Agreement as follows:
1. Section 2.01 under Article II to the Loan Agreement is hereby amended to read as follows:
“2.01. The Bank agrees to lend to the Borrower the amount of twenty-eight million and five hundred thousand Dollars ($28,500,000), as such amount may be converted from time to time through a Currency Conversion (“Loan”), to assist in financing Part 1.1, Part 1.2, Part 1.3(b), Part 1.3(c), Part 2.1, Part 2.2, Part 2.4 (b), Part 2.4 (c), Part 2.4 (d), Part 2.4 (e), Part 3, Part 4 and Part 5 of the project described in Schedule 1 to this Agreement (“Project”).”
2. Article IV in the Loan Agreement is hereby deleted. Consequently, the remaining Articles are renumbered to keep the numerical order.
3. The word “and” at the end of paragraph 1.2(a) under Part 1 of Schedule 1 to the Loan Agreement is hereby deleted.
4. Paragraph 1.3 under Part 1 of Schedule 1 to the Loan Agreement is hereby amended to read as follows:
“1.3 Restoring and modernizing revenue management ICT systems through, among others:
(a) carrying out maintenance and upgrading of hardware, software, and the ICT capacity of the tax and customs ICT systems;
(b) integrating revenue and customs systems to enhance data sharing for critical decision making and enhancing the review functions; and
(c) developing an integrated tax administration system (ITAS).”
5. Paragraph 2.1 under Part 2 of Schedule 1 to the Loan Agreement is hereby amended to read as follows:
“2.1 Strengthening budget preparation through, among others:
(a) technical assistance to achieve the timely preparation of the annual budget, underscored by a sound macro fiscal framework which supports the crisis response and recovery;
(b) Training and capacity building, and technical assistance to staff for, inter alia, the review of the Budget Classification and Chart of Accounts (BC-CoA), the updating of the macro fiscal framework, preparation of budget ceilings, enhancing of the macro fiscal framework budgeting methodologies, preparation of a fiscal risk analysis, preparation of budget policy statement setting the foundations for gender-responsive and climate sensitive budgeting and enhancing citizen engagement; and
(c) provision of solar panels for electricity generation.”
6. Paragraph 2.2(a) under Part 2 of Schedule 1 to the Loan Agreement is hereby amended to read as foliows: / follows:
“(a) technical assistance to: (i) regularize the generation of budget execution reports, annual financial statements, and bank reconciliations for closely monitoring budget execution and fiscal risks; and (ii) lay the foundation of a treasury single account (TSA) framework to improve liquidity management and availability of real-time information on budget execution (including revenues and expenditures);”
7. Paragraph 2.3 under Part 2 of Schedule 1 to the Loan Agreement is hereby deleted and left “intentionally blank”.”
8. Paragraph 2.4 under Part 2 of Schedule 1 to the Loan Agreement is hereby amended to read as follows:
“2.4 Restoring cross-cutting Information and Communication Technology (ICT) functionalities through, inter alia:
(a) supporting critical maintenance and upgrading of hardware, software, and the ICT capacity of the budget and expenditure management systems;
(b) provision of critical IT equipment and related software and licenses to provide cross cutting support to expenditure management;
(c) integrating expenditure and revenue systems to enhance data sharing for critical decision making on expenditure and revenue management;
(d) supporting an ICT strategy, a business process reengineering, and a post implementation review; and
(e) developing and implementing a modern integrated financial management system (IFMIS).
9. Part 3 under Schedule 1 to the Loan Agreement is hereby amended to read as follows:
“Part 3: Re-vitalizing Oversight and Accountability Institutions and public financial management and procurement capacity building.
Provision of support to help enhance (a) the role of oversight, audit and capacity of the Court of Accounts (CoA), Central Inspection (CI), the Public Procurement Authority and other selected public procurement institutions and expand their engagement with the citizens; and (b) the role of capacity building of the Institute of Finance, and Training of the Recipient’s civil servants, including through:
3.1 Increasing core functions capacity of:
(a) the CoA through among others: (i) operational support and technical assistance to expedite the clearance of the backlog of statutory audits and maintain timely audits thereafter, carry out audits of automated environments and support citizen engagement activities on audit recommendations; and (ii) Training and capacity building to CoA staff;
(b) (i) the CI through among others operational support to carry out in-depth payroll audits; and (ii) technical assistance to carry out payroll audits and (iii) provision of solar panels for electricity generation; (c) interconnectivity of CoA and CI to carry out their audits and inspections through the establishment of connectivity platforms; and
(c) technical assistance, Training and development of e-learning platforms and e-modules to build the capacity and skills of civil servants on public financial management and public procurement.
3.2 Supporting (a) the enhancement of capacity building functions of the Institute of Finance; and (b) the professionalization of public procurement practitioners through, inter alia, technical assistance and Training.
3.3 Provision of solar panels for electricity generation.”
10. Paragraph 1(c) under Section I.B of Schedule 2 to the Loan Agreement is hereby amended to read as follows:
“(c) detailed description of mechanisms of the Eligible Expenditures Program under the Project for PBCs, including the modalities for the verification of achievements of PBCs;”
11. Paragraph 1 under Section I.F of Schedule 2 to the Loan Agreement is hereby amended to read as follows:
“1. For purposes of implementing PBC#1 to PBC#4 under Parts 1.1(a), 1.2(a). 2.1(a). 2.2(a), 3.1 (a)(i) and 3.1(b)(i) of the Project, the Borrower shall engage an independent verification agency by no later than three (3) months after the Effective Date, or such later date as agreed with the Bank, with such qualifications
ication Protocol and acceptable to the
Agreement is hereby amended to read
Percentage of Expenditures to be financed (inclusive of Taxes)
100% of each PBC Amount set out in Schedule 4 (or such lesser percentage as represents the total Eligible Expenditures paid by the Borrower under the Eligible Expenditures Program as of the date of withdrawal)
100%
Amount payable pursuant to Section 2.03 of this Agreement in accordance with Section 2.07 (b) of the General Conditions
Amount due pursuant to Section 4.05 (c) of the General Conditions
100%
ule 2 to the Loan Agreement is hereby
Date, except that withdrawals up to an may be made for payments made prior Eligible Expenditures; or” / or"
and experience as determined in the Verifi Bank (“Verification Agent”).”
12. The table in Section III.A of Schedule 2 to the Loan as follows:
Category | Amount of the Loan Allocated (expressed in USD)
(1) Eligible Expenditures Program under Parts 1.1(a), 1.2(a). 2.1(a). 2.2(a), 2.3(a) and 3.1 (a)(i) of the Project | 5,000,000
(2) Goods, works, non-consulting services, consulting services, Operating Costs, and Training under the Project (except for expenditures under Category (1) and Parts 1.3(a) and 2.4(a) of the Project) | 23,428,750
(3) Front-end Fee | 71,250
(4) Interest Rate Cap or Interest Rate Collar premium | 0
(5) Emergency Expenditures under Part 5 of the Project | 0
TOTAL AMOUNT | 28,500,000
13. Paragraph 1(a) under Section III.B of under Schedu amended to read as follows:
“(a) for payments made prior to the Signature D aggregate amount not to exceed $2,000,000 to this date but on or after July 1, 2024, for
14. Paragraph 1(b) under Section III.B of Schedule 2 to the Loan Agreement is hereby amended to read as follows:
"(b) / “(b) for payments under Category (1) unless the Bank has received satisfactory evidence that (i) the PBCs set forth in Schedule 4 to this Agreement for which payment is requested have been met and verified in accordance with the Verification Protocol and the POM to be verified by the Verification Agent; and (ii) payments for the Eligible Expenditures Program have been made in accordance and in compliance with the procedures set forth in the POM." / POM.”
15. Section III.B.6 of Schedule 2 to the Loan Agreement is hereby amended to read as follows:
"6. The Closing Date is December 31, 2028." / 2028.”
16. Schedule 4 to the Loan Agreement is hereby deleted and replaced to read as set forth in the attachment to this Amendment Letter.
17. The definitions included in paragraphs 1, 13, and 39 are hereby deleted from the Appendix to the Loan Agreement, and, as a result, the definitions are renumbered accordingly.
18. The definition included in paragraph 15 in the Appendix to the Loan Agreement is hereby amended to read as follows:
"15. "Eligible / “15. “Eligible Expenditures Program" / Program” means the Goods, works, non-consulting services, and consulting services, Operating Costs, Training incurred by the Borrower for the implementation of the Project." / Project.”
19. The following definitions are hereby added to the Appendix to the Loan Agreement in alphabetical order; and, as a result, the remaining definitions are renumbered accordingly, as follows:
""BC-CoA" / ““BC-CoA” means Budget Classification and Chart of Accounts,"" ""IFMIS" / Accounts.”” ““IFMIS” means integrated public financial management information system." ""ITAS" / system.” ““ITAS” means integrated tax administration system." ""TSA" / system.” ““TSA” means treasury single account." / account.”
All other provisions of the Loan Agreement, except as amended through this Amendment Letter, shall remain in full force and effect.
Please confirm your agreement with the foregoing amendments, on behalf of the Borrower, by signing and dating this Amendment Letter in the space provided below. This Amendment Letter shall be executed in two counterparts, each of which shall be an original and one of which shall be returned to us.
The provisions set forth in this Amendment Letter shall become effective upon receipt by the Bank of satisfactory evidence that the following conditions have been satisfied:
(i) receipt of one fully executed original of this Amendment Letter;
(ii) the Project Operations Manual has been updated and adopted by the Borrower, through MOF, in a manner satisfactory to the Bank; and
(iii) the conditions of Effectiveness as noted in Article IV of the Loan Agreement have been fulfilled.
Yours sincerely,
INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT
Jean-Christophe Carret
… / Jean-Christophe Carret Division Director, Middle East Department
Middle East & North Africa Region
AGREED:
LEBANESE REPUBLIC
By
… / Yassine Jaber Authorized Representative
Name: Yassine Jaber
Title: Minister of Finance
Date: 05-Jul-2025 / 08-Jul-2025
Attachment
“SCHEDULE 4
Performance-Based Conditions under the Project
The following table specifies the Performance-Based Conditions (PBCs) and the allocation of the amounts of the Loan to each PBC under Category (1):
Performance Based Conditions | Description of achievement 6 months following Effective Date … / Amount of financing (in USD) | Description of achievement 12 months following Effective Date … / Amount of financing (in USD) | Description of achievement 18 months following Effective Date … / Amount of financing (in USD) | Description of achievement 24 months following Effective Date … / Amount of financing (in USD) | Description of achievement 36 months following Effective Date … / Amount of financing (in USD) | Description of achievement 48 months following Effective Date
| Amount of financing (in USD) | Amount of financing (in USD) | Amount of financing (in USD) | Amount of financing (in USD) | Amount of financing (in USD) | Amount of financing (in USD) / …
1a. (i) Increase in the timely filing of tax declarations by large taxpayers 250,000 | New Eligibility Criteria adopted by the MOF 50,000 | VAT and Income Tax LTO(s) / LTO (s) have identified large taxpayers using the new criteria for review of declarations 50,000 | At least 30 % of the identified large taxpayers timely file declarations and pay taxes; and 25,000 | At least 40 % of the identified large taxpayers timely file declarations and pay taxes; and 25,000 | At least 60 % of the identified large taxpayers timely file declarations and pay taxes; and 50,000 | At least 75 % of the identified large taxpayers timely file declarations and pay taxes; and
250,000 | 50,000 | 50,000 | 25,000 | 25,000 | 50,000 | 50,000
1a. (ii) Increase in the number of audits of large tax payers (of Income Tax and VAT) 250,000 | 50,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria. 50,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria. 25,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria. 25,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria. 50,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria.
250,000 | 50,000 | 50,000 | 25,000 | 25,000 | 50,000 | 50,000
30 for ort are | At least 35 cases of risk-based post clearance audits for customs clearances through Port of Beirut are conducted. … / . 50,000 | At least 40 risk-based post clearance audits for customs clearances through Port of Beirut are conducted. … / 100,000 | At least 45 risk-based post clearance audits for customs clearances through Port of Beirut port are conducted.
50,000 | / … 100,000 | 100,000 / …
ed 3 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY … / 150,000 | (a) Updated MTFF for 3 years … / 150,000 | (b) Completed FY+1 budget consultations within 7 months of the relevant FY
150,000 | 150,000 | 150,000 / …
all 4 of nt | (b)Finalized draft FY +1 budget by within 8 months of the relevant FY … / 150,000 | (c) Issued budget call circulars with indicative ceilings within 4 months of the relevant FY … / 150,000 | (c) Finalized draft FY +1 budget by within 8 months of the relevant FY
150,000 | 150,000 | 150,000 / …
(c)Submission of 2028 budget to CoM within 8 months of the relevant FY … / 200,000 | (e)Submission of 2029 budget to CoM within 8 months of the relevant FY
200,000 | -200,000 / …
1b. Increase in the number of risk-based desk and premise post clearance audits for Port of Beirut customs … / 500,000 | Risked based selection system approved by the competent authority and adopted by the MOF for implementatio n. … / 100,000 | At least 20 risk-based post clearance audits of customs clearances through Port of Beirut are conducted. … / 100,000 | At least risk-based post clearance audits customs clearances through P of Beirut … / a conducted
500,000 | 100,000 | 100,000 | / … 50,000
2.(i) Timely submission of the Budget to the Council of Ministers … / 750,000 | (a) Updated MTFF for 3 years submitted … / 100,000 | (a) Completed FY+1 budget consultations by within 7 months of the relevant FY … / 100,000 | (a) Updat MTFF for years
750,000 | / … 100,000 | 100,000 | 100,000 / …
2.(ii) … / 750,000 | (b) Issued budget call circulars within 4 months of the relevant FY … / 100,000 | (b)Finalized draft FY +1) budget by within 8 months of the relevant FY … / 100,000 | (b)Issued budget c circulars with indicative ceilings within months the releva FY
750,000 | / … 100,000 | 100,000 | 100,000 / …
2.(iii) … / 500,000 | | (c)Submissio n of 2027 budget to CoM within 8 months of the relevant FY
500,000 | | 100,000
|
(a) Final accounts 2025-2026 finalized by MOF 25.000 | (a) Final accounts 2027 finalized by MOF 25.000
(b) Clearance of backlog. Audit reports 2013-2016 15.000 | (b) Clearance of backlog: Audit reports 2017-2018 15,000
(c) Audit report 2025-2026 published 25.000 | (c) Audit report 2027 published 25.000
(d) Reporting on the status of recommendati ons. from previous audit reports 15.000 | (d) Reporting on the status of recommendati ons. from previous audit reports 15,000
(a) Year-end Fiscal performance Report of previous FY is published within 45 days 50.000 | Quarter 2 and 3 Fiscal Performance Report for current FY is published within 20 days end of period 50.000
(b) Quarter 1 Fiscal Performance Report for current FY is published within 45 days end of period 50,000
| (a) payroll audis / audits of Lebanon civilian public administration | (a) payroll audits of Lebanon civilian public administration
3a.(i) Timely audit report published 150.000 | (a) final accounts 2021 finalized by MOF; 25.000 | (a) final accounts 2022 finalized by MOF 25.000 | (a) final accounts 2023 finalized by MOF 25.000 | (a) Final accounts 2024 finalized by MOF 25.000
3a.(ii) 100,000 | (b) Clearance of backlog: Audit reports 2005-2006 20,000 | (b) Clearance of backlog: Audit reports 2007-2008 20,000 | (b) Clearance of backlog: Audit reports 2009-2010 15.000 | (b) Clearance of backlog: Audit reports 2011-2012 15,000
3a.(iii) 150.000 | (c) Audit report 2021 published 25.000 | (c) Audit report 2022 published 25,000 | (c) Audit report 2023 published 25.000 | (c) Audit report 2024 published 25.000
3a.(iv) 100.000 | (d) Reporting on the status of recommendati ons. from previous audit reports 20.000 | (d) Reporting on the status of recommenda tions. from previous audit reports 20,000 | (d)- Reporting on the status of recommenda tions. from previous audit reports 15,000 | (d)- Reporting on the status of recommendati ons. from previous audit reports 15,000
3b.(i) Fiscal Performance Report published 350.000 | Fiscal Performance Report of 2022 finalized 100,000 | (a) The first 6 months Fiscal Performance Report for current FY is published within 60 days end of period; 50,000 | (a) Year-end Fiscal performance Report of previous FY is published within 60 days end of period 50,000 | (a) The first 6 months Fiscal Performance Report for current FY is published within 60 days end of period 50,000
3b.(ii) 150,000 | 0 | (b) Fiscal Performance Report of the first 6 months of 2025 finalized 50,000 | (b) Fiscal Performance Report of the last 6 months of 2026 finalized 50,000
| 5.(i) Regular Payroll Audits completed | Preparation of audit plan | (a) payroll audits of Lebanon civilian public | (a) payroll audits of Lebanon civilian public | (a) payroll audits of Lebanon civilian public administration
LOAN NUMBER 9644-LB
Loan Agreement
(Fiscal Management Project)
between
LEBANESE REPUBLIC
and
INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT
LOAN NUMBER 9644-LB
LOAN AGREEMENT
AGREEMENT dated as of the Signature Date between the LEBANESE REPUBLIC ("Borrower") / (“Borrower”) and the INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT ("Bank"). / (“Bank”).
WHEREAS the Borrower and the Bank, in its capacity as the administrator of the Lebanon Financing Facility for Reform, Recovery and Reconstruction Multi-Donor Trust Fund (No. TF0C3381) intend to enter into a grant agreement for the purpose of providing a grant in an amount not to exceed five million five hundred thousand United States Dollars ($5,500,000) ("LFF Grant") / (“LFF Grant”) to the Recipient to assist in financing the Project, dated the same date as this Agreement ("LFF / (“LFF Grant Agreement"); / Agreement”); and funding from the Lebanon Financing Facility for Reform, Recovery and Reconstruction Multi-Donor Trust Fund was received by the Bank for purposes of providing co-financing to the Loan on terms and conditions set forth in the LFF Grant Agreement.
NOW THEREFORE, the Borrower and the Bank hereby agree as follows:
ARTICLE I — GENERAL CONDITIONS; DEFINITIONS
1.01. The General Conditions (as defined in the Appendix to this Agreement) apply to and form part of this Agreement.
1.02. Unless the context requires otherwise, the capitalized terms used in this Agreement have the meanings ascribed to them in the General Conditions or in the Appendix to this Agreement.
ARTICLE II — LOAN
2.01. The Bank agrees to lend to the Borrower the amount of twenty-eight million and five hundred thousand Dollars ($28,500,000), as such amount may be converted from time to time through a Currency Conversion ("Loan"), / (“Loan”), to assist in financing Part 1.1, Part 1.2, Part 1.3(b), Part 2.1, Part 2.2, Part 2.3, Part 2.4 (b), Part 2.4 (c), Part 2.4 (d), Part 3, Part 4 and Part 5 of the project described in Schedule 1 to this Agreement ("Project"). / (“Project”).
2.02. The Borrower may withdraw the proceeds of the Loan in accordance with Section III of Schedule 2 to this Agreement.
2.03. The Front-end Fee is one quarter of one percent (0.25%) of the Loan amount.
2.04. The Commitment Charge is one quarter of one percent (0.25%) per annum on the Unwithdrawn Loan Balance.
2.05. The interest rate is the Reference Rate plus the Variable Spread or such rate as may apply following a Conversion; subject to Section 3.02(e) of the General Conditions.
ساحة رياض الصلح
بيروت
الجمهورية اللبنانية؛ و
(ب) العنوان الالكتروني للمقترض هو:
البريد الالكتروني:
٦,٠٣. لأغراض القسم ١٠,٠١ من الشروط العامة:
(a) عنوان البنك هو:
البنك الدولي للإنشاء والتعمير
شارع 1818H، نورث ويست
العاصمة واشنطن ٢٠٤٣٣
الولايات المتحدة الأميركية؛ و
(ب) العنوان الالكتروني للبنك هو:
البريد الالكتروني:
[email protected]
أبرمت الاتفاقية اعتباراً من تاريخ التوقيع،
2.06. The Payment Dates are June 15 and December 15 in each year.
2.07. The principal amount of the Loan shall be repaid in accordance with Schedule 3 to this Agreement.
ARTICLE III — PROJECT
3.01. The Borrower declares its commitment to the objectives of the Project. To this end, the Borrower, through the Ministry of Finance (MOF), shall carry out the Project in accordance with the provisions of Article V of the General Conditions and Schedule 2 to this Agreement.
ARTICLE IV — REMEDIES OF THE BANK
4.01. The Additional Event of Suspension consists of the following, namely that the Regulatory Framework has been amended, suspended, abrogated, repealed or waived so as to affect materially and adversely, in the opinion of the Bank, the ability of the Borrower to perform any of its obligations under this Agreement.
4.02. The Additional Event of Acceleration consists of the following, namely that the event specified in Section 4.01 of this Agreement occurs and is continuing for a period of sixty (60)) days after notice of the event has been given by the Bank to the Borrower.
ARTICLE V — EFFECTIVENESS; TERMINATION
5.01. The Additional Conditions of Effectiveness consist of the following:
(a) The LFF Grant Agreement has been executed and delivered and all conditions precedent to the effectiveness of said agreement have been fulfilled;
(b) The Project Coordination Unit has been formally established within the MoF under terms satisfactory to the Bank; and
(c) The Project Operations Manual has been prepared and adopted by the Borrower, through the MoF, under terms satisfactory to the Bank.
5.02. The Effectiveness Deadline is the date one hundred and eighty days (180) days after the Signature Date.
5.03. For purposes of Section 9.05 (b) of the General Conditions, the date on which the obligations of the Borrower under this Agreement (other than those providing for payment obligations) shall terminate is twenty (20) years after the Signature Date.
ARTICLE VI — REPRESENTATIVE; ADDRESSES
6.01. The Borrower's / Borrower’s Representative is its minister in charge of finance.
For purposes of Section 10.01 of the General Conditions:
(a) the Borrower’s / Borrower's address is:
Ministry of Finance
Riad El-Solh Square
Beirut
Lebanese Republic; and
(b) the Borrower’s / Borrower's Electronic Address is:
Facsimile:
+961 1 642 762
For purposes of Section 10.01 of the General Conditions:
(a) the Bank’s / Bank's address is:
International Bank for Reconstruction and Development
1818 H Street, N.W.
Washington, D.C. 20433
United States of America; and
(b) the Bank’s / Bank's Electronic Address is:
E-mail:
[email protected]
AGREED as of the Signature Date.
LEBANESE REPUBLIC
By
… / Youssef El Khalil Authorized Representative
Name: Youssef El Khalil
Title: Minister of Finance
Date: 27-Sep-2024
INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT
By
… / Jean-Christophe Carret Authorized Representative
Name: Jean-Christophe Carret
Title: Country Director
Date: 15-Jul-2024
SCHEDULE 1
Project Description
The objective of the Project is to support the Borrower restore the basic functions for domestic revenue mobilization and accountable allocation and use of public resources.
The Project consists of the following parts:
Part 1: stabilizing domestic revenue administration.
Provision of support to critical revenue functions which are essential for increasing the collection of tax and non-tax revenues, including through:
1.1 Strengthening the Large Taxpayer Office and a taskforce for large debts through, inter alia,
(a) the provision of operational support to enhance tax compliance, including with regard to tax arrears recovery, and the implementation of a tax compliance plan;
(b) the provision of Training and capacity building of staff, on, inter alia, taxpayer education; and
(c) the provision of solar panels for electricity generation.
1.2 Restoring basic functions of Customs through, among others:
(a) the provision of operational support to ensure basic functioning of the customs administration in accordance with the Customs Law; and
(b) the provision of Training and capacity building of staff, technical assistance for supporting the preparation of a strategic plan; and
(c) the provision of solar panels for electricity generation.
1.3 Restoring revenue management ICT systems through, among others:
(a) carrying out maintenance and upgrading of hardware, software, and the ICT capacity of the tax and customs ICT systems; and
(b) integrating revenue and customs systems to enhance data sharing for critical decision making and enhancing the review functions.
Part 2: Restoring fiscal controls.
Provision of support to help re-establish critical macro fiscal planning, budgeting, payment processing and reporting pillars for allocating and utilizing resources to meet urgent fiscal control needs and set the foundation for recovery, including through:
2.1 Strengthening budget preparation through, among others:
(a) operational support to achieve the timely preparation of the annual budget, underscored by a sound macro fiscal framework which supports the crisis response and recovery;
(b) Training and capacity building, and technical assistance to staff for, inter alia, the updating of the macro fiscal framework, preparation of budget ceilings, enhancing of the macro fiscal framework budgeting methodologies, preparation of a fiscal
risk analysis, preparation of budget policy statement setting the foundations for gender-responsive and climate sensitive budgeting and enhancing citizen engagement; and
(c) provision of solar panels for electricity generation.
2.2 Regularizing fiscal reporting and end-year financial reporting through, inter alia:
(a) operational support to regularize the generation of budget execution reports, annual financial statements, and bank reconciliations for closely monitoring budget execution and fiscal risks; and
(b) Provision of capacity building and Training to relevant staff engaged in fiscal reporting and provision of related IT equipment,
(c) provision of solar panels for electricity generation.
2.3 Maintaining timely processing of public payment documentation and updating pension files through, inter alia:
(a) operational support for the timely review of public payment documentation, and the timely preparation, review and updates of pension files for efficient and effective payment function;
(b) Provision of capacity building and Training to relevant staff engaged in public payment documentation and pension file updating, and provision of related IT equipment; and
(c) provision of solar panels for electricity generation.
2.4 Restoring cross-cutting Information and Communication Technology (ICT) functionalities through, inter alia:
(a) supporting critical maintenance and upgrading of hardware, software, and the ICT capacity of the budget and expenditure management systems;
(b) provision of critical IT equipment and related software and licenses to provide cross cutting support to expenditure management;
(c) integrating expenditure and revenue systems to enhance data sharing for critical decision making on expenditure and revenue management; and
(d) supporting an ICT strategy, a business process review and a post implementation review.
Part 3: Re-vitalizing Oversight and Accountability Institutions and procurement capacity building.
Provision of support to help enhance (a) the role of oversight, audit and capacity of the Court of Accounts (CoA), Central Inspection (CI), the Public Procurement Authority and other selected public procurement institutions and expand their engagement with the citizens; and (b) the role of capacity building of the Institute of Finance, including through:
3.1 Increasing core functions capacity of:
(a) the CoA through among others: (i) operational support to expedite the clearance of the backlog of statutory audits and maintain timely audits thereafter, carry out
audits of automated environments and support citizen engagement activities on audit recommendations; and (ii) Training and capacity building to CoA staff;,
(b) . (i) the CI through among others operational support to carry out in-depth payroll audits; and (ii) technical assistance to carry out payroll audits and (iii) provision of solar panels for electricity generation; (c) interconnectivity of CoA and CI to carry out their audits and inspections through the establishment of connectivity platforms.
3.2 Supporting (a) the enhancement of capacity building functions of the Institute of Finance; and (b) the professionalization of public procurement practitioners through, inter alia, technical assistance and Training.
Part 4: Project Management
4.1 Project management
Supporting Project management and coordination; monitoring and evaluation; compliance with the environmental and social standards; capacity building on gender sensitization for Project implementation purposes; fiduciary administration, internal controls, and audits; third-party monitoring, communication and outreach, and the establishment and maintenance of a Grievance Mechanism (GM) and a citizen's engagement mechanism.
4.2 PBC verification and audit support
Providing technical assistance for the review and verification of results associated with Performance-Based Conditions, and for the support of financial audit required for Project fiduciary oversight.
Part 5: Contingent Emergency Response
Provision of immediate response to an Eligible Crisis or Emergency, as needed.
SCHEDULE 2
Project Execution
Section I. Implementation Arrangements
A. Institutional Arrangements.
1. MOF
Without limitation to the provisions of Article V of the General Conditions, the Borrower, through the MOF, shall have the overall responsibility for the implementation of the Project.
2. Project Coordination Unit
Without limitation to the provisions of Article V of the General Conditions, and except as the Bank shall otherwise agree, the Borrower, through MOF, shall maintain at all times throughout the implementation of the Project, a Project Coordination Unit (“PCU”), within the MOF, with composition, resources, terms of reference and functions acceptable to the Bank, and as further detailed in the Project Operations Manual, including the obligation to:
(a) be responsible for the day-to-day implementation of the Project including disbursement, procurement, monitoring and evaluation, reporting, and ensuring compliance with environmental and social obligations and arrangements under the Project, as further elaborated in the POM.
(b) not later than two (2) months after the Effective Date, or such later date as agreed by the Bank, recruit and thereafter maintain throughout Project implementation, the core staff of the PCU, including, inter alia, a Project coordinator, a financial officer, a procurement officer, and an environmental and social specialist, all with adequate experience, qualifications, and terms of reference acceptable to the Bank.
3. Project Steering Committee
The Borrower shall, no later than three (3) months after the Effective Date, or such later date as agreed by the Bank, establish and maintain throughout Project implementation, a steering committee, chaired by the Minister of Finance, with terms of reference, composition, roles and responsibilities acceptable to the Bank and defined in the Project Operations Manual (“Project Steering Committee”), to provide, inter alia, overall strategic guidance and Project oversight, approve the Annual Work Plan and Budget, and review implementation and evaluation reports, as applicable.
administration / administratio n staff and teachers completed as per the last 6 month audit plan; ; 75,000 | staff and teachers completed as per the last 6 month audit plan; ; 75,000 | staff and teachers completed as per the last 6 month audit plan; ; 100,000 | staff and teachers completed as per the last 6 month audit plan; ; 100,000
(b) an aggregate level payroll audit report published for the relevant 6 months 75,000 | (b) an aggregate level payroll audit report published for the relevant 6 months 75,000 | (b) an aggregate level payroll audit report published for the relevant 6 months 100,000 | (b) an aggregate level payroll audit report published for the relevant 6 months 100,000
630,000 | 880,000 | 1,080,000 | 830,000
and published 575,000 | 150,000 | administration / administratio n staff and teachers completed as per the last 6 month audit plan; ; 75,000
5.(ii) 425,000 | | (b) an aggregate level payroll audit report published for the relevant 6 months 75,000
TOTAL: 5,000,000 | 740,000 | 840,000
B. Project Operations Manual
1. The Borrower, through MOF shall maintain a Project Operations Manual (POM), under terms satisfactory to the Bank, which shall include the rules, guidelines, standard documents and procedures for the carrying out of the Project, including inter alia the following:
(a) a detailed description of the institutional and implementation arrangements of the Project;
(b) the Project accounting, auditing, reporting, financial, and disbursement procedures; the environmental and social obligations and arrangements for the Project; the indicators to be used in the monitoring and evaluation of the Project and procedures for Project monitoring, supervision and evaluation, including the format and content of the Project Reports;
(c) detailed description of mechanisms of transfer of Allowances to Eligible Beneficiaries as part of the Eligible Expenditures Program under the Project for PBCs; including eligibility criteria, targeting mechanisms, and procedures in selecting Eligible Beneficiaries, in accordance with the Regulatory Framework;
(d) the Grant Manual;
(e) the Verification Protocol; and
(f) the requirements of the Anti-Corruption Guidelines.
2. The POM may not be assigned, amended, abrogated or waived, or permitted to be assigned, amended, abrogated or waived, or any provision thereof, in a manner which, in the opinion of the Bank, may materially and adversely affect the implementation of the Project. The POM may only be amended in consultation with, and after approval of, the Bank. In case of any-conflict / any conflict between the terms of the POM and those of this Agreement, the terms of this Agreement shall prevail.
C. Annual Work Plan and Budget
1. The Borrower, through the PCU, shall:
(a) unless otherwise agreed with the Bank, prepare and furnish to the Bank not later than November 15 of each year during the implementation of the Project, starting in 2024, a proposed Annual Work Plan and Budget for the next calendar year containing: (i) all activities to be carried out under the Project during that calendar year; and (ii) a proposed financing plan for expenditures required for such activities, setting forth the proposed amounts and sources of financing; and
(b) provide the Bank a reasonable opportunity to exchange views with the Borrower on each such proposed Annual Work Plan and Budget, and shall thereafter ensure that the Project is implemented with due diligence during said following year, in
accordance with such Annual Work Plan and Budget as shall have been approved by the Bank; and not make or allow to be made any change to the approved Annual Work Plan and Budget without the Bank's prior written approval.
D. Environmental and Social Standards.
1. The Borrower shall ensure that the Project is carried out in accordance with the Environmental and Social Standards, in a manner acceptable to the Bank.
2. Without limitation upon paragraph 1 above, the Borrower shall ensure that the Project is implemented in accordance with the Environmental and Social Commitment Plan ("ESCP"), / (“ESCP”), in a manner acceptable to the Bank. To this end, the Borrower shall ensure that:
(a) the measures and actions specified in the ESCP are implemented with due diligence and efficiency, as provided in the ESCP;
(b) sufficient funds are available to cover the costs of implementing the ESCP;
(c) policies and procedures are maintained, and qualified and experienced staff in adequate numbers are retained to implement the ESCP, as provided in the ESCP; and
(d) the ESCP, or any provision thereof, is not amended, repealed, suspended or waived, except as the Bank shall otherwise agree in writing, as specified in the ESCP, and ensure that the revised ESCP is disclosed promptly thereafter.
3. In case of any inconsistencies between the ESCP and the provisions of this Agreement, the provisions of this Agreement shall prevail.
4. The Borrower shall ensure that:
(a) all measures necessary are taken to collect, compile, and furnish to the Bank through regular reports, with the frequency specified in the ESCP, and promptly in a separate report or reports, if so requested by the Bank, information on the status of compliance with the ESCP and the environmental and social instruments referred to therein, all such reports in form and substance acceptable to the Bank, setting out, inter alia: (i) the status of implementation of the ESCP; (ii) conditions, if any, which interfere or threaten to interfere with the implementation of the ESCP; and (iii) corrective and preventive measures taken or required to be taken to address such conditions; and
(b) the Bank is promptly notified of any incident or accident related to or having an impact on the Project which has, or is likely to have, a significant adverse effect on the environment, the affected communities, the public or workers, in accordance with the ESCP, the environmental and social instruments referenced therein and the Environmental and Social Standards.
5. The Borrower shall establish, publicize, maintain and operate an accessible grievance mechanism, to receive and facilitate resolution of concerns and grievances of Project-affected people, and take all measures necessary and appropriate to resolve, or facilitate the resolution of, such concerns and grievances, in a manner acceptable to the Bank.
6. The Borrower shall ensure that all bidding documents and contracts for civil works under the Project include the obligation of contractors ,subcontractors and supervising entities to: (a) comply with the relevant aspects of ESCP and the environmental and social instruments referred to therein; and (b) adopt and enforce codes of conduct that should be provided to and signed by all workers, detailing measures to address environmental, social, health and safety risks, and the risks of sexual exploitation and abuse, sexual harassment and violence against children, all as applicable to such civil works commissioned or carried out pursuant to said contracts.
E. Contingent Emergency Response
1. In order to ensure the proper implementation of contingent emergency response activities under Part 5 of the Project (“Contingent Emergency Response Part”), the Borrower shall ensure that:
(a) a manual (“CERC Manual”) is prepared and adopted in form and substance acceptable to the Bank, which shall set forth detailed implementation arrangements for the Contingent Emergency Response Part, including: (i) any structures or institutional arrangements for coordinating and implementing the Contingent Emergency Response Part; (ii) specific activities which may be included in the Contingent Emergency Response Part, Eligible Expenditures required therefor (“Emergency Expenditures”), and any procedures for such inclusion; (iii) financial management arrangements for the Contingent Emergency Response Part; (iv) procurement methods and procedures for the Contingent Emergency Response Part; (v) documentation required for withdrawals of Financing amounts to finance Emergency Expenditures; (vi) a description of the environmental and social assessment and management arrangements for the Contingent Emergency Response Part; and (vii) a template Emergency Action Plan;
(b) the Emergency Action Plan is prepared and adopted in form and substance acceptable to the Bank;
(c) the Contingent Emergency Response Part is carried out in accordance with the CERC Manual and the Emergency Action Plan; provided, however, that in the event of any inconsistency between the provisions of the CERC Manual or the Emergency Action Plan and this Agreement, the provisions of this Agreement shall prevail; and
(d) neither the CERC Manual or the Emergency Action Plan is amended, suspended, abrogated, repealed or waived without the prior written approval by the Bank.
الجمهورية اللبنانية
من قبل
الممثل المفوض
الاسم:
العنوان:
التاريخ:
البنك الدولي للإنشاء والتعمير
من قبل
الممثل المفوض
الاسم:
العنوان:
التاريخ:
2. The Borrower shall ensure that the structures and arrangements referred to in the CERC Manual are maintained throughout the implementation of the Contingent Emergency Response Part, with adequate staff and resources satisfactory to the Bank.
3. The Borrower shall ensure that:
(a) the environmental and social instruments required for the Contingent Emergency Response Part are prepared, disclosed and adopted in accordance with the CERC Manual and the ESCP, and in form and substance acceptable to the Bank; and
(b) the Contingent Emergency Response Part is carried out in accordance with the environmental and social instruments in a manner acceptable to the Bank.
4. Activities under the Contingency Emergency Response Part shall be undertaken only after an Eligible Crisis or Emergency has occurred.
F. Verification of Achievement of PBCs
1. For purposes of implementing PBC#1 to PBC#5 under Parts 1.1(a), 1.2(a), 2.1(a), 2.2(a), 2.3(a), 3.1 (a)(i) and 3.1(b)(i) of the Project, the Borrower shall engage an independent verification agency by no later than three (3) months after the Effective Date, or such later date as agreed with the Bank, with such qualifications and experience as determined in the Verification Protocol and acceptable to the Bank ("Verification Agent"). / (“Verification Agent”).
2. The Borrower shall cause the Verification Agent to carry out a verification process for the achievement of PBCs which are set forth in the table in Schedule 4 to this Agreement, and furnish to the Bank, not later than sixty (60) days after the verification of compliance of said PBCs, reports on the results of said verification of compliance process of such scope and in such detail as the Bank shall reasonably request.
Section II. Project Monitoring Reporting and Evaluation / Financial Management
A. Project Reports
The Borrower shall furnish to the Bank each Project Report not later than forty-five (45) days after the end of each calendar quarter, covering the calendar quarter.
B. Other Financial Management Arrangements
(a) To facilitate the efficient management of the financial management system, upon each withdrawal of the proceeds of the Loan, the Borrower shall, through MoF, open additional budget lines (budget classification number 1-8-2-123-14-1-3 equivalent to the amount of such withdrawal of the Loan proceeds, provided that the total amount allocated to all such budget lines during the life of the Project up until the disbursement deadline date (as
defined in the World Bank Disbursement Guidelines for Projects) shall not exceed the amount of the Loan. For the purposes of this Loan, said additional budget lines may be opened in the budget of a specific year up until January 31 of the following year and those contracted or not contracted are carried forward per the request of the MoF.
Section III. Withdrawal of Loan Proceeds
A. General.
Without limitation upon the provisions of Article II of the General Conditions and in accordance with the Disbursement and Financial Information Letter, the Borrower may withdraw the proceeds of the Loan to: (a) finance Eligible Expenditures; and (b) pay: (i) the Front-end Fee and (ii) each Interest Rate Cap or Interest Rate Collar premium; in the amount allocated and, if applicable, up to the percentage set forth against each Category of the following table:
Category | Amount of the Loan Allocated (expressed in USD) | Percentage of Expenditures to be financed (inclusive of Taxes)
(1) Eligible Expenditures Program under Parts 1.1(a), 1.2(a). 2.1(a). 2.2(a), 2.3(a), 3.1 (a)(i) and 3.1(b)(i) of the Project | 12,300,000 | 100% of each PBC Amount set out in Schedule 4 (or such lesser percentage as represents the total Eligible Expenditures paid by the Borrower under the Eligible Expenditures Program as of the date of withdrawal)
(2) Goods, works, non-consulting services, and consulting services, Operating Costs, Training under the Project (except for expenditures under Category (1) and Parts 1.3(a) and 2.4(a) of the Project) | 16,128,750 | 100%
(3) Front-end Fee | 71,250 | Amount payable pursuant to Section 2.03 of this Agreement in accordance with Section 2.07 (b) of the General Conditions
(4) Interest Rate Cap or Interest Rate Collar premium | 0 | Amount due pursuant to Section 4.05 (c) of the General Conditions
(5) Emergency Expenditures under Part 5 of the Project | 0 | 100%
TOTAL AMOUNT | 28,500,000
… / | B. Withdrawal Conditions; Withdrawal Period.
1. Notwithstanding the provisions of Part A above, no withdrawal shall be made:
(a) for payments made prior to the Signature Date, except that withdrawals up to an aggregate amount not to exceed $2,000,000 may be made for payments made prior to this date but on or after November 1, 2023, for Eligible Expenditures; or
(b) for payments under Category (1) unless the Bank has received satisfactory evidence that (i) the PBCs set forth in Schedule 4 to this Agreement for which payment is requested have been met and verified in accordance with the Verification Protocol and the POM to be verified by the Verification Agent; (ii) payments for the Eligible Expenditures Program have been made in accordance and in compliance with the procedures set forth in the POM; and (iii) the Borrower has adopted as part of the Regulatory Framework, a decree based on Article 25 of Law No. 112 of the Borrower, setting forth, inter alia, the eligibility criteria, governance arrangements, processing requirements and limit for Allowances throughout the Project period, in form and substance satisfactory to the Bank.
(c) for -Emergency Expenditures under Category (5), unless and until all of the following conditions have been met in respect of said expenditures:
(i) (A) the Borrower has determined that an Eligible Crisis or Emergency has occurred, and has furnished to the Bank a request to withdraw Loan amounts under Category (5); and (B) the Bank has agreed with such determination, accepted said request and notified the Borrower thereof; and
(ii) the Borrower has adopted the CERC Manual and Emergency Action Plan, in form and substance acceptable to the Association.
2. Notwithstanding the provisions of Part A of this Section, payments under Category (1) shall not exceed the maximum amounts allocated to the respective PBC(s) as provided in Schedule 4 to this Agreement.
3. Notwithstanding the provisions of Paragraphs 1 and 2 of this Part B, the Borrower may withdraw the amount, as may be stipulated in the DFIL, as an advance under Category (1), provided, however, that if the PBCs in the opinion of the Bank, are not achieved (or only partially achieved) by the PBC Achievement Due Date, the Borrower shall refund such advance (or portion of such advance as determined by the Bank in accordance with the provisions of Paragraph (4) of this Part B) to the Bank promptly upon notice thereof by the
Bank. Except as the Bank may otherwise determine, the Bank shall cancel all so amounts refunded.
4. Notwithstanding the provisions of paragraphs 1 and 2 of this Part B, if the Bank shall determine, based on the evidence provided by the Borrower under paragraph 3 of this Part B, that any PBC(s) have not been achieved or have been partially achieved by the end of the year during which such PBC(s) were scheduled to be met in accordance with Schedule 4 to this Agreement, the Bank may in its sole discretion, by notice to the Borrower:
(a) withhold in whole or in part the amount of the Loan allocated to such PBCs;
(b) disburse in whole or in part the amount of the Loan allocated to such PBC(s) at any later time when such PBC(s) are met; and/or
(c) reallocate in whole or in part any amount of the Loan allocated to such PBC(s) to other PBC(s) under Category (1) or to other Categories.
5. Notwithstanding the foregoing, if the Bank determines, at any time, that any portion of the amounts disbursed by the Borrower under Category (1) was made for payment of expenditures that are not eligible, or not in compliance with the provisions of the POM, the Borrower shall promptly refund any such amount to the Bank as the Bank shall specify by notice to the Borrower.
6. The Closing Date is March 31, 2027.
SCHEDULE 3
Commitment-Linked Amortization Repayment Schedule
The following table sets forth the Principal Payment Dates of the Loan and the percentage of the total principal amount of the Loan payable on each Principal Payment Date ("Installment Share"). / (“Installment Share”).
Level Principal Repayments' / Repayments¹
Principal Payment Date | Installment Share
On each June 15 and December 15 Beginning June 15, 2029 through June 15, 2047 | 2.63%
On December 15, 2047 | 2.69%
-CHEDULE 4
d Conditions under the Project
ance-Based Conditions (PBCs) and the allocation of the
ategory (1):
Description of achievement 18 months following Effective Date … / Amount of financing (in USD) | Description of achievement 24 months following Effective Date … / Amount of financing (in USD) | Description of achievement 30 months following Effective Date … / Amount of financing (in USD) | Description of achievement 36 months following Effective Date
Amount of financing (in USD) | Amount of financing (in USD) | Amount of financing (in USD) | Amount of financing (in USD) / …
At least 20 % of the identified large taxpayers timely file declarations and pay taxes; and … / 375,000 | At least 40 % of the identified large taxpayers timely file declarations and pay taxes; and … / 394,000 | At least 60 % of the identified large taxpayers timely file declarations and pay taxes; and … / 375,000 | At least 75 % of the identified large taxpayers timely file declarations and pay taxes; and
375,000 | 394,000 | 375,000 | 375,000 / …
Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria … / 375,000 | Number of large taxpayers audited are. at least 3% of all large. taxpayers falling under the New Eligibility Criteria … / 394,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria … / 375,000 | Number of large taxpayers audited are at least 3% of all large taxpayers falling under the New Eligibility Criteria.
375,000 | 394,000 | 375,000 | 375,000 / …
S
Performance-Base
The following table specifies the Performa
amounts of the Loan to each PBC under Ca / C
Performance Based Conditions | Description of achievement 6 months following Effective Date … / Amount of financing (in USD) | Description of achievement 12 months following Effective Date
| Amount of financing (in USD) | Amount of financing (in USD) / …
1a. (i) Increase in the timely filing of tax declarations by large taxpayers … / 2,662,000 | New Eligibility Criteria adopted by the MOF … / 750,000 | VAT and Income Tax LTO (s) have identified large taxpayers using the new criteria for review of declarations
2,662,000 | 750,000 | / … 393,000
1a. (ii) Increase in the number of audits of large tax payers - (of Income Tax -and VAT) … / 1,913,000 | 0 | Number of large taxpayers audited are at least 3% of all large taxpayers falling-under / falling under the New Eligibility Criteria.
1,913,000 | 0 | 394,000
At least 35 cases of risk-based post clearance audits for customs clearances through Port of Beirut are conducted . … / 188,000 | At least 40 risk-based post clearance audits for customs clearances through Port of Beirut are conducted. 150,000 | At least 45 risk-based post clearance audits for customs clearances through Port of Beirut port are conducted.
188,000 | / … 150,000 | 150,000
(a) Completed FY+1 budget consultations within 7 months of the relevant FY … / 95,000 | (a) Updated MTFF for 3 years … / 116,000 | (a) Completed FY+1 budget consultations within 7 months of the relevant FY
95,000 | 116,000 | / … 91,000
(b)Finalized draft FY +1 budget by within 8 months of the relevant FY … / 95,000 | (b) Issued budget call circulars with indicative ceilings within 4 months of the relevant FY … / 117,000 | (b)Finalize draft FY+1 budget by within 8 months of the relevant FY
95,000 | 117,000 | / … 91,000
(c)Submission of FY+1 budget to CoM within 9 months of the relevant FY … / 48,000 | 0 | (c)Submission of FY+1 budget to CoM by within 9 months of the relevant FY
48,000 | 0 | 46,000
1b. Increase in the number of risk-based desk and premise post clearance audits for Port of Beirut customs … / 976,000 | Risked based selection system approved by the competent authority and adopted by the MOF for implementation. … / 150,000 | At least 25 risk-based post clearance audits of customs clearances through Port of Beirut are conducted. … / 188,000 | At least 30 risk-based post clearance audits for customs clearances through Port of Beirut are conducted
976,000 | / … 150,000 | 188,000 | 150,000 / …
2.(i) Timely submission of the Budget to the Council of Ministers … / 625,000 | (a) Updated MTFF for 3 years submitted … / 114,000 | (a) Completed FY+1 budget consultations by within 7 months of the relevant FY … / 95,000 | (a) Updated MTFF for 3 years
625,000 | / … 114,000 | 95,000 | 114,000 / …
2.(ii) … / 626,000 | (b) Issued budget call circulars within 4 months of the relevant FY … / 114,000 | (b)Finalized draft FY +1) budget by within 8 months of the relevant FY … / 95,000 | (b)Issued budget call circulars with indicative ceilings within 4 months of the relevant FY
626,000 | / … 114,000 | 95,000 | 114,000 / …
2.(iii) … / 142,000 | 0 | (c)Submission of FY+1 budget to CoM within 9 months of the relevant FY | 142,000 | 0 | 48,000 | 0
(a) Final accounts 2023 finalized by MOF 131,000 | (a) Final accounts 2024 finalized by MOF 131,000 | (a) Final accounts 2025 finalized by MOF 132,000
(b) Clearance of backlog: Audit reports 2009-2011 46,000 | (b) Clearance of backlog: Audit reports 2012-2013 46,000 | (b) Clearance of backlog: Audit reports 2014-2016 45,000
(c) Audit report 2022 published 60,000 | (c) Audit report 2023 published 60,000 | (c) Audit report 2024 published 60,000
(d)- Reporting on the status of recommendati ons. from previous audit reports 68,000 | (d) Reporting on the status of recommendati ons. from previous audit reports 68,000 | (d) Reporting on the status of recommendati ons. from previous audit reports 63,000
(a) The first 6 months Fiscal Performance Report for current FY is published within 60 days end of period 129,000 | (a) Year-end Fiscal performance Report of previous FY is published within 45 days 64,000 | Quarter 2 and 3 Fiscal Performance Report for current FY is published within 45 days end of period 129,000
0 | (b) Quarter 1 Fiscal Performance Report for current FY is published within 45 days end of period 65,000 | 0
3a.(i) Timely audit report published 788,000 | (a) final accounts 2020 finalized by MOF; 131,000 | (a) final accounts 2021 finalized by MOF 131,000 | (a) final accounts 2022 finalized by MOF 132,000
3a.(ii) 425,000 | (b) Clearance of backlog: Audit reports 2002-2004 197,000 | (b) Clearance of backlog: Audit reports 2005-2006 46,000 | (b) Clearance of backlog: Audit reports 2007-2008 45,000
3a.(iii) 300,000 | 0 | (c) Audit report 2020 published 60,000 | (c) Audit report 2021 published 60,000
3a.(iv) 330,000 | 0 | (d) Reporting on the status of recommenda tions from previous audit reports 68,000 | (d)- Reporting on the status of recommenda tions. from previous audit reports 63,000
3b.(i) Fiscal Performance Report published 750,800 | Fiscal Performance Report of 2022 finalized 292,600 | (a) The first 6 months Fiscal Performance Report for current FY is published within 60 days end of period; 64,000 | (a) Year-end Fiscal performance Report of previous FY is published within 45 days..end / days end of period 72,200
3b.(ii) 202,200 | 0 | (b) Fiscal Performance Report of the first 6 months of 2023 finalized 65,000 | (b) Fiscal Performance Report of the last 6 months of 2023 finalized 72,200
(a) Reduced Time taken for supplier payments to 45 days … / 108,000 | (a) Reduced Time taken for supplier payments to 60 days … / 102,000 | (a) Reduced Time taken for supplier payments to 60 days
108,000 | / … 102,000 | 102,000 / …
(b) Pension files completed within 4 months … / 106,000 | (b) Pension files completed within 3 months … / 99,000 | (b) Pension files completed within 3 months
106,000 | / … 99,000 | 99,000 / …
(c) Processing changes in pension beneficiaries within 3 months … / 106,000 | (c) Processing changes in pension beneficiaries within 2 months … / 99,000 | (c) Processing changes in pension beneficiaries within 2 months
106,000 | / … 99,000 | 99,000 / …
(a) payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan ; … / 84,000 | (a) payroll andits / audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan ; … / 66,000 | (a) payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan ;
84,000 | / … 66,000 | 66,000 / …
(b) an aggregate level payroll audit report published for the relevant 6 months … / 56,000 | (b) an aggregate level payroll audit report published for the relevant 6 months … / 44,000 | (b) an aggregate level payroll audit report published for the relevant 6 months
56,000 | / … 44,000 | 44,000 / …
2,108,000 | 1,977,000 | 1,967,000
4.(i) System-generated reports show reduced time for reviews of Payment documents for third parties and pension payments … / 624,000 | (a) Reduced Time taken for supplier payments to 60 days … / 102,000 | (a) Reduced Time taken for supplier payments to 60 days … / 108,000 | (a) Reduced Time taken for supplier payments to 45 days
624,000 | / … 102,000 | 108,000 | 102,000 / …
4.(ii) … / 608,000 | (b) Pension files completed within 5 months … / 99,000 | (b) Pension files completed within 5 months … / 106,000 | (b) Pension files completed within 4 months
608,000 | / … 99,000 | 106,000 | 99,000 / …
4.(iii) … / 608,000 | (c) Processing changes in pension beneficiaries within 4 months … / 99,000 | (c) Processing changes in pension beneficiaries within 4 months … / 106,000 | (c) Processing changes in pension beneficiaries within 3 months
608,000 | / … 99,000 | 106,000 | 99,000 / …
5.(i) Regular Payroll Audits completed and published … / 476,000 | Preparation of audit plan … / 110,000 | (a) payroll andits / audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan ; 84,000 | (a) payroll audits of Lebanon civilian public administration staff and teachers completed as per the last 6 month audit plan ;
476,000 | 110,000 | 84,000 | 66,000
5.(ii) … / 244,000 | 0 | (b) an aggregate level payroll audit report published for the relevant 6 months … / 56,000 | (b) an aggregate level payroll audit report published for the relevant 6 months
244,000 | 0 | 56,000 | 44,000
TOTAL: 12,300,000 | 2,158,600 | 2,107,000 | 1,982,400
APPENDIX
Definitions
1. “Allowances” means the incremental costs incurred by the Borrower in the implementation of Parts 1.1(a), 1.2(a). 2.1(a). 2.2(a), 2.3(a), 3.1 (a)(i) and 3.1(b)(i) of the Project by the Eligible Beneficiaries, as permitted under the Borrower’s Regulatory Framework, excluding Operating Costs and civil servant salaries.
2. “Annual Work Plan and Budget” means any or all of the work plans prepared annually by the Borrower in accordance with the provisions of Section I.C of Schedule 2 to this Agreement, as further detailed in the Project Operations Manual and as approved by the Bank.
3. “Anti-Corruption Guidelines” means, for purposes of paragraph 6 of the Appendix to the General Conditions, the “Guidelines on Preventing and Combating Fraud and Corruption in Projects Financed by IBRD Loans and IDA Credits and Grants”, dated October 15, 2006 and revised in January 2011 and as of July 1, 2016.
4. “Category” means a category set forth in the table in Section III A / III.A of Schedule 2 to this Agreement.
5. “CERC Manual” means the manual referred to in Section I.E of Schedule 2 to this Agreement, as such manual may be updated from time to time with the agreement of the Bank, and which is an integral part of the Project Operations Manual.
6. “Central Inspection” or “CI” means the Borrower’s central inspection unit established and operating within the Presidency of the Council of Ministers under Law of December 12, 1958, and the Legislative Decree No. 115 of June 12, 1959, or its legal successor.
7. “CoM” means the Borrower’s Council of Ministers or its legal successor.
8. “Contingent Emergency Response Part” means any activity or activities to be carried out under Part 5 of the Project to respond to an Eligible Crisis or Emergency.
9. “Court of Accounts” or “CoA” means the Borrower’s administrative court established by the Public Accounting Law of January 16, 1951, and operating to supervise the management of public funds by auditing and setting the accounts of the Government, ruling on validity and legality of its transactions, or its legal successor.
10. “Customs” means the Borrower’s customs administration, established and operating pursuant to Decree No. 4461 of December 15, 2000, or its legal successor.
الجدول ١
وصف المشروع
يهدف المشروع إلى دعم المقترض في استعادة المهام الأساسية لتعبئة الإيرادات المحلية وتخصيص الموارد العامة واستخدامها بشكل خاضع للمساءلة.
يتألف المشروع من الأجزاء الآتية:
الجزء ١: تأمين استقرار إدارة الإيرادات المحلية.
توفير الدعم لوظائف الإيرادات الهامة التي تُعتبر ضرورية لزيادة تحصيل الإيرادات الضريبية وغير الضريبية، بما في ذلك عن طريق:
١,١ تعزيز دائرة كبار المكلفين وفريق عمل للديون الكبيرة، عن طريق، على سبيل المثال لا الحصر،
أ) توفير الدعم التشغيلي لتعزيز الامتثال الضريبي، بما في ذلك استرداد المتأخرات الضريبية وتطبيق خطة الامتثال الضريبي؛
ب) توفير التدريب وبناء قدرات الموظفين في ما يتعلق بثقافة المكلفين على سبيل المثال لا الحصر؛ و
ت) توفير الألواح الشمسية لتوليد الكهرباء.
١,٢ استعادة الوظائف الأساسية للجمارك عن طريق، على سبيل المثال لا الحصر:
أ) توفير الدعم التشغيلي لضمان التسيير الأساسي لإدارة الجمارك بما يتوافق مع قانون الجمارك؛
و
ب) توفير التدريب وبناء قدرات الموظفين، كما المساعدة الفنية لدعم إعداد خطة استراتيجية؛ و
ت) توفير الألواح الشمسية لتوليد الكهرباء.
١,٣ استعادة أنظمة تكنولوجيا المعلومات والاتصالات لإدارة الإيرادات عن طريق، على سبيل المثال لا الحصر:
أ) إجراء أعمال الصيانة والتحديث للأجهزة والبرمجيات وقدرات تكنولوجيا المعلومات والاتصالات لأنظمة تكنولوجيا المعلومات والاتصالات الضريبية والجمركية؛ و
ب) إيجاد تكامل بين أنظمة الإيرادات والجمارك لتعزيز تشارك البيانات من أجل اتخاذ القرارات الحاسمة وتعزيز وظائف المراجعة.
11. “Emergency Expenditures” means any of the eligible expenditures set forth in the CERC Manual referred to in Section I.E of Schedule 2 to this Agreement and required for the Contingent Emergency Response Part.
12. “Emergency Action Plan” means the plan referred to in Section I.E, detailing the activities, budget, implementation plan, and monitoring and evaluation arrangements, to respond to the Eligible Crisis or Emergency.
13. “Eligible Beneficiary” means the Borrower’s civil servants eligible to receive an Allowance under the Project in accordance with the Regulatory Framework and the terms of the POM; and “Eligible Beneficiaries” means more than one Eligible Beneficiary.
14. “Eligible Crisis or Emergency” means an event that has caused, or is likely to imminently cause, a major adverse economic and/or social impact to the Borrower, associated with a natural or man-made crisis or disaster.
15. “Eligible Expenditures Program” means the Goods, works, non-consulting services, and consulting services, Allowances for Eligible Beneficiaries, Operating Costs, Training incurred by the Borrower for the implementation of Parts 1.1(a), 1.2(a). 2.1(a). 2.2(a), 2.3(a), 3.1 (a)(i) and 3.1(b)(i) of the Project.
16. “Environmental and Social Commitment Plan” or “ESCP” means the environmental and social commitment plan for the Project, dated December 22, 2023, as the same may be amended from time to time in accordance with the provisions thereof, which sets out the material measures and actions that the Borrower shall carry out or cause to be carried out to address the potential environmental and social risks and impacts of the Project, including the timeframes of the actions and measures, institutional, staffing, training, monitoring and reporting arrangements, and any environmental and social instruments to be prepared thereunder.
17. “Environmental and Social Standards” or “ESSs” means, collectively: (i) “Environmental and Social Standard 1: Assessment and Management of Environmental and Social Risks and Impacts”; (ii) “Environmental and Social Standard 2: Labor and Working Conditions”; (iii) “Environmental and Social Standard 3: Resource Efficiency and Pollution Prevention and Management”; (iv) “Environmental and Social Standard 4: Community Health and Safety”; (v) “Environmental and Social Standard 5: Land Acquisition, Restrictions on Land Use and Involuntary Resettlement”; (vi) “Environmental and Social Standard 6: Biodiversity Conservation and Sustainable Management of Living Natural Resources”; (vii) “Environmental and Social Standard 7: Indigenous Peoples/Sub-Saharan Historically Underserved Traditional Local Communities”; (viii) “Environmental and Social Standard 8: Cultural Heritage”; (ix) “Environmental and Social Standard 9: Financial Intermediaries”; (x) “Environmental and Social Standard 10: Stakeholder Engagement and Information Disclosure”; effective on October 1, 2018, as published by the Bank.
18. “Fiscal Performance Report” means the monthly comparative report on total revenues and expenditure (on a cash basis) published by the Ministry of Finance.
19. "Fiscal Year" / “Fiscal Year” or "FY" / “FY” means the Borrower's / Borrower’s fiscal year, running from January 1 to the next following December 31.
20. "General Conditions" / “General Conditions” means the "International / “International Bank for Reconstruction and Development General Conditions for IBRD Financing, Investment Project Financing", / Financing”, dated December 14, 2018 (Last revised on July 15, 2023).
21. "Grant Manual" / “Grant Manual” means the manual adopted by the Borrower, describing and setting forth procedures for implementation of Part 1.3(a) and Part 2.4(a) of the Project and institutional arrangements, consistent with the provisions of the LFF Grant Agreement, and as the same may be amended from time to time with the prior written approval of the Bank.
22. "Grievance Mechanism" / “Grievance Mechanism” or "GM" / “GM” means the grievance mechanism established, publicized, maintained and operated by the Borrower to receive and facilitate the resolution of concerns and grievances in relation to the Project, in accordance with the ESCP.
23. "Institute / “Institute of Finance" / Finance” means "Institut / “Institut des Finances Basil Fuleihan", / Fuleihan”, the Borrower's, / Borrower’s, specialized autonomous public institution that contributes to capacity development in public financial management and governance through policy research, training and partnership building, established and operating under MOF pursuant to Article 49 of the Borrower's / Borrower’s Budget Law no. 497/2003 or its legal successor.
24. "IT" / “IT” means information technology.
25. "Large / “Large Taxpayer Office" / Office” or "LTO" / “LTO” means the dedicated unit for administration of taxes of the largest taxpayers, established and operating pursuant to the Borrower's / Borrower’s Decree no. 10063 of 2003.
26. "LFF Grant" / “LFF Grant” means the Grant No. TF0C3381 in an amount not to exceed five million five hundred thousand United States Dollars ($5,500,000) to be provided by the Bank in its capacity as the administrator of the Lebanon Financing Facility for Reform, Recovery and Reconstruction Multi-Donor Trust Fund, to assist the Borrower in financing the Project.
27. "LFF / “LFF Grant Agreement" / Agreement” means the agreement of the same date of this Agreement, between the Borrower and the Bank in its capacity as the administrator of the Lebanon Financing Facility for Reform, Recovery and Reconstruction Multi-Donor Trust Fund for the LFF Grant to assist in financing the Project. "LFF / “LFF Grant Agreement" / Agreement” includes all appendices, schedules and agreements supplemental to the LFF Grant Agreement.
28. "MOF" / “MOF” means the Borrower's / Borrower’s ministry in charge of finance, or any legal successor thereto acceptable to the Bank.
29. “MTFF” / "MTFF" means medium-term fiscal framework tool of the MOF used for medium term budgeting and fiscal planning.
30. “New / "New Eligibility Criteria” / Criteria" means the eligibility criteria for taxpayers falling under the Large Taxpayers Office to be established to include only the largest taxpayers by revenue threshold across tax types, including VAT, corporate income tax (CIT) and pay as you earn (PAYE) for the purposes of PBC#3.
31. “Operating Costs” / "Operating Costs" means incremental costs incurred on account of the Project coordination, implementation and monitoring, including expenditures for vehicle operation and maintenance, audit fees, legal fees (as required), maintenance of equipment, office supplies and consumables, utilities, communication, translation and interpretation, bank charges, Project-related travel, including per diem and accommodation, and other miscellaneous costs directly associated with the Project implementation and salaries of Project staff, but excluding salaries of the Borrower’s / Borrower's civil servants, meeting allowances, other sitting allowances, salary top ups and all honoraria.
32. “Oversight / "Oversight and Accountability Institutions” / Institutions" means, the Central Inspection, the Court of Accounts, Public Procurement Authority and other public procurement institutions selected for their oversight, audit, and/or inspection mandates, to be selected by the Borrower for the purposes of Part 3 of the Project with the prior approval of the Bank.
33. “Performance-Based Condition” / "Performance-Based Condition" or “PBC” / "PBC" means a performance-based condition referred to in Schedule 4 to this Agreement; and “PBCs” / "PBCs" means more than one PBC.
34. “Procurement Regulations” / "Procurement Regulations" means, for purposes of paragraph 85 of the Appendix to the General Conditions, the “World / "World Bank Procurement Regulations for IPF Borrowers”, / Borrowers", dated September 2023.
35. “Project / "Project Coordination Unit” / Unit" or “PCU” / "PCU" means the unit within MOF in charge of the day-to-day management, implementation, monitoring and evaluation of the Project, as referred to in Section I.A.2 of Schedule 2 to this Agreement and as further detailed in the Project Operations Manual; or any successor thereto acceptable to the Bank.
36. “Project / "Project Operations Manual” / Manual" or “POM” / "POM" means the manual referred to in Section I.B of Schedule 2 to this Agreement, adopted by the Borrower, describing and setting forth procedures for implementation of the Project and institutional arrangements, consistent with the provisions of this Agreement, and as the same may be amended from time to time with the prior written approval of the Bank.
37. “Project / "Project Steering Committee” / Committee" means the committee established for the overall oversight of the Project, as referred to in Section I.A.3 of Schedule 2 to this Agreement and further detailed in said Project Operations Manual, or any successor thereto acceptable to the Bank.
38. “Public Procurement Authority” means the Borrower’s specialized autonomous public institution on public procurement, established and operating pursuant to the Borrower’s Public Procurement Law No. 244/2021, or its legal successor.
39. “Regulatory Framework” means the Borrower’s Law No. 112 dated December 6, 1959; decree to be issued by the Council of Ministers pursuant to Article 25 of Law No. 112 regarding the compensation and Allowances of civil servants, as referred to in paragraph 1 of Section III.B of Schedule 2 to this Agreement, and any subsequent related implementing decisions, as applicable.”
40. “Signature Date” means the later of the two dates on which the Borrower and the Bank signed this Agreement and such definition applies to all references to “the date of the Loan Agreement” in the General Conditions.
41. “Training” means Project related study tours, training courses, seminars, workshops and other training activities, not included under service providers’ contracts, including costs of training materials, space and equipment rental, reasonable and necessary local and international travel by participants in training activities, reasonable lodging and accommodation, subsistence and local and international per diem of trainees and trainers, registration, tuition and facilitators’ fees, translation and interpretation, and other training related miscellaneous costs, all based on budgets acceptable to the Bank.
42. “VAT” means value-added tax.
43. “Verification Agent” means an independent verification agency or agencies, satisfactory to the Bank, hired under the Project to conduct technical audit as provided under Section I.F of Schedule 2 to this Agreement.
44. “Verification Protocol” means the Recipient’s protocol detailing the means by which the fulfillment of the Performance-Based Conditions will be verified under the Project, as further described in the Project Operations Manual.
AGREED MINUTES OF NEGOTIATIONS BETWEEN
THE LEBANESE REPUBLIC
AND
INTERNATIONAL BANK FOR RECONSTRUCTION AND DEVELOPMENT (IBRD)
REGARDING PROPOSED FINANCING FOR THE LEBANON: FISCAL MANAGEMENT PROJECT
December 22, 2023 – January 3, 2024
1. Introduction: Technical Discussions followed by Negotiations related to the proposed financing (“Financing”) from the International Bank for Reconstruction and Development (“IBRD” or “World Bank”) in the amount of twenty eight million five hundred thousand United States Dollars (US$ 28,500,000) and the Lebanese Financing Facility for Reform, Recovery and Reconstruction Multi Donor Trust Fund (“LFF”) in the amount of five million five hundred thousand United States Dollars (US$ 5,500,000) to the Lebanese Republic for the Lebanon: Fiscal Management Project (P181155) (the Project) were held virtually through Teams videoconference and in-person in Beirut between December 21 and December 22, 2023. The list of participants to the negotiations representing the Borrower (the “Borrower Delegation”) and representing IBRD (the “IBRD Delegation”) is attached as Annex 1 to these Minutes (collectively the Borrower Delegation and the IBRD Delegation are referred to as the “Parties”). These Minutes record the key agreements and conclusions reached during the negotiations.
2. Authority to Negotiate: The Borrower Delegation provided a letter to the IBRD Delegation, dated December 19, 2023, signed by His Excellency Minister of Finance, indicating the members of the Borrower Delegation authorized to participate in the negotiations and appointing His Excellency Mr. Youssef El Khalil (Minister of Finance), as the head of the Borrower Delegation.
3. Documents Discussed: - The Parties reviewed and agreed on the negotiated draft versions of the following: (i) the Project Appraisal Document; (ii) the draft Loan Agreement (LA), (iii) the draft LFF Grant Agreement; (iii) the draft Disbursement and Financing Information Letter, (iv) the Environmental and Social Commitment Plan (ESCP), and (v) the Procurement Plan. The proposed corrections and edits were directly incorporated into the documents, and the draft Loan and Grant Agreements was agreed upon after a thorough discussion (Annex 2).
4. Project Development Objective and Components: The Project Development Objective (PDO) was slightly amended by replacing ‘government of Lebanon’ with “Lebanese Republic”. Accordingly, the PDO of the Project is “to support the Lebanese Republic restore the basic functions of domestic revenue mobilization and accountable allocation in the use of public resources.”
5. The Project design and components were reviewed, and no major modifications were identified. Considering the currently expected date of presentation for Board of Executive Directors’ / Directors' approval on February 14, 2024, the periods for PBCs reflected in the PAD have been adjusted. It was discussed that for the non-PBC intermediate indicator on ‘reduced bank accounts outside of the main account 36’, the baseline will be determined within 2 months of Project implementation and
recorded in the ISR. The Project Appraisal Document (Annex 7) describes the detailed Project design and components.
6. Implementation Arrangements: Key features of the implementing arrangements were agreed as: (a) a Steering Committee comprising of heads of relevant agencies and directorates chaired by the Minister of Finance or a person nominated by the Minister; (b) A Project Coordination Unit (PCU) will monitor and facilitate day to day project implementation activities and liaise with and report progress to the World Bank task team; (c) an interim Project team will be appointed by the MOF until the PCU is established and staffed under the Loan Agreement; (c) the agencies and departments involved in Project activities will be involved in the procurement decision making, managing consultants and implementing Project activities in their respective areas; (d) an independent verification agent will verify the achievement of the Performance Based Conditions; (e) external auditor will audit the project financial statements and the payment of staff allowances; and (f) a Project Operations Manual, including a Grant Manual, will describe the work flow procedures and the internal controls of the Project.
7. Regulatory Framework: The Parties clarified that MoF will immediately inform the World Bank of any proposed modification to the Regulatory Framework in accordance with Section 5.10 of the General Conditions and Section 2.10 of the Standard Conditions. In this regard, without prejudice to the World Bank’s right to exercise any legal remedies in accordance with Article IV of the Loan Agreement and the General Conditions as well as Article IV the LFF Grant Agreement and the Standard Conditions, respectively, if in the opinion of the World Bank, any such modification will affect materially and adversely the Borrower’s ability to perform any of its obligations under the Loan Agreement and/or LFF Grant Agreement, the World Bank intends to consult with the Borrower in line with Section 5.10 of the General Conditions and Section 2.10 of the Standard Conditions.
8. The following clarifications were agreed upon by the parties:
9. Section 5.01(b) of the Loan Agreement: ‘Establishment’ of a PCU means issuing a decision by the Minister of Finance describing the mandate, the composition, and the resources available for said PCU, as well as a timeline for the recruitment of the staff of the PCU that is aligned with the terms of the Loan Agreement;
10. Section 5.01(a) of the Loan Agreement: “The LFF Grant Agreement has been executed and delivered and all conditions precedent to the effectiveness of said agreement” means that the LFF Grant Agreement shall be duly signed by the parties, and all related conditions of effectiveness shall be fulfilled;
11. Manuals: Considering that the LFF Grant Agreement is subject to the approval by the Cabinet of Ministers, while the Loan Agreement is subject to the ratification by the Parliament, the Delegations discussed that the LFF Grant may become available before the IBRD Loan. As such, in order to ensure timely implementation of the LFF Grant, a separate grant manual will be prepared for the LFF Grant as an effectiveness condition to the LFF Grant Agreement, under terms and conditions satisfactory to the Bank. Said Grant Manual will be incorporated in due course into the Project Operations Manual (POM). The POM is set as an effectiveness condition to the Loan Agreement.
12. The term “Allowances” is defined in the Appendix, including in the definition of the term “Eligible Expenditures Program” for PBCs.
13. Closing Date: It was agreed to set the Project’s Closing Date to March 31, 2027.
14. Opinions as Effectiveness Conditions.
15. Loan Agreement: The Delegations discussed that, considering the caretaker status of the Government, the Bank will require a legal opinion from the Borrower as a condition of effectiveness pursuant to Article 9.02(a) of the General Conditions, showing that the Loan Agreement has been duly authorized or ratified by, and executed and delivered on its behalf of the Borrower and is legally binding upon it in accordance with its terms.
16. LFF Grant Agreement: As part of the evidence to be furnished pursuant to Section 5.01(b), on effectiveness, there shall be furnished to the Bank an opinion satisfactory to the Bank showing that, on behalf of the Recipient, this Agreement has been duly authorized or ratified by, and executed and delivered on its behalf and is legally binding upon it in accordance with its terms.
17. The Government Delegation informed the Bank Delegation that the counsel from the Ministry of Justice will provide in due course both legal opinions for the Project to become effective.
18. Disbursement and Financial Information Letter (DFIL): The DFIL, covering both the IBRD Loan and the LFF Grant, was discussed and agreed between the Parties. The Parties clarified that the Designated Account mentioned in the DFIL will be held at the Borrower's Central Bank, in USD. Disbursements will follow the guidelines and the modalities specified in the Loan and Grant Agreements and in the Disbursement and Financial Information Letters. The advance to the DA will be based on a six-month expenditure forecast. The LFF Grant will use only the direct payment method. The documentation of eligible expenditures will be based on Interim Financial Reports (IFR). Details about disbursement methods are available in the DFIL. The negotiated version of the DFIL, incorporating all the changes, is attached in Annex 3 to these minutes.
19. Financial Management: The Borrower, through the Project Team/PCU (as applicable), shall prepare and furnish to the Bank, not later than forty-five (45) days after the end of each calendar quarter, consolidated interim unaudited financial reports (“IFR”) for the Project covering the quarter. Each audit of the consolidated Financial Statements shall cover the period of one fiscal year of the Project, commencing with the first year in which the first withdrawal was made. The audited consolidated Financial Statements for each such period shall be furnished to the Bank not later than six (6) months after the end of such period. The PCU will recruit an Independent Verification Agent and an external auditor with Terms of Reference acceptable to the Bank to review and validate Project activities. Details of the approach, methodologies and terms of references will be elaborated in the POM. It was agreed that the Loan funds will be channeled from the World Bank to the MOF Treasury Account at the Central Bank, and then in turn transferred by the MOF to the Project Designated Account in the Central Bank in USD. The option of direct payment will be available as stated in the DFIL. The reimbursement option is available for the Loan Agreement.
20. Loan’s / Loan's terms, charge, and amortization schedule: The proposed 28.5 million USD variable spread loan will be repaid in line with Borrower repayment terms in loan choice worksheet (LCW) dated December 21, 2023 with a total maturity of 24 years, including a grace period of 5 years, repayment dates of June 15 and December 15 for commitment linked, level repayments with front-end fees financed out of loan proceeds, with the option of financing caps and collars. The amortization schedule is based on an estimated WBG Board approval date of February 14, 2024. Should the Board date change, the amortization schedule may be affected, and will be updated and shared with the Borrower accordingly. The Closing Date is confirmed as March 31, 2027. The signed Loan Choice Worksheet (LCW) and the discussed and agreed amortization schedule are both attached to these minutes (Annex 4 and Annex 5, respectively).
21. Procurement: The IBRD Delegation clarified that procurement will be carried out in accordance with the World Bank Procurement Regulations for Investment Project Financing, dated September 2023, the Procurement Plan approved by IBRD and the procurement procedures to be outlined in the POM. The Project Procurement Strategy for Development (PPSD) and Procurement Plan will be cleared by IBRD prior to launching any procurement process. Both documents will be updated as needed throughout Project implementation, with IBRD prior approval. The initial procurement plan dated December 2023is / 2023 is attached to the minutes of negotiations (Annex 8).
22. Environmental and Social Framework (ESF): The Parties agreed on the ESCP, dated December 22, 2023 (Annex 6). The IBRD Delegation noted that the implementation of the document is part of the obligations to be fulfilled under the Loan Agreement and the LFF Grant Agreement, and contains mandatory requirements for the Borrower.
23. Access to Information: Pursuant to the World Bank Policy on Access to Information, IBRD will disclose the Project Appraisal Document, the related legal agreements and other information related to the operation and the legal agreements, including any supplemental letters. The Borrower's / Borrower’s Delegation confirmed that the Bank may publicly release this Project Appraisal Document upon the approval of the operation by the Bank’s Executive Directors. The agreed version is attached to these Minutes as Annex 7.
24. Project Reports will cover only the LFF Grant Agreement until the Loan Agreement becomes effective.
25. Signing of the Legal Agreements. The Bank Delegation reminds that as of July 1, 2023, the Bank migrated to the use of electronic signatures (e-Signatures) as a default modality for signing all IBRD/IDA financing agreements concluded with the Bank where both Bank and Borrower are expected to sign electronically via DocuSign. If the Lebanese Republic is unable to use e-Signatures only, it can use the ‘dual modality’ where (i) both parties will first sign fully electronically in DocuSign; and thereafter (ii) Borrower prints out the fully e-signed agreement as needed and countersigns manually, in wet ink, next to their electronic signature. The Borrower Delegation indicated the Lebanese Republic’s readiness to electronically sign the Loan Agreement by using the ‘dual modality’ above, after the approval of the Project by the Bank’s Board of Executive Directors and Senior Management (RVP), as applicable.
26. Next Steps. Upon the signing of these Minutes, the Borrower's / Borrower’s Delegation has confirmed that no further action is necessary from the Borrower to authorize the submission of the Project to the World Bank Board of Executive Directors for consideration. The proposed Project is expected to be presented to the Board on February 14, 2024. The notice of approval will be communicated to the Borrower and the MOF will request authorization of the Council of Ministers to sign the Loan Agreement and the LFF Grant Agreement. Upon approval, the Borrower Delegation and the Bank Delegation will arrange for the signing of the Loan Agreement and the LFF Grant Agreement between the Borrower and the IBRD using the modality described in the paragraph above of these Minutes.
On behalf of the International Bank for Reconstruction and Development
Jiwanka B. Wickramasinghe
Head of Delegation
Signed on: 03-Jan-2024
ment
Financial Information Letter